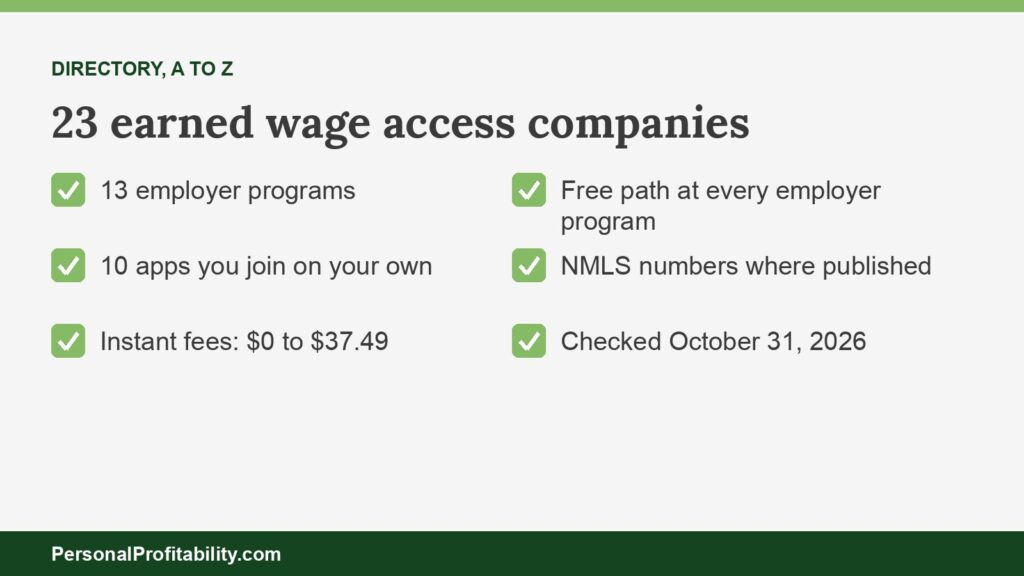
This directory lists 23 earned wage access companies: 13 that work through your employer, such as DailyPay and ZayZoon, and 10 apps you join on your own, such as EarnIn and Dave. Instant fees run from $0 to $37.49.
Eric Rosenberg, who founded Personal Profitability, wrote for Payactiv as a freelancer and later worked there as a marketing manager, until June 2026. Nobody at Payactiv reviewed this page. We held Payactiv to its own published fees and terms, the same standard we used for every other company here.
Personal Profitability may earn a commission from partner links on this page, at no cost to you. Partners don’t decide what we recommend or where it ranks. Fees and terms are each company’s as of 2026-10-31. Confirm them on the company’s site before you apply.
Last checked: October 31, 2026, against each company’s own fee and terms pages.
Earned wage access, or EWA, lets you take part of the pay you’ve already earned before payday. Two kinds of companies sell EWA. Employer programs plug into payroll and take repayment from your next paycheck. Direct-to-consumer apps read your bank deposits and debit your account on payday. This page is a reference, not a ranking. For our ranked picks, read the employer EWA provider rankings and the EWA app roundup. New to the product? Start with our earned wage access guide.
What counts as an earned wage access company
An earned wage access company is a financial services provider that lets employees access their earned wages before payday, for a fee or for free, and collects the funds back on payday. Some sell the service to employers as a benefit, and others sell an app directly to consumers.
EWA isn’t the same as payday loans or personal loans. You don’t pay interest, and most companies run no credit check. Still, regulators disagree about whether the direct-to-consumer apps make loans, so the line matters when you compare fees. This directory includes both kinds and marks each one in the Model column.
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
Earned wage access companies directory
The directory below covers each company’s model, who pays, the free way to get your money, the instant fee, the cap, payroll connections, and license numbers, all taken from each company’s own pages on October 31, 2026.
The table sorts companies alphabetically by company name. The order is not a ranking. A blank or “not published” cell means we couldn’t find the fact on the company’s public pages, so we didn’t guess.
| Company | Model | Who pays | Free path | Instant fee | Cap | Payroll connections | License or NMLS |
|---|---|---|---|---|---|---|---|
| Branch | Employer | Worker pays for instant. $0 to the business | Branch Wallet or standard ACH | “Small fee,” amount not published | Up to 50% of earned wages | Not published | Not published |
| Brigit | Direct | Member, through a monthly plan | Free plan on request by email | Plans $8.99–$15.99 a month. Express $0.99–$5.99 on Plus, per its terms | $25–$500 ($25–$250 in Maine) | None, bank-linked | Not published |
| Chime Enterprise EWA | Employer | Nobody, for instant to Chime | Instant to a Chime account, $0 | $0. No paid instant option | Not published | Workday, UKG | Not published |
| Chime MyPay | Direct (Chime members) | Member, for instant | Scheduled transfer within 24 hours | 3%, $2 minimum, $5 maximum | $20–$1,000 a pay period | None. Needs $200 in direct deposits to Chime | Line of credit from The Bancorp Bank or Stride Bank |
| Clair | Employer, through payroll software | Worker, for instant | Standard, 1–3 business days | Up to $4.99 (QuickBooks) | Not published | QuickBooks Payroll, Gusto | Pathward, N.A. originates advances. Not offered in CT, MA, MN, NM, NV, or SD |
| Cleo | Direct | Subscriber | Standard, 3–4 days | $4.49–$14.99 express | Not published | None | Not published |
| Current | Direct (Current members) | Member, for instant | Free if you wait up to 3 days | Shown in the app only | $25–$1,000 | Payroll has to land in Current | Finco Advance LLC makes advances |
| DailyPay | Employer | Worker, unless the employer covers fees | $0, 1–3 business days | $3.49 (varies by employer) | $1,000 a day (Program Terms) | 180+ integrations | NMLS 2587396, NV EWA00004, WI 2587396EWA |
| Dave | Direct | Member: up to $5 a month plus the advance fee | None. Every advance carries the fee | 5%, $5 minimum, $15 maximum on its fee schedule (removed for some members in 2026), plus 1.5% to an outside debit card | $25–$500 | None, bank-linked | NMLS 2675197 (Dave Operating LLC) |
| Dayforce Flex Pay | Employer (Dayforce Payroll) | Included with Dayforce Payroll | On-demand pay at $0 | $0. Card fees may apply | Not published | Dayforce Payroll only | Dayforce Wallet card from Green Dot Bank |
| EarnIn | Direct | Optional tips plus Lightning Speed fees | Standard, usually 1–2 business days, up to 3 | $3.99–$8.99 Lightning Speed in most states | $200 a day, $1,000 a pay period | None, bank-linked | Not published on pages checked |
| FloatMe | Direct | Member, for instant | Standard ACH | $1–$10 Instant Float | $200, first Floats $10–$50 | None | Not published |
| Immediate | Employer | Worker, for instant transfers. $0 to employers | Merchant cards, paycard, next-day ACH | “Flat nominal fee,” amount not published | Not published | ADP RUN, isolved, and others | NMLS 2592436 |
| Instant Financial | Employer | Not published | Free options listed | Not published | Not published | Not published | NMLS 1869318. Card from Sutton Bank |
| Klover | Direct | Member, for express or Klover+ | Standard, 2–5 business days | $3.99 on $25 up to $37.49 on $750 | Up to $750 on its fee chart | None, bank-linked | Not published |
| MoneyLion Instacash | Direct | Member, for Turbo delivery | Standard to a MoneyLion Spend account, 1–2 days | Turbo 7.5% to Spend, capped at $14.99 | $500, or $1,000 with Spend direct deposit | None | ML Plus LLC, NMLS 2621850, plus state EWA licenses |
| OnePay @Work | Employer | Employer or worker | Free when the employer sets it up that way | “Small fee,” amount not published | A percentage of net earnings | Not published | Not published |
| Payactiv | Employer | Worker, for instant. $0 to the employer | ACH in 1–3 days, Amazon load, Payactiv Visa with $200+ direct deposit | $2.49 to $3.49 by destination | “A portion” of earned wages | 150+ systems | NMLS 2591928, WI 2591928EWA |
| Rain | Employer | Worker, for instant | ACH, 1–3 days | “Small fee,” amount not published | 50% “in most cases” | 100+ connectors | NMLS 2623400, WI 2623400EWA |
| Stream | Employer | Worker, for instant | Standard transfer | “Small flat fee” set by the employer deal | Not published on pages checked | Not published | NMLS 2547041 |
| Tapcheck | Employer | Worker. $0 to the employer | Prizeout gift cards | One flat fee, amount not published | Typically $100 a day | 300+ providers | NMLS 2634283 |
| Tilt (formerly Empower) | Direct | Member, $8 a month after a 14-day trial | None after the trial | In Tilt’s Terms, not on its site | $10–$500 | None | Not published |
| ZayZoon | Employer | Worker, unless the employer pays | ZayZoon Boost and ZayZoon Visa, $0 | Up to $5 (Connecticut: $4, once a pay period) | Up to 50%, $200 a payout, about $1,000 a pay period (help center) | 300+ (homepage) or 130+ (employer page) | NMLS 2635812, plus 10 state licenses |
The table shows two patterns. Every employer program in the table offers a free path, and most charge $5 or less for instant pay. The direct-to-consumer apps charge more for speed, and Dave, Brigit, Tilt, and Cleo collect money whether or not you pay for instant delivery. Our earned wage access fees page runs the cost per $100 for each company.
Employer-integrated EWA companies
Employer EWA companies connect to payroll or timekeeping, let you take part of your earned pay, and recover the money through a payroll deduction on payday. As a result, you can use one only when your employer offers the program to employees.
Still, these programs usually cost employees less. A December 2025 CFPB advisory opinion said employer-integrated EWA that meets its conditions isn’t credit under the Truth in Lending Act. The profiles follow in alphabetical order.
Branch
Branch offers EWA through employers with a free Branch Wallet and free ACH transfers, and its EWA page says instant transfers carry a “small fee.” Employees can access up to 50% of their earned wages, and the business pays nothing. Branch serves employers in all 50 states. Branch publishes fee amounts in its help center, but we couldn’t load those pages on October 31, so we left the numbers off this page.
Chime Enterprise EWA
Chime Enterprise EWA sends instant pay to a Chime account for $0, according to Chime’s enterprise page. Chime offers no paid instant option, and employers don’t pre-fund advances. Chime lists Workday and UKG as payroll connections. This product is separate from Chime MyPay, which Chime sells directly to its members.
Clair
Clair runs on-demand pay inside small-business payroll software, including QuickBooks Payroll and Gusto. QuickBooks’ Clair help article lists instant transfers at up to $4.99 and standard transfers free in 1 to 3 business days. Pathward, N.A. originates the advances, and workers in Connecticut, Massachusetts, Minnesota, New Mexico, Nevada, and South Dakota can’t use Clair.
DailyPay
DailyPay charges $0 for transfers that arrive in 1 to 3 business days and $3.49 for instant transfers, according to its fees page, which adds that fees vary by employer. DailyPay’s Program Terms cap transfers at $1,000 a day. DailyPay holds NMLS 2587396 and lists more than 180 payroll and timekeeping integrations. See our DailyPay review for the full verdict.
Dayforce Flex Pay
Dayforce Flex Pay comes included with Dayforce Payroll, and Dayforce’s page says on-demand pay costs $0, though card fees may apply. Pay lands on the Dayforce Wallet Mastercard from Green Dot Bank. Dayforce no longer publishes a percentage cap on that page, so ask your employer what share of net pay you can take.
Immediate
Immediate charges a “flat nominal fee” for instant transfers and nothing for merchant cards, a paycard, or next-day ACH, according to its site. Employers pay nothing. Immediate holds NMLS 2592436 and plugs into ADP RUN, isolved, and other payroll systems.
Instant Financial
Instant Financial lists free ways to get earned pay on its site but publishes no fee amounts or cap. Instant Financial holds NMLS 1869318, and Sutton Bank issues its card.
OnePay @Work
OnePay @Work went by Even before its rebrand. The program is free when the employer configures the program that way and carries a “small fee” otherwise, according to OnePay’s @Work page. Employees can access a percentage of their net earnings. OnePay publishes no fee amount.
Payactiv
Payactiv charges $0 for ACH transfers in 1 to 3 days, Amazon loads, and transfers to the Payactiv Visa card for workers with $200 or more in direct deposits each pay period, according to its program pricing page. Without that deposit, a transfer to the Payactiv Visa prepaid card costs $2.49. Cash App costs $3.24 through an Early Adopter Program, and other debit cards, Walmart, Venmo, and PayPal cost $3.49.
The pricing page says employees can take “a portion” of earned wages. Payactiv’s get-started FAQ puts that at up to 50% and $500 a pay period in most cases. Employers pay nothing, and Payactiv lists 150+ payroll and timekeeping connections. It holds NMLS 2591928 and Wisconsin license 2591928EWA. Our Payactiv review has the verdict, and the Payactiv fees breakdown has the math.
Rain
Rain offers free ACH transfers in 1 to 3 days and charges a “small fee” for instant transfers without publishing the amount, according to its employee page. Rain says employees can access 50% of their earned wages in most cases. It holds NMLS 2623400 and Wisconsin license 2623400EWA, and lists 100+ payroll connectors.
Stream
Stream went by Wagestream before its rebrand. Stream charges employees nothing for standard transfers, per its help center. Instant transfers cost a small flat fee, and each employer partnership sets the amount. Stream holds NMLS 2547041.
Tapcheck
Tapcheck charges one flat fee per transfer, which it compares to an ATM fee, and waives the fee when you take your pay as a Prizeout gift card, according to its site. Tapcheck says employees can typically access $100 a day. Employers pay $0, and Tapcheck lists 300+ payroll providers and NMLS 2634283 on its licenses page.
ZayZoon
ZayZoon charges up to $5 for a near-instant transfer and $0 for ZayZoon Boost and the ZayZoon Visa card, according to its terms effective May 15, 2026. Connecticut workers pay $4, once per pay period. ZayZoon charges no subscription, and its advances are nonrecourse. Employers may cover the fee.
ZayZoon holds NMLS 2635812 and lists licenses in California, Connecticut, Kansas, Maryland, Missouri, Nevada, South Carolina, Utah, and Wisconsin, with Indiana listed as pending. ZayZoon’s help center says you can take up to 50% of earned pay, $200 a payout, and about $1,000 a pay period. ZayZoon’s homepage lists 300+ payroll partners, and its employer page says 130+.
Direct-to-consumer EWA apps
Direct-to-consumer EWA apps work without your employer: you link a bank account, the app estimates your pay from deposits, and it debits your account on payday. Our guide to earned wage access without employer help has the full cost math.
Regulators haven’t settled how to treat these apps. The CFPB’s 2025 opinion covered only employer programs, and the Colorado attorney general sued EarnIn in August 2026, calling its product high-cost lending. Our EWA vs cash advance guide covers where the CFPB draws that line.
Brigit
Brigit sells plans from $8.99 to $15.99 a month with advances of $25 to $500, or $25 to $250 in Maine, according to its homepage. Brigit’s terms put the Express fee on Plus at $0.99 to $5.99. Brigit also offers a free option if you ask by email. Brigit runs no credit check. For the verdict, see our Brigit review or the list of apps like Brigit.
Chime MyPay
Chime MyPay charges 3% for instant delivery, with a $2 minimum and $5 maximum, and nothing for a scheduled transfer within 24 hours, according to Chime’s MyPay page. MyPay is a line of credit from The Bancorp Bank or Stride Bank, with $20 to $1,000 available per pay period. You need $200 or more in qualifying direct deposits to Chime.
Cleo
Cleo charges $4.49 to $14.99 for express advances and nothing for standard delivery in 3 to 4 days, per Cleo’s help center. Cleo ties advances to a subscription, though it says you can apply without one by emailing its team. Repayment comes due in 3 to 14 days.
Current
Current offers Paycheck Advance of $25 to $1,000 to members whose payroll lands in a Current account, according to its advance page. Delivery is free if you wait up to 3 days, and the instant fee appears only in the app. Finco Advance LLC makes the advances, and Current says the product is not a loan or credit product.
Dave
Dave charges 5% on every ExtraCash advance, with a $5 minimum and $15 maximum, according to its fee schedule, plus 1.5% for delivery to an outside debit card. Dave’s quarterly report says Dave removed the $15 cap for some members in 2026. Dave’s homepage describes the fee as the greater of $5 or 5% and adds a membership of up to $5 a month. Advances run $25 to $500. Dave Operating LLC holds NMLS 2675197.
Dave has no free path, because the 5% fee applies to standard transfers too. For alternatives, see our Dave review and apps like Dave.
EarnIn
EarnIn lets you take up to $200 a day and $1,000 a pay period, according to its help center. Free standard transfers usually take 1 to 2 business days, and up to 3. Lightning Speed costs $3.99 to $8.99 in most states, depending on the amount. Tips are optional. Tips are fees with better marketing, so leave the tip at $0. Our EarnIn review and list of apps like EarnIn cover the rest.
FloatMe
FloatMe advances up to $200, starting at $10 to $50 for new members, according to its site. Instant Float costs $1 to $10, which works out to $7.50 on $100, and a $6.99 membership is optional. FloatMe says its average Float is $58 as of October 26, 2026. It doesn’t serve Connecticut, Nevada, or D.C.
Klover
Klover charges express fees from $3.99 on a $25 advance to $37.49 on $750, per its pricing page, and $4.99 a month for the optional Klover+. Standard delivery is free in 2 to 5 business days, and Klover runs no credit check. Klover’s FAQ says the average advance is about $170. To compare, see our Klover review and apps like Klover.
MoneyLion Instacash
MoneyLion Instacash advances up to $500, or $1,000 with direct deposit to a MoneyLion Spend account, according to the Instacash page. Standard delivery to Spend is free in 1 to 2 days, and Turbo delivery costs 7.5% of the advance, capped at $14.99. ML Plus LLC holds NMLS 2621850 and EWA licenses in Kansas, Missouri, Nevada, Utah, Wisconsin, and other states, per MoneyLion’s licensing page. Gen Digital owns MoneyLion.
Tilt
Tilt went by Empower before its rebrand. Tilt advances $10 to $500 and charges $8 a month after a 14-day trial, according to its cash advance page. Its instant fee appears in Tilt’s Terms, not on its site. Tilt doesn’t offer advances in Connecticut, Maine, or D.C.
Why employers offer earned wage access
Employers offer earned wage access as an employee benefit, and most EWA companies charge the employer nothing for the service. Payactiv says employers pay $0 on its earned wage access page. Tapcheck, Immediate, and Branch say the same, and Dayforce includes Flex Pay with its payroll.
In practice, employees fund the model. When an employee pays for instant transfers, the fee covers the EWA company’s costs, and employers covered less than 5% of total fees in the CFPB’s sample. EWA companies pitch the product to employers as a tool for hiring and retention, because employees who can access earned wages early have another way to cover expenses between paychecks.
If you run payroll and want to compare EWA services, ask each company four questions: what employees pay for instant transfers, whether a free path exists, what share of income employees can take, and whether you can cover the fees as a benefit. ZayZoon and DailyPay both let employers pick up the fee.
Which payroll platforms connect to which EWA company
Your payroll platform decides which EWA programs your employer can turn on, so start with the platform your employer already runs.
- ADP: ADP’s marketplace lists Immediate for RUN, DailyPay Preferred for Wisely, and Payactiv for ADP Workforce Now.
- Workday: DailyPay and Workday announced a partnership in August 2025. Payactiv lists Workday among its partners on its earned wage access page, and Chime Enterprise EWA also connects.
- UKG: Payactiv runs UKG Wallet, and Chime Enterprise EWA lists UKG as a connection.
- Dayforce: Dayforce Flex Pay comes built into Dayforce Payroll.
- QuickBooks and Gusto: both offer Clair to small businesses.
- isolved: the isolved marketplace lists Immediate.
DailyPay, Payactiv, Rain, Tapcheck, and ZayZoon each claim 100 or more payroll and timekeeping connections. If your employer runs a smaller payroll system, one of those five may still connect. Our EWA deduction guide explains how the payroll side works.
State licenses and how to look up an EWA company
At least ten states license or register EWA providers: California, Connecticut, Indiana, Kansas, Maryland, Missouri, Nevada, South Carolina, Utah, and Wisconsin, based on the license lists ZayZoon, Tapcheck, and MoneyLion publish. Our earned wage access laws by state tracker covers each law.
You can look up any company with an NMLS number on NMLS Consumer Access, a free public database that shows which states license a company and whether regulators took action against the company. Search by the NMLS number in the table above. A license means a state lets the company operate, and nothing more.
State rules change what you pay. Connecticut caps EWA charges at $4 an advance and $30 a month, which explains ZayZoon’s $4 Connecticut fee. Cleo, Tilt, and FloatMe don’t offer advances to Connecticut residents, and Clair skips six states.
Name changes and owners
Several EWA companies changed names or owners, so an old article may use a name you can’t find in the app store today.
- Empower now goes by Tilt.
- Wagestream now goes by Stream in the U.S.
- Even now operates as OnePay @Work.
- MoneyLion belongs to Gen Digital, which closed the acquisition on April 17, 2025.
- Dayforce Wallet on-demand pay now runs under the Dayforce Flex Pay name.
How EWA companies charge
EWA companies earn most of their revenue from instant transfer fees, with subscriptions, tips, card interchange, and employer fees making up the rest. In CFPB data on employer-partnered providers, expedited transfers made up 96.6% of worker-paid fees, and the average fee was $3.18 on a $106 advance. Our guide to how earned wage access companies make money breaks down each model company by company.
Each model shows what a company wants from your wallet. Employer programs earn when you pay for speed. Subscription apps earn every month you stay. Tip-based apps earn when you feel generous. You control the first two by waiting for the free transfer and canceling plans you don’t use.
How to check an EWA company
Check five things before you hand any EWA company your bank login or payroll access:
- The fee page. Find the instant fee in dollars. If the company says “small fee” and stops, ask for the number.
- The free path. Confirm a $0 option and how many days it takes.
- The cap. Know how much of your pay you can take, so payday doesn’t arrive half empty.
- The license. Search the NMLS number in NMLS Consumer Access.
- The repayment. Learn whether the company takes a payroll deduction or debits your bank, and what happens if the debit fails.
If you’re weighing an app against a payday loan, read our EWA vs payday loan comparison and is earned wage access a loan.
Earned wage access companies FAQ
Conclusion: pick by who you work for, then by the free path
The earned wage access companies in this directory split on one question: does your employer offer a program? If it does, you’ll get a free path and instant fees of $5 or less at almost every company listed. If it doesn’t, EarnIn, Klover, MoneyLion, and Chime MyPay let you pay $0 when you can wait a few days. Use the table to compare fees, check the NMLS number, and read our provider rankings when you want a verdict.
Free guide
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
- Track your money with the tools that still work in 2026.
- The order to invest in, with the 2026 401(k) and IRA limits.
- Three ways to earn your first $100 on the side this month.
Bonus: The 7-day Personal Profitability Bootcamp, one short lesson in your inbox each day