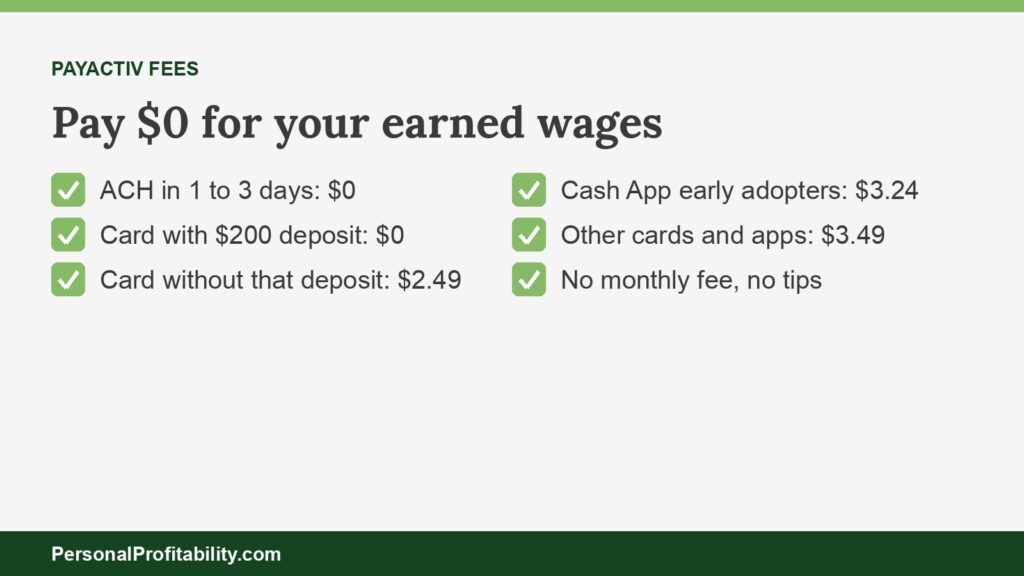
Payactiv fees run $0 for a bank transfer in one to three business days or an instant transfer to its Visa card with $200 of direct deposit, and $2.49 to $3.49 for other instant transfers. Payactiv lists no monthly fee and asks for no tips. Your employer has to offer Payactiv before you can sign up and access your earned wages. This page covers every fee and the math behind each one. For the verdict, read our Payactiv review.
Eric Rosenberg, who founded Personal Profitability, wrote for Payactiv as a freelancer and later worked there as a marketing manager, until June 2026. Nobody at Payactiv reviewed this page. We held Payactiv to its own published fees and terms, the same standard we used for every other company here.
Personal Profitability may earn a commission from partner links on this page, at no cost to you. Partners don’t decide what we recommend or where it ranks. Fees and terms are each company’s as of 2026-10-31. Confirm them on the company’s site before you apply.
Last checked: October 31, 2026, against each company’s own fee and terms pages.
Payactiv fees at a glance
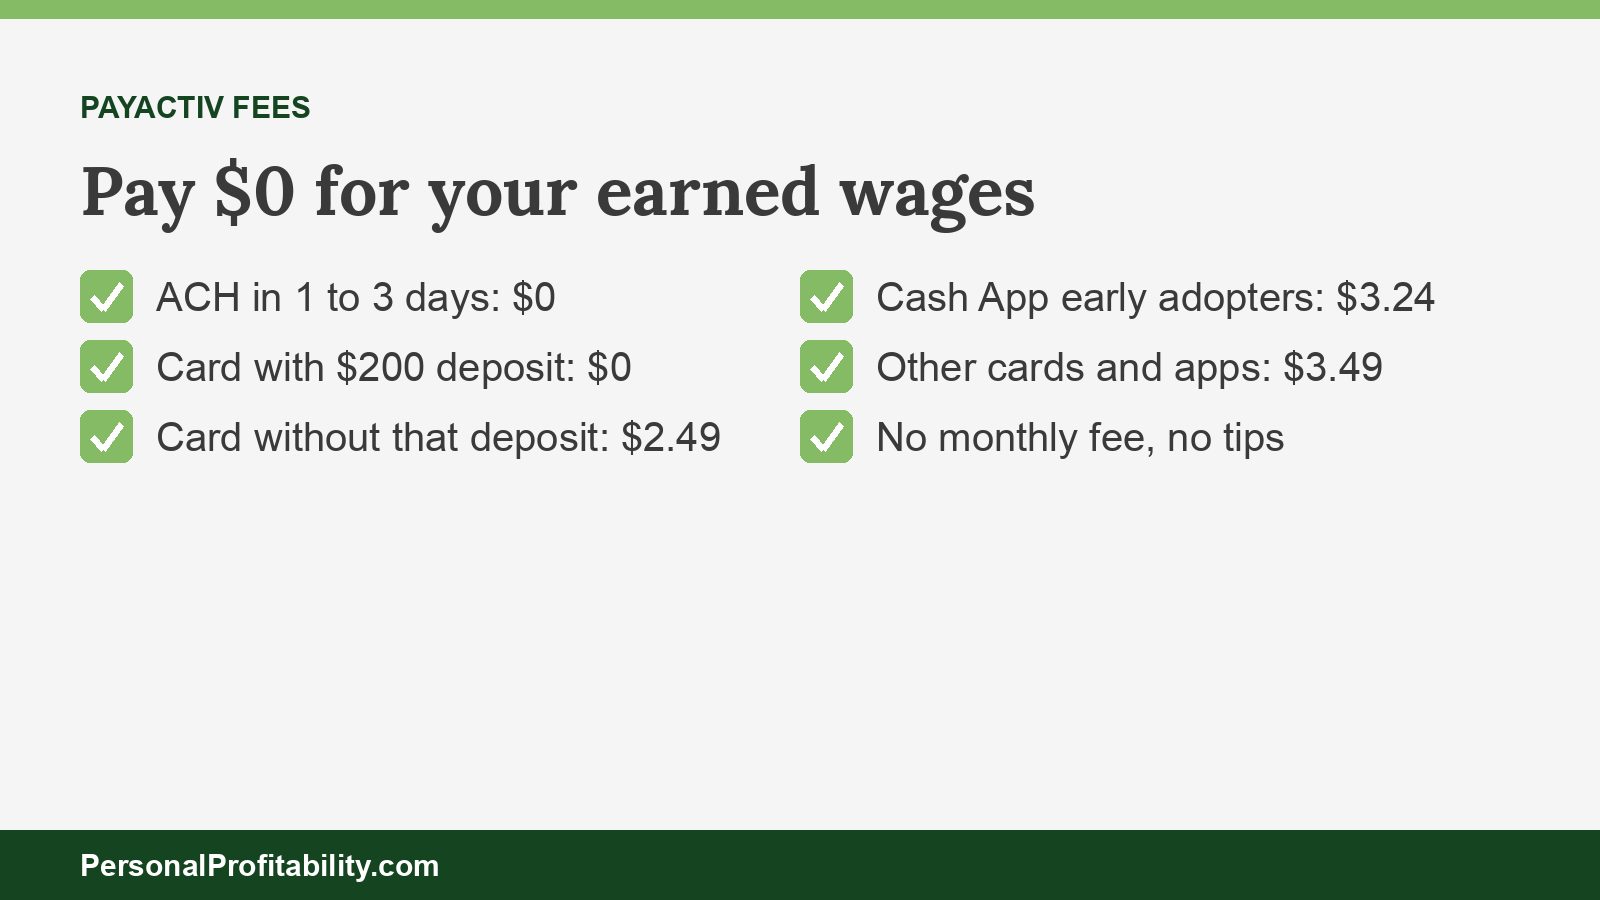
You pay nothing for slow transfers or for an instant transfer to the free Payactiv Visa Card with qualifying direct deposit. Every other instant transfer costs a flat $2.49, $3.24, or $3.49. Payactiv publishes these Payactiv fees on its program pricing page. It says the table “applies to our Payactiv program and our affiliated programs: UKG Wallet and OnShift Wallet.”
| How you take your earned wages | Speed | Payactiv’s fee |
|---|---|---|
| ACH transfer to your bank account | 1–3 business days | $0 |
| Amazon load | Instant | $0 |
| Payactiv Visa Card, with qualifying direct deposit | Instant | $0 |
| Payactiv Visa Card, without qualifying direct deposit | Instant | $2.49 |
| Cash App (early adopter program only) | Instant | $3.24 |
| Non-Payactiv debit card or payroll card | Instant | $3.49 |
| Walmart Cash Pickup | Instant | $3.49 |
| Venmo | Instant | $3.49 |
| PayPal | Instant | $3.49 |
| Uber rides, bill pay, saving tools, financial counseling, discount marketplace | Not applicable | $0 |
| Monthly or subscription fee | Not applicable | None listed |
| Tips | Not applicable | “Never any tips” |
Fees and terms verified 2026-10-31 on Payactiv’s pricing page. Payactiv also says “disbursement options may vary depending on location.” Check the fee in the app before you confirm a transfer.
Each fee applies per transfer. Split $100 into two $50 transfers to a debit card, and you pay $3.49 twice, or $6.98. One larger transfer costs less than two small ones.
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
Does Payactiv charge a fee?
Payactiv charges a fee only when you want wages you already earned sent instantly somewhere other than its card with qualifying direct deposit. Its FAQ says, “There is no cost to get started and no enrollment or activation fees.” Payactiv adds that “a transaction fee may apply” to instant transfers. It also says “real-time EWA transfers are free with a qualifying direct deposit of $200 or more per pay period to the Payactiv Card.”
On its pricing page, Payactiv lists these products, features, and services at $0:
- ACH transfers to your bank account, in one to three business days.
- Instant loads to Amazon.
- Instant transfers to the Payactiv Visa Card with qualifying direct deposit.
- Paying for an Uber ride with earned wages.
- Bill pay, which Payactiv says reaches more than 80,000 billers. Payments typically take two to seven business days.
- Saving tools, financial counseling, and the discount marketplace.
The $200 direct deposit rule that decides your instant fee
Your instant fee to the Payactiv Card depends on one test each pay period. Payactiv’s footnote reads: “To qualify, you must have one (1) successful direct deposit of $200 or more to the Payactiv Visa Card per pay period.” If you miss the deposit, Payactiv charges “a load fee of $2.49.”
To meet the requirement, ask your payroll team to send at least $200 of each paycheck to the card. Payactiv puts the card’s account and routing numbers on the Card tab in its app. The rest of your pay can keep going to your bank. If you miss the $200 deposit in a pay period, each instant transfer to the card costs $2.49 until the next qualifying deposit lands.
Payactiv Visa Card fees
The free Payactiv Visa Prepaid Card has no monthly, activation, purchase, or MoneyPass ATM fee. Payactiv does charge $2.95 to move money out through digital wallets, linked debit cards, or third-party banking apps. Payactiv posts the fee schedule on its card411 page, last updated April 23, 2025. Central Bank of Kansas City, Member FDIC, issues the card.
| Payactiv Visa Prepaid Card fee | Amount |
|---|---|
| Card purchase, activation, and monthly fee | $0 |
| Purchases in the US | $0 |
| MoneyPass ATM withdrawal | $0 |
| Out-of-network ATM withdrawal | $2.95, plus any ATM operator fee |
| ATM balance inquiry | $0.50 |
| Customer service, including balance checks by phone | $0 |
| Transfer out through Google, Apple, or Samsung digital wallets | $2.95 |
| Payment through a linked third-party debit card or e-wallet | $2.95 |
| Withdrawal through a third-party banking app | $2.95 |
| International transaction | 3% |
| International ATM withdrawal | $2.95 |
| Retail cash load at Green Dot (third party) | Up to $5.95 |
| Inactivity fee | $0 |
Fees and terms verified 2026-10-31. In its card411 FAQ, Payactiv says transfers from the card to a linked bank account are free. Those transfers typically take one to three business days. For transfers to a debit card, “fees may apply.” The card holds up to $15,000 and has no overdraft feature.
Watch the $2.95 rows. Take a free instant transfer to the card, push that money to another app, and you pay $2.95 anyway. Spend from the card, pay bills with the card balance, or pull cash at a MoneyPass ATM, and you keep the free path free.
What Payactiv costs: worked examples and APR
Each Payactiv transfer costs $0 to $3.49, an APR equivalent of 0% to about 182% on $100 repaid in a week. With no interest charge, Payactiv shows no APR on its disclosures. We annualize each flat fee the way regulators compare short-term credit. Divide the fee by the amount, multiply by 365, and divide by the days until payday.
Example 1: a $100 car repair, payday in seven days
- ACH to your bank: $0, and the money lands in one to three business days.
- Instant to the Payactiv Card with $200 of direct deposit this pay period: $0.
- Instant to the Payactiv Card without that deposit: $2.49, about 130% APR.
- Instant to your bank’s debit card: $3.49, about 182% APR.
- Free instant to the Payactiv Card, then $2.95 to move it through a digital wallet: $2.95, about 154% APR.
Example 2: a $500 rent shortfall, payday in 14 days
Payactiv’s get-started FAQ says that “in most cases” you can access up to 50% of earned wages, with a maximum of $500 per pay period. Its pricing page says only “a portion.” So $500 sits at the top of the typical limit. One $3.49 instant transfer on $500 for 14 days works out to about 18% APR. Size cuts the rate, since the same flat fee costs less per dollar on a bigger transfer. Five separate $100 transfers would cost $17.45 instead.
Payactiv fees as an APR
| Payactiv fee | $50 for 7 days | $100 for 7 days | $106 for 10 days | $100 for 14 days |
|---|---|---|---|---|
| $0 (ACH, Amazon, or card with $200+ deposit) | 0% | 0% | 0% | 0% |
| $2.49 (card, no qualifying deposit) | 260% | 130% | 86% | 65% |
| $3.24 (Cash App, early adopter program) | 338% | 169% | 112% | 84% |
| $3.49 (debit card, Venmo, PayPal, Walmart) | 364% | 182% | 120% | 91% |
The $106 column comes from the CFPB’s July 2024 Data Spotlight. The CFPB studied 2022 data and found an average employer-partnered advance of $106, an average fee of $3.18, and about 27 transfers per worker a year. Its own illustration put the APR on that average advance, over about 10 days, at 109.5%.
What Payactiv costs in a year
| Your habit | Fee per transfer | Yearly cost |
|---|---|---|
| 27 transfers by ACH or to the card with $200+ deposit | $0 | $0 |
| 27 transfers to the card without the deposit | $2.49 | $67.23 |
| 27 transfers to Cash App | $3.24 | $87.48 |
| 27 transfers to a debit card, Venmo, or PayPal | $3.49 | $94.23 |
| One transfer every biweekly payday to a debit card | $3.49 | $90.74 |
Ninety-four dollars a year for speed buys nothing you keep. Save that $94.23 instead, and you have the start of a starter emergency fund that costs $0 to tap.
How to pay $0 with Payactiv
You pay $0 with Payactiv when you choose ACH, pay bills straight from earned wages, or send $200 of each paycheck to the Payactiv Card. Follow these steps:
- Plan a day or two ahead and pick the ACH bank transfer to receive your cash free. Payactiv lists it at $0, with arrival in one to three business days.
- Pay the bill through Payactiv’s free bill pay and skip the transfer. Allow two to seven business days for the payment to reach the biller.
- Get the Payactiv Visa Card from the app. Payactiv says anyone in the US who is 18 or older is eligible to apply, with no bank account and no credit check.
- Ask payroll to send at least $200 of every paycheck to the card. One deposit each pay period makes every instant transfer to the card free.
- Spend from the card, tap with Apple Pay or Google Pay, or use a MoneyPass ATM, all at $0. Skip the digital wallet transfer, linked debit card, and third-party banking app options, which each cost $2.95.
- Access the full amount you need in one transfer, since Payactiv charges per transfer.
Our guide to how Payactiv works covers the timing of each option. It also explains when your balance updates.
Do Payactiv fees vary by employer or program?
Payactiv fees can vary by program and location. Payactiv says so in its pricing FAQ: “Fees and available transfer options may vary by program.” The Payactiv-powered programs we checked publish the same main fees, with a few differences.
UKG Wallet and OnShift Wallet
UKG Wallet and OnShift Wallet use the same Payactiv pricing. On its UKG Wallet page, Payactiv lists $0 for bank transfers and $0 for the UKG Visa Card with $200 of direct deposit. Without that deposit, the card costs $2.49. Venmo, PayPal, other debit or payroll cards, and Walmart cash pickup cost $3.49.
On the same UKG page, Payactiv still shows an older block, with “$2.25” for “day-of transfers to debit, bank or payroll cards.” The newer UKG table matches the main pricing page. Trust the fee you see in the app before you confirm.
Paycor Wallet and Paychex Pay on Demand
On its Paycor page, Payactiv lists bank, debit, prepaid, and payroll card transfers, plus Uber, Amazon, and Walmart pickup. Payactiv adds “fees may apply” without a table. Payactiv’s Paychex Pay on Demand page publishes no fee amounts either. Check the fee screen before you send money.
Older Payactiv fees you may still see online
Some reviews still quote a daily or monthly Payactiv program fee. Payactiv used to charge one. In a 2021 memorandum of understanding, California’s financial regulator described a $1 fee that covered Payactiv’s services for the whole day. Workers who sent their pay to a Payactiv card paid nothing. On its about page, Payactiv says that in 2022 it “removes standard EWA fees to expand access.” Its pricing page lists no program fee today. Treat any quote of $1 a day or $5 a month as out of date.
How Payactiv fees compare
Payactiv’s $3.49 instant fee matches DailyPay’s published flat fee and costs less than EarnIn’s Lightning Speed on most amounts. All three offer a $0 slow path.
| Provider | Free path | Instant fee on $100 | Needs employer? | Repayment |
|---|---|---|---|---|
| DailyPay | 1–3 business days, $0 | $3.49 on its fees page, set by your employer’s contract | Yes | Your paycheck |
| EarnIn Cash Out | Standard speed, $0 | $5.99 Lightning Speed in most states | No | Your bank account |
| Payactiv | ACH in 1–3 business days, or its card with $200+ deposit, $0 | $2.49 to its card, $3.49 to other cards | Yes | Your paycheck |
Fees and terms verified 2026-10-31 on DailyPay’s fees page and EarnIn’s fee table. EarnIn needs no employer, but EarnIn collects repayment from your bank account on payday. Payactiv deducts from your paycheck instead. Our Payactiv vs EarnIn comparison runs that trade-off, and Payactiv vs DailyPay covers the two employer programs. For every major provider in one table, see our earned wage access fees guide.
Are Payactiv fees loan charges?
No, Payactiv treats its fees as charges for faster delivery, not interest. Payactiv says its service “is not a loan or an advance against future earnings.” The CFPB’s December 2025 advisory opinion agrees for “Covered EWA.” That term covers a product that a payroll deduction repays, with no recourse against the worker. The CFPB also says expedited delivery fees and tips aren’t finance charges in the normal course.
Cash advance apps work differently. Most cash advance apps make advances against your next bank deposit and collect repayment from your bank account. If the money comes up short, your bank can charge an overdraft fee. Several apps add a monthly membership on top of express fees. Payactiv lists no membership, and it says its card involves no credit check and doesn’t affect your credit. Our guide to earned wage access vs cash advance apps explains where the line falls, and is earned wage access a loan covers the legal side.
Is Payactiv legit and safe with your money?
Payactiv is a licensed provider, and the card money you hold sits at an FDIC-insured bank. Payactiv lists NMLS ID 2591928 and Wisconsin earned wage access license number 2591928EWA on its pricing page. Payactiv’s card fee schedule says Central Bank of Kansas City holds your funds, and the FDIC insures them up to $250,000 if you register the card and meet the deposit insurance requirements. The card has no overdraft or credit feature, so you can’t spend past your balance. The CFPB issued Payactiv an approval order in December 2020 and ended it in June 2022 at Payactiv’s request. For the full record and whether Payactiv is worth using, see our Payactiv review.
Payactiv fees: pros and cons
| Where Payactiv’s fees help you | Where Payactiv’s fees cost you |
|---|---|
| Two $0 paths: ACH and its card with $200+ deposit | $2.49 per card transfer in any pay period without the deposit |
| No monthly fee and no tips | $3.49 per instant transfer to other cards, Venmo, or PayPal |
| Flat fees that shrink as a rate on larger transfers | $2.95 to move card money out through wallets or linked cards |
| Free bill pay, Uber, and Amazon spending | Fees that “may vary by program” and location |
| No cost to your employer | An older $2.25 fee block still posted on its UKG page |
What employers pay, and where the money comes from
Employers pay nothing to offer the benefit, according to Payactiv’s earned wage access page: “Employers can offer Payactiv Earned Wage Access to employees at no cost.” Payactiv publishes no other employer price. With no employer fee and no subscription, the instant fees and card fees that users choose to pay are the charges Payactiv publishes. That makes the free paths matter more. Our explainer on how earned wage access companies make money compares Payactiv’s model with subscription and tip-based apps.
On payday, you receive your paycheck minus whatever you accessed, plus any fee. Payactiv’s employee page says the amount you access “is automatically deducted from your next paycheck and appears as a line item on your pay stub.” To read that line, use our guide to the earned wage access deduction.
Payactiv fees FAQ
The cheapest way to use Payactiv
The cheapest Payactiv habit costs $0. Send $200 of each paycheck to the Payactiv Card, spend from the card, and use ACH when you can wait. Every instant fee Payactiv charges is $3.49 or less, and you can skip every one. Before you pay a fee, check whether the bill can wait two days.
Payactiv fixes a timing gap between your shift and your payday. A fee you pay every pay period points to a budget gap, and our guide to budgeting with irregular income helps you close that gap. For our overall take, read the Payactiv review. To skip the employer, compare apps like Payactiv. For the basics, start with our earned wage access guide.
Free guide
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
- Track your money with the tools that still work in 2026.
- The order to invest in, with the 2026 401(k) and IRA limits.
- Three ways to earn your first $100 on the side this month.
Bonus: The 7-day Personal Profitability Bootcamp, one short lesson in your inbox each day