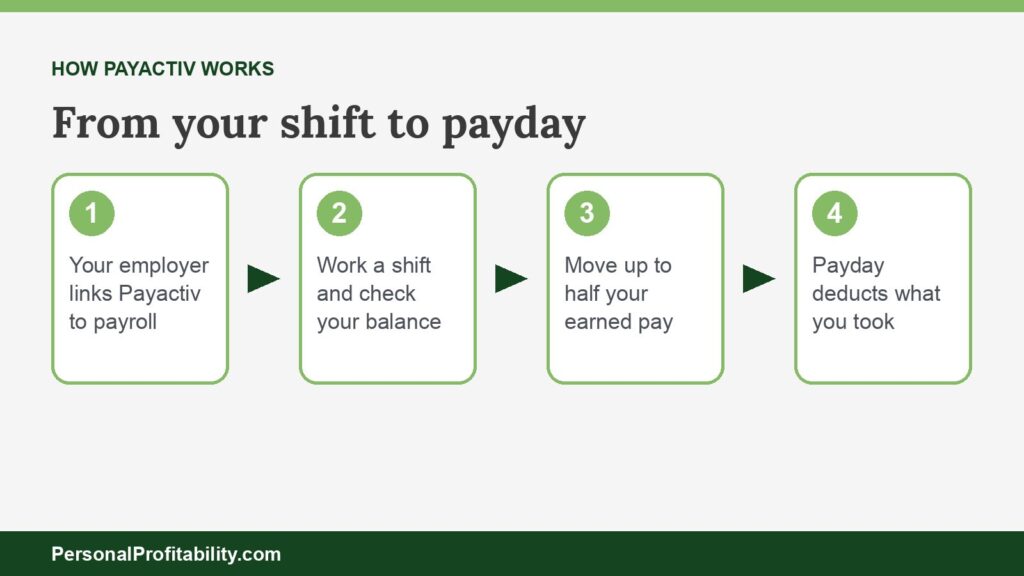
The answer to how does Payactiv work fits in one line: your employer links Payactiv to payroll, you access wages you already earned, and Payactiv deducts that amount on payday. Payactiv’s get-started FAQ puts the limit at 50% of earned wages and $500 a pay period in most cases. This guide covers the mechanics. For costs, see our Payactiv fees breakdown.
Eric Rosenberg, who founded Personal Profitability, wrote for Payactiv as a freelancer and later worked there as a marketing manager, until June 2026. Nobody at Payactiv reviewed this page. We held Payactiv to its own published fees and terms, the same standard we used for every other company here.
Personal Profitability may earn a commission from partner links on this page, at no cost to you. Partners don’t decide what we recommend or where it ranks. Fees and terms are each company’s as of 2026-10-31. Confirm them on the company’s site before you apply.
Last checked: October 31, 2026, against each company’s own fee and terms pages.
How does Payactiv work, step by step?
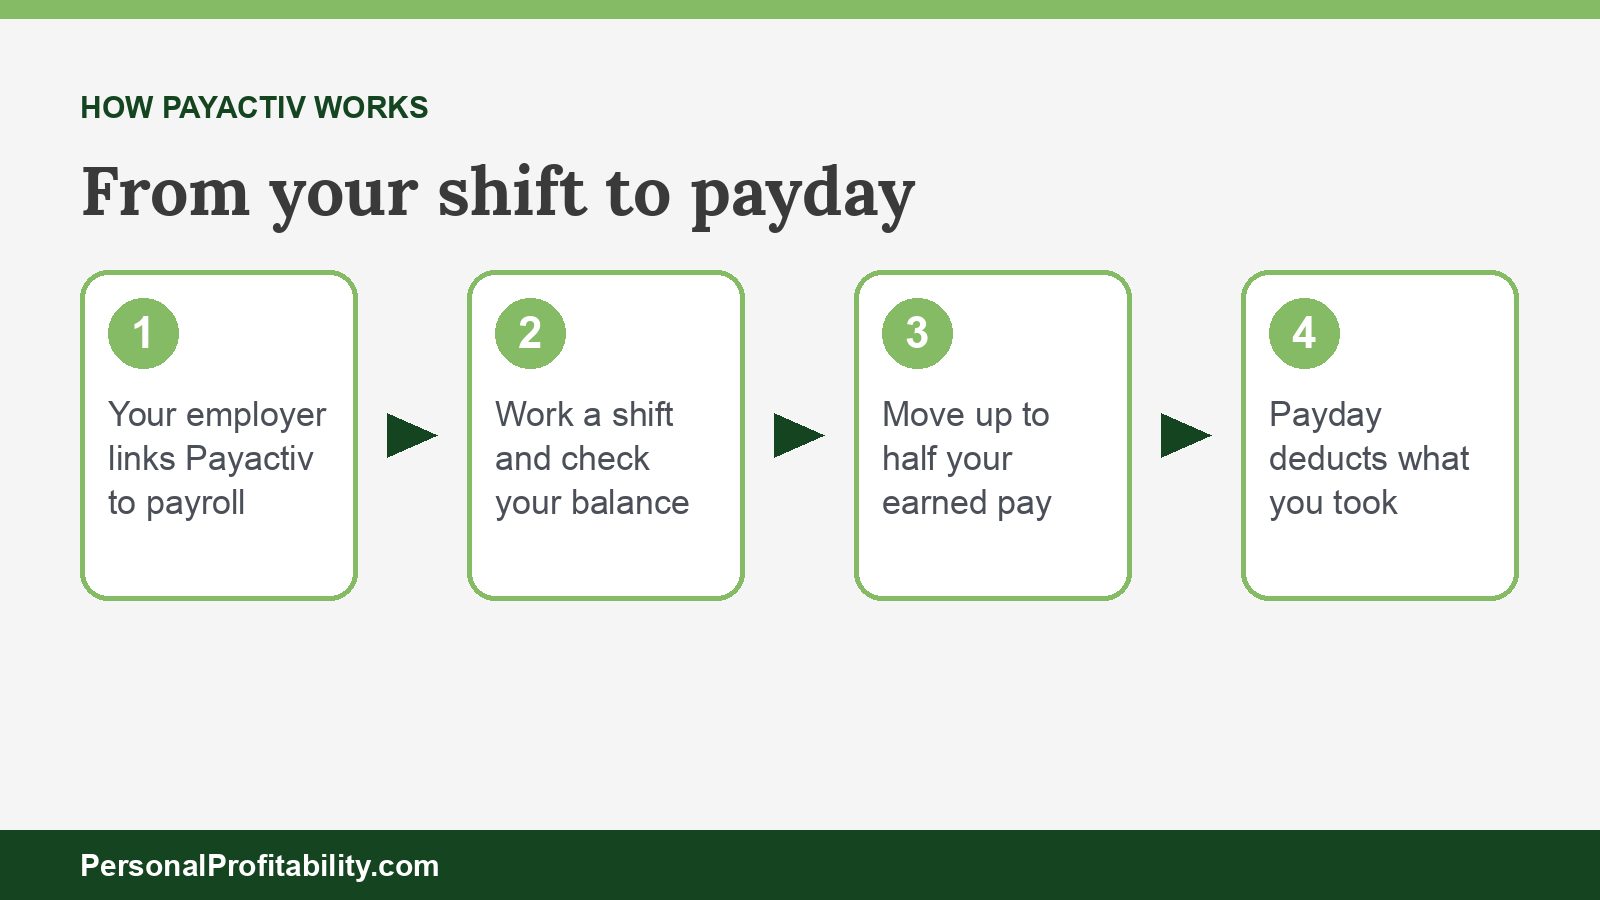
Payactiv works in six steps, from your employer signing up to the payday deduction. Payactiv describes each one on its employee page and its get-started page.
- Your employer offers Payactiv. Payactiv says “Earned Wage Access requires employer participation.” You can’t join on your own.
- You create an account. Download the Payactiv app from the App Store or Google Play. Payactiv asks for your name, mobile phone number, personal email, employer name, and employee ID, which you can find on your pay stub.
- You work your shifts. In Payactiv’s words, “Work your scheduled shifts and we’ll automatically get that data from your employer.”
- You check your balance. Open the app to see the earned wages available to you right now.
- You move what you need. Send money to your bank, the Payactiv Card, another debit card, Venmo, PayPal, or Walmart Cash Pickup. You can also pay bills, Uber rides, or Amazon orders with earned wages.
- Payday settles the balance. Payactiv’s employee page says the money you access “is automatically deducted from your next paycheck and shows as a line item on your pay stub.”
Payactiv fronts the money between paychecks, so you don’t borrow from your employer, and your employer keeps running payroll as usual. On its Money Network page, Payactiv says, “We front the money so employees are covered without disrupting any existing systems.” On its earned wage access page, Payactiv says employees “are still paid on their normal payday.” Payactiv reconciles what you accessed through payroll. To read that pay stub line, use our guide to the earned wage access deduction.
What else comes with Payactiv?
Payactiv bundles several money tools with early pay, and Payactiv lists most of these services at $0 on its pricing page. Your employer’s program decides which features you see. Payactiv lists these on its employee page:
- Bill pay: pay bills from the app with your card balance or earned wages to help avoid late fees.
- Saving tools: create custom goals and set money aside automatically. Payactiv says goal-based saving requires the Payactiv Visa Card.
- Discount marketplace: deals on everyday purchases, such as gas, prescriptions, and movie tickets.
- Financial counseling: one-on-one sessions with independent financial professionals on budgeting, debt, and planning.
- Financial education: articles and resources inside the app.
- Tips and mileage: same-day access to eligible tips and mileage reimbursements on a Payactiv Visa Card, if your employer offers the feature.
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
How much can you get from Payactiv?
You can usually get up to 50% of your earned wages from Payactiv, up to $500 per pay period. Your employer’s settings decide the exact limit. Payactiv’s get-started FAQ reads: “In most cases, employees can access up to 50% of earned wages, with a maximum of $500 per pay period.” With direct deposit to the Payactiv Card, Payactiv adds, “you may be able to access up to $1,000 per request.”
Payactiv calculates the amount from your employer’s records. Payactiv uses “validated payroll and workforce data” plus your employer’s program settings. Payactiv also describes “eligibility and program controls to preserve wages for payday.” Your employer uses those controls to keep part of your check for payday.
| Program | What Payactiv says you can access |
|---|---|
| Payactiv (most employers) | Up to 50% of earned wages, $500 maximum per pay period, “in most cases” |
| Payactiv with card direct deposit | Up to $1,000 per request, “may be able to” |
| Paychex Pay on Demand | Up to 50% of net earnings after every day you work |
| Paycor Wallet | “A portion of your net earnings” after every day you work |
| UKG Wallet | “A portion of your earned but unpaid wages” every day you work |
Limits verified 2026-10-31 on Payactiv’s get-started, Paychex, Paycor, and UKG Wallet pages. Payactiv’s site-wide footer says only that “employees can only access a portion of the wages they have earned to date.” Check the app for your exact limit.
How often can you use Payactiv?
You can use Payactiv as often as you have an available balance, and Payactiv publishes no limit on the number of transfers. Your balance grows as you work. On its Paychex page, Payactiv says it recalculates your balance from the hours you worked “after every shift.” On its UKG Wallet page, Payactiv says that “every day you work,” you can access a portion of your earned but unpaid wages.
Two things limit how often you’ll want a transfer. First, each instant transfer carries its own fee unless you use a free path, so five small transfers cost five fees. Second, everything you take comes out of the same paycheck. Pull $500 from a $1,000 check, and you receive about $500 on payday.
How long does Payactiv take, and does it work on weekends?
Payactiv’s instant options arrive right away, and its free ACH transfer takes one to three business days. Payactiv lists these speeds on its pricing page:
| Where the money goes | Speed Payactiv lists | Fee |
|---|---|---|
| Your bank account by ACH | 1–3 business days | $0 |
| Payactiv Visa Card | Instant | $0 with $200+ direct deposit per pay period, $2.49 without |
| Amazon load | Instant | $0 |
| Cash App (early adopter program only) | Instant | $3.24 |
| Another debit or payroll card | Instant | $3.49 |
| Venmo or PayPal | Instant | $3.49 |
| Walmart Cash Pickup | Instant | $3.49 |
| Bill pay | Typically 2–7 business days | $0 |
Fees and speeds verified 2026-10-31. Payactiv doesn’t publish a weekend policy. An ACH transfer counts business days, so a Friday night request won’t land over the weekend. Payactiv lists its card, debit card, Venmo, PayPal, and Walmart options as “Instant,” with no business-day limit stated. Whether your balance grows on a Saturday depends on when your employer sends hours to Payactiv. Payactiv offers support by phone and live chat 24 hours a day at 1 (877) 937-6966.
Which banks and cards work with Payactiv?
Payactiv works with any bank account or debit card you link, plus its own Visa card, Venmo, PayPal, and Walmart Cash Pickup. On its UKG Wallet page, Payactiv says, “You can transfer your funds to any bank account or debit card.” You link a bank account or debit card from the Wallet tab in the app. Payactiv connects linked bank accounts through Plaid.
Does Payactiv work with Chime?
Payactiv doesn’t name Chime on its public pages. Still, a Chime checking account is a bank account, and a Chime debit card is a non-Payactiv debit card. By Payactiv’s published rules, an ACH transfer to a Chime account would cost $0 and take one to three business days. An instant transfer to a Chime debit card would cost $3.49. Link the account in the Payactiv app and check the options it offers before you count on either one.
The Payactiv Visa Card
The Payactiv Visa Card is a prepaid card you can get through the app, and it’s the only card Payactiv loads instantly for free. Payactiv says “anyone in the United States, who is 18 years or older may apply,” with no bank account and no credit check. Central Bank of Kansas City, Member FDIC, issues the card. Here’s what Payactiv says the card does:
- Receives instant earned wage transfers, free when you set up direct deposit of $200 or more to the Payactiv Card each pay period.
- Delivers your direct-deposit paycheck up to two days early. Payactiv’s Subway and UKG pages add government payments up to four days early.
- Pays anywhere merchants take Visa debit, including through Apple Wallet, Google Wallet, and Samsung Wallet.
- Gives you free withdrawals at 37,000 MoneyPass ATMs.
- Holds up to $15,000, with an account and routing number for direct deposit from any employer.
- Takes paper check deposits through the Ingo Money app, which charges its own fees.
The card has its own fee schedule, including $2.95 to move money out through digital wallets or linked cards. Our Payactiv fees page lists every charge.
What companies use Payactiv?
Payactiv names payroll partners such as UKG, Paychex, Paycor, ADP, Oracle, and Workday. Payactiv also names employers such as Subway, Urban Outfitters, and the YMCA of Metropolitan Dallas. The list below includes only the companies Payactiv names on its own public pages. Many Payactiv employers never appear on its site, so ask HR if your company isn’t here.
Payroll, HR, and wallet programs powered by Payactiv
| Partner | What you’ll see | Where Payactiv names it |
|---|---|---|
| UKG | UKG Wallet app, “powered by Payactiv” | UKG Wallet page and pricing page |
| OnShift | OnShift Wallet and OnShift Wallet Visa Prepaid Card | Pricing page and card411 |
| Paychex | Pay on Demand in Paychex Flex, run through the Payactiv app | Paychex page |
| Paycor | OnDemand Pay in the Paycor app, Wallet powered by Payactiv | Paycor page |
| ADP, Oracle, and Workday | Listed as “active partnerships” | Earned wage access page FAQ |
| Money Network | Partner program for selling Payactiv to employers | Money Network page |
On its Paychex page, Payactiv says, “If your employer offers Paychex payroll processing, then you are eligible for Pay on Demand.” Paycor users need no separate app. They open OnDemand Pay inside the Paycor app. One change is coming for UKG. ZayZoon announced on October 8, 2026, that UKG chose ZayZoon as the exclusive earned wage access provider for UKG Wallet in UKG Ready. ZayZoon expects the rollout in early 2027.
Employers Payactiv names publicly
- Subway: Payactiv runs a page for Subway employees that says “Subway partnered with us.”
- Urban Outfitters: a retail case study on Payactiv’s earned wage access page.
- Norman Regional Health System: a healthcare case study on the same page.
- YMCA of Metropolitan Dallas: a nonprofit case study video.
- Reser’s Fine Foods: a manufacturing case study.
- OVG: a welcome page for OVG employees.
- Amazon delivery service partners: a landing page aimed at the businesses that run Amazon delivery routes.
Payactiv also partners with Murphy USA on a 10-cent-per-gallon discount for Payactiv Visa cardholders. Payactiv gives different counts of its reach on different pages. On its payroll partner page, Payactiv claims 245,000+ employers, 7 million+ workers, and 190+ integration partners. On its partner page, it claims “more than 30,000 employers, 6 million employees and 180+ partners.” On its earned wage access page, Payactiv says it “connects to 150+ payroll and workforce systems.”
What happens on payday, and is Payactiv a loan?
On payday, your employer deducts what you accessed through Payactiv, plus any fee, and pays you the rest. Payactiv says in its FAQ that “there is no interest.” It also says its service “is not a loan or an advance against future earnings.” In its December 2025 advisory opinion, the CFPB says “Covered EWA” isn’t credit under federal Truth in Lending rules. To qualify, a provider limits access to accrued wages and collects through a payroll deduction. The provider also gives up any claim against you if that deduction falls short.
Payactiv doesn’t publish what happens if you leave your job, or if your final check comes up short of what you took. We couldn’t find Payactiv’s earned wage access user agreement on its public site. Ask HR or read the terms in the app before you rely on a transfer late in a pay period. For the legal background, see is earned wage access a loan.
Can you use Payactiv without an employer?
No. Payactiv’s earned wage access needs your employer to participate. You can apply for the Payactiv Card on your own. Without an employer program, you get the card and its tools, but no early pay. If your job doesn’t offer Payactiv, read our guide to earned wage access without an employer. You’ll find EarnIn there, plus the cash advance apps that collect repayment from your bank account instead of your paycheck. Compare the two models side by side in our Payactiv vs EarnIn guide.
How does Payactiv make money?
Payactiv makes its money from workers through the transfer and card fees it publishes, and from employer and partner deals it keeps private. Payactiv lists the worker fees on its pricing page and its prepaid card fee schedule:
- Instant transfer fees: $3.49 to a non-Payactiv debit or payroll card, Venmo, PayPal, or Walmart Cash Pickup, and $3.24 to Cash App in its early adopter program.
- Card load fee: $2.49 to load the Payactiv Visa Card if you don’t have qualifying direct deposit to the card.
- Card fees: $2.95 for an out-of-network ATM withdrawal or a transfer to a third-party debit card or digital wallet, $0.50 for an out-of-network balance inquiry, and 3% on international purchases.
- Partner revenue share: on its partner page, Payactiv says partners “earn on revenue as customers adopt Earned Wage Access, card, tips, and off-cycle payment capabilities.”
Payactiv doesn’t publish employer pricing. On its earned wage access page, Payactiv says “Employers can offer Payactiv Earned Wage Access to employees at no cost.” Payactiv lists no prices for employers. Payactiv also doesn’t say whether it earns a share of the interchange, the swipe fees merchants pay when you use the card. Every fee on the list above has a free way around, and our Payactiv fees guide walks through each route. To see how Payactiv’s model compares with the rest of the industry, read how earned wage access companies make money.
How does Payactiv work FAQ
Using Payactiv well
Payactiv works best as a bridge for one bill that lands before payday. Check your balance after your shift and take one transfer for the full amount. Pick a free path when the bill can wait a day or two. Plan for the smaller paycheck that follows.
If you reach for Payactiv every pay period, the problem is the budget, and a small emergency fund beats any transfer. For the costs in detail, read our Payactiv fees guide. For our verdict, read the Payactiv review. For the bigger picture, start with our earned wage access guide.
Free guide
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
- Track your money with the tools that still work in 2026.
- The order to invest in, with the 2026 401(k) and IRA limits.
- Three ways to earn your first $100 on the side this month.
Bonus: The 7-day Personal Profitability Bootcamp, one short lesson in your inbox each day