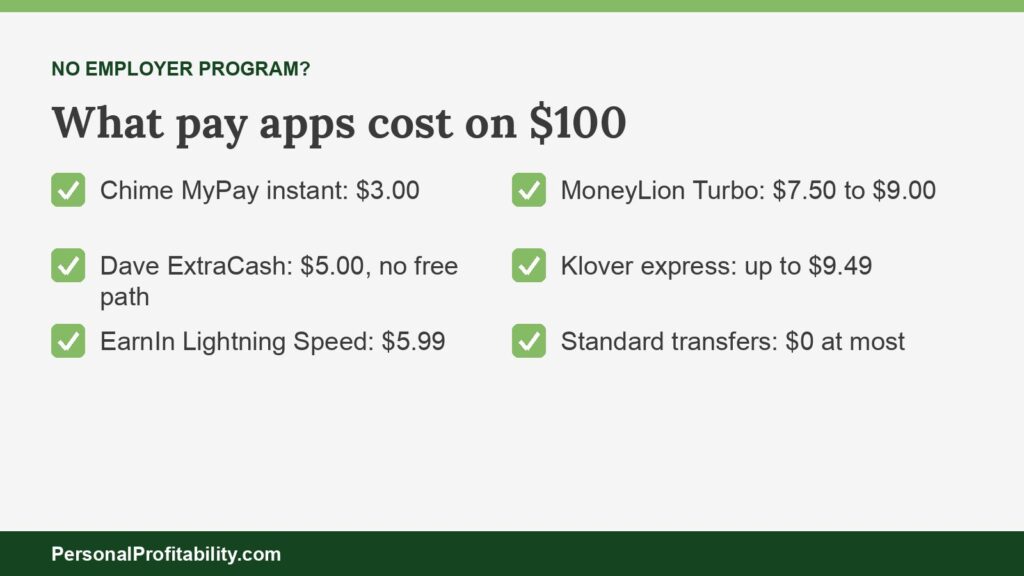
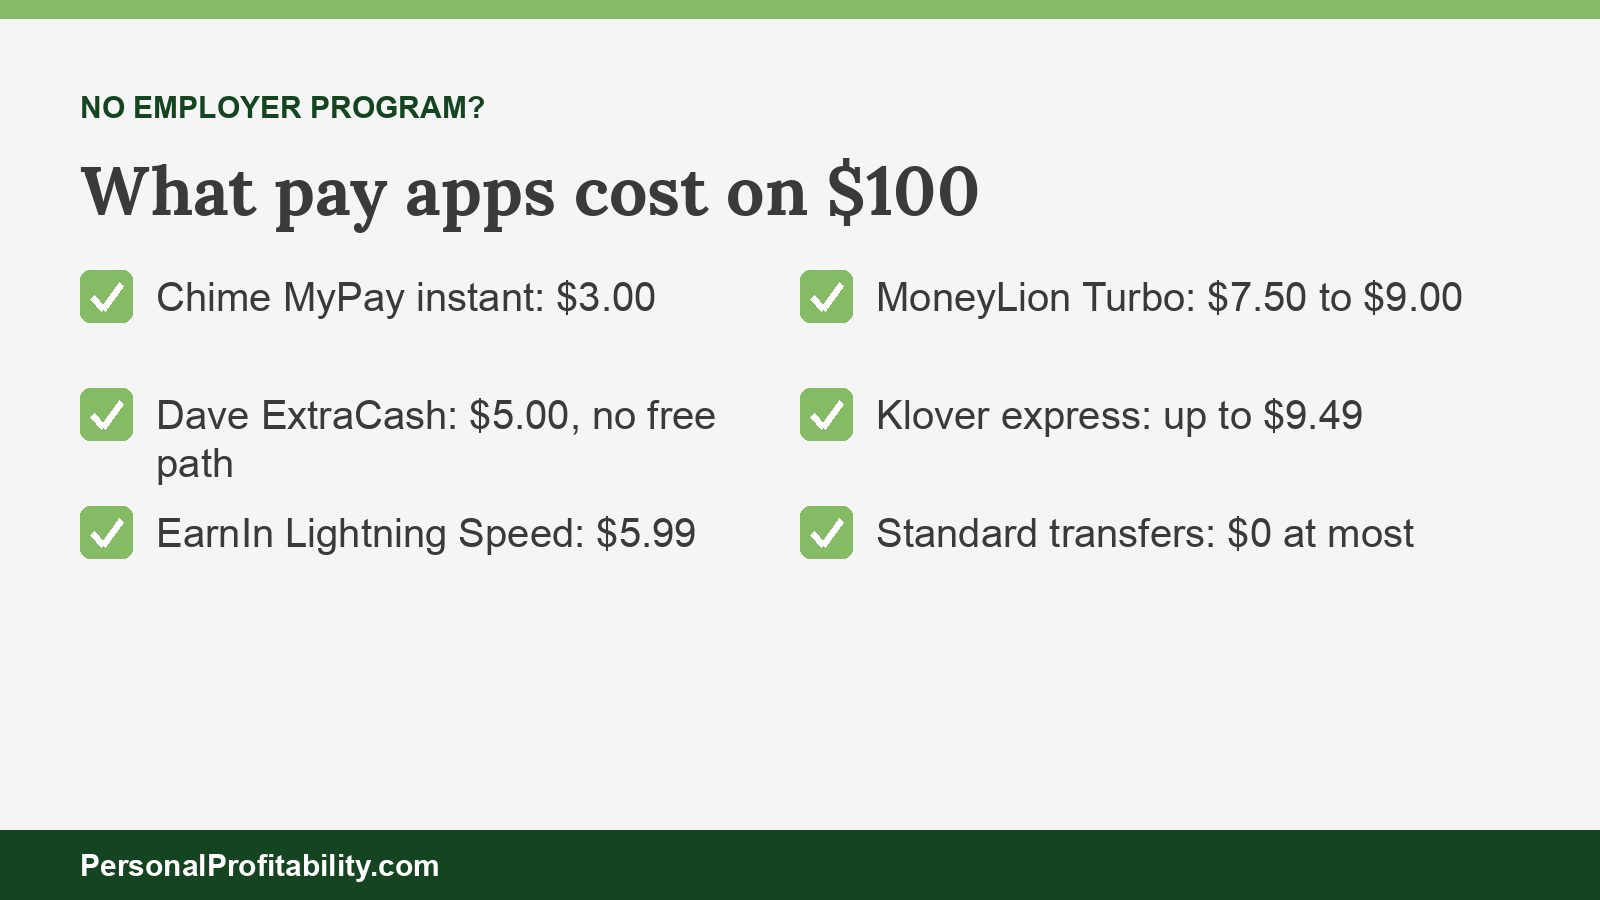
You can get earned wage access without employer involvement through apps like EarnIn, Klover, MoneyLion, and Chime MyPay, but a $100 instant advance costs $3.00 to $9.49 at those four. Start with our earned wage access guide if the product is new to you.
Eric Rosenberg, who founded Personal Profitability, wrote for Payactiv as a freelancer and later worked there as a marketing manager, until June 2026. Nobody at Payactiv reviewed this page. We held Payactiv to its own published fees and terms, the same standard we used for every other company here.
Personal Profitability may earn a commission from partner links on this page, at no cost to you. Partners don’t decide what we recommend or where it ranks. Fees and terms are each company’s as of 2026-10-31. Confirm them on the company’s site before you apply.
Last checked: October 31, 2026, against each company’s own fee and terms pages.
Most people search this because their job doesn’t offer a pay app as an employee benefit. Direct-to-consumer EWA apps fill the gap. They read your bank account instead of your employer’s payroll, and that one change drives the cost, the risk, and the legal fights. This guide covers how these apps work, what each one charges, and when you’re better off asking HR for a real employer program.
How earned wage access works without your employer
Earned wage access without employer involvement runs through apps that estimate your pay from bank deposits, send you part of your earned wages before payday, and debit your bank account on payday.
An employer program works differently. Your employer or its payroll company tells the provider how many hours you’ve worked, and the provider takes repayment out of your next paycheck before the money ever reaches your bank. A direct-to-consumer app has neither connection. So the app company has to guess what you’ve earned and collect from your bank account after payday. That’s why people also call these products pay advance apps without an employer, or cash advance apps, and why their EWA fees run higher.
Each company verifies income its own way:
- EarnIn asks for a consistent direct deposit schedule and a linked checking account (no prepaid or savings accounts). If you have a job, EarnIn asks for a work email or work location, and its help center lists GPS location and uploaded timesheets as ways to verify hours. EarnIn also accepts Social Security, SSDI, SSI, and VA payments, but not unemployment, according to its eligibility page.
- Klover wants a linked bank account, direct deposit income, and recent, consistent pay. New hires need three consistent direct deposits first, per Klover’s FAQ.
- Chime MyPay requires $200 or more in qualifying direct deposits into a Chime account, an activated physical Chime card, and an eligible state, per Chime’s MyPay page.
- MoneyLion Instacash looks for a checking account open at least two months, regular income deposits, and a positive balance.
- Brigit needs a smartphone and a connected checking account, and Brigit reviews your transactions to set a limit.
None of these five companies runs a credit check or charges interest on its advance. You give them something else instead: a live window into your bank account. Before you link an account, read our explainer on whether earned wage access is a loan, since the answer differs for these apps.
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
Earned wage access without employer apps compared
EarnIn, Klover, MoneyLion, and Chime MyPay each offer a $0 standard transfer, while Dave ExtraCash charges a fee on every advance and Brigit, Tilt, and Cleo lean on subscriptions.
| App | Advertised max | Free path | Instant fee on $100 | Subscription | The catch |
|---|---|---|---|---|---|
| EarnIn Cash Out | $200 a day, $1,000 a pay period | Standard transfer, usually 1–2 business days, up to 3 | $5.99 Lightning Speed (most states) | None | Tip prompts, and two state AG lawsuits |
| Klover | $750 | Standard transfer, 2–5 business days | Up to $9.49 | Klover+ $4.99 a month, optional | The priciest express fees here, and a data trade |
| MoneyLion Instacash | $500, up to $1,000 with qualifying direct deposit | Standard to a MoneyLion Spend account only | $7.50 Turbo to Spend, $9.00 to an outside account | Optional | $100 per disbursement, and no free delivery to an outside bank |
| Chime MyPay | $750 advertised, limits of $20–$1,000 | Scheduled advance within 24 hours | $3.00 (3%, $2 minimum, $5 maximum) | None | Chime calls MyPay a line of credit, and your pay must land at Chime |
| Dave ExtraCash | $25–$500, few qualify for $500 | None. Every advance carries a 5% fee | $5.00, free to Dave Checking, plus 1.5% to an outside debit card | Up to $5 a month | No $0 option, and an FTC and DOJ lawsuit |
| Brigit Instant Cash | $25–$500 | An advance by email request, without a plan | $0.99–$5.99 Express on Plus, per Brigit’s terms. Free on Premium | $8.99 or $15.99 a month | You pay the plan whether you borrow or not |
| Current Paycheck Advance | $25–$1,000 | Free if you wait up to 3 days | Shown in the app only | None | Payroll has to land in a Current account |
| FloatMe | $200, first Floats $10–$50 | ACH transfer | $7.50 | $6.99 a month, not required | Not in Connecticut, D.C., or Nevada |
| Tilt (formerly Empower) | $10–$500 | Not stated | In Tilt’s Terms, not on its site | $8 a month after a 14-day trial | Not in Connecticut, Maine, or D.C. |
| Cleo | Shown in the app | Standard in 3–4 days | $4.49–$14.99, same day | Plus, Pro, or Builder plans | No advances in Connecticut or Maine |
Fees and terms verified 2026-10-31. Sources: EarnIn Cash Out, Klover pricing, MoneyLion Instacash, Chime MyPay, Dave’s ExtraCash fee schedule, Brigit, Current, FloatMe’s terms, Tilt, and Cleo’s help center.
EarnIn charges $3.99 for Lightning Speed on $75 or less, $5.99 on $75.01 to $150, and $8.99 above $150 in most states, and its fees differ in Indiana, Florida, New York, Colorado, and Wisconsin. Dave’s fee schedule, last updated July 6, 2026, sets the ExtraCash fee at 5% of each overdraft amount, with a $5 minimum and a $15 maximum. Dave’s homepage calls it “the greater of $5 or 5%” and leaves out the cap, and Dave’s quarterly report says Dave removed the cap for some members in 2026. Klover lists its express fees as “up to” amounts and lets you offset them with points at 500 points per $1.
Apps with a $0 path and no required subscription
EarnIn is the closest thing to employer EWA without the employer, and it’s the app most people mean by direct to consumer earned wage access. It ties advances to hours it can verify, charges no subscription, and sends standard Cash Outs free. The catch is the tip screen and the instant fee. Read our EarnIn review for the state-by-state fee table, or go straight to EarnIn.
Klover advertises the highest limit in this group at $750, with an average advance around $170. Klover says it “earns revenue through express fees for expedited transfers and through Klover+ memberships,” and it uses points you earn from surveys, receipt scans, and referrals to raise limits. Our Klover review explains the data trade, and you can sign up at Klover.
Chime MyPay charges the lowest instant fee here, $2 to $5, with a free scheduled option inside 24 hours. You have to move your paycheck to Chime first. MoneyLion Instacash sends standard money free only to a MoneyLion Spend account and caps each disbursement at $100.
Apps that charge on every advance or every month
Dave ExtraCash has no free path. Dave’s 2025 annual report says the company “replaced” its optional fee model with “a mandatory 5% overdraft service fee” in February 2025, and members pay up to $5 a month on top. See our Dave review or Dave’s site.
Brigit charges $8.99 to $15.99 a month, and its $15.99 tier includes free express delivery and Credit Builder. Brigit also offers a free advance if you email the company and ask for one without a plan. Our Brigit review covers both tiers, and Brigit takes sign-ups in its app.
What a $100 advance costs at each app
A $100 instant advance repaid in seven days costs the equivalent of 156% APR at Chime MyPay and 495% at Klover, and the standard transfer at EarnIn, Klover, MoneyLion, or Chime costs $0.
We used one formula for every row: fee divided by the advance, times 365 divided by the days until repayment, times 100. Our earned wage access fees page walks through the math step by step.
| $100 advance, instant | Fee | APR, 7 days | APR, 14 days |
|---|---|---|---|
| Chime MyPay | $3.00 | 156.4% | 78.2% |
| Dave ExtraCash to Dave Checking | $5.00 | 260.7% | 130.4% |
| EarnIn Lightning Speed | $5.99 | 312.3% | 156.2% |
| FloatMe Instant Float | $7.50 | 391.1% | 195.5% |
| MoneyLion Turbo to Spend | $7.50 | 391.1% | 195.5% |
| MoneyLion Turbo to an outside account | $9.00 | 469.3% | 234.6% |
| Klover express | $9.49 | 494.8% | 247.4% |
| Employer EWA at $3.49 (Payactiv or DailyPay) | $3.49 | 182.0% | 91.0% |
| Any standard transfer with no fee | $0 | 0% | 0% |
Now run it for a year. The CFPB’s 2024 data spotlight found the average worker used EWA 27 times a year, so a habit of one instant advance per biweekly paycheck is realistic.
| 26 instant $100 advances a year | Advance fees | Subscription | Yearly cost |
|---|---|---|---|
| Chime MyPay | $78.00 | $0 | $78.00 |
| Payactiv or DailyPay at $3.49 | $90.74 | $0 | $90.74 |
| Brigit Premium (free express) | $0 | $191.88 | $191.88 |
| EarnIn Lightning Speed | $155.74 | $0 | $155.74 |
| Dave ExtraCash | $130.00 | Up to $60 | Up to $190.00 |
| MoneyLion Turbo to Spend | $195.00 | $0 | $195.00 |
| Klover express plus Klover+ | $246.74 | $59.88 | $306.62 |
| Standard transfers at EarnIn, Klover, or Chime | $0 | $0 | $0 |
Dave is the exception. Even if you wait for the slow transfer, 26 advances of $100 still cost $130 in ExtraCash fees. Every other app on this list waives transfer fees if you plan a few days ahead. Tips sit outside this math, and you should keep them at $0. Tips are fees with better marketing.
Why employer EWA costs less if you can get it
Employer-integrated EWA costs less and carries less risk because the provider reads payroll data, collects repayment through your paycheck, and charges no subscription or tips.
- Lower fees with a free path. Payactiv charges $0 for a 1–3 business day bank transfer and $0 for a real-time transfer to its Visa card with $200 or more in direct deposit per pay period, according to its pricing page. DailyPay charges $0 to access earnings in 1–3 business days and $3.49 instantly, per its fees page.
- No bank debit. Employer EWA programs take repayment out of your next paycheck. Direct-to-consumer apps debit your bank account, and the GAO flagged surprise overdraft fees when those debits hit at the wrong moment.
- Fewer bad outcomes. The CFPB measured a 0.3% charge-off rate at employer-partnered providers in both 2021 and 2022. Its direct-to-consumer sample charged off 6.5% in 2021 and 6.3% in 2022.
- No tips. In its December 2025 advisory opinion, the CFPB wrote that it “is not aware of” employer-partnered providers that solicit tips. Payactiv’s earned wage access page promises “never any tips.”
- Clearer federal status. The same opinion says employer-integrated “covered EWA” isn’t credit under federal lending law. The CFPB left direct-to-consumer apps unresolved.
Your job may already offer EWA under another name. Ask HR or check your payroll portal for “on-demand pay,” “earned wage access,” or a wallet app. Paychex runs Payactiv inside its platform, according to Payactiv’s Paychex page, and Paylocity says Payactiv backs its On-Demand Pay, Gusto and QuickBooks Payroll offer Clair, Dayforce includes on-demand pay in Dayforce Wallet, and ADP lists DailyPay, Payactiv, Tapcheck, and Immediate in its marketplace. Our directory of earned wage access companies lists who runs inside which payroll system. If your employer offers nothing, send HR our guide to EWA providers for employers, since most of them cost the employer nothing.
Is direct-to-consumer earned wage access legal?
Direct-to-consumer EWA apps operate legally in most states. Federal regulators haven’t decided whether these apps make short-term loans, and several state attorneys general have sued them as illegal payday lenders.
The CFPB’s December 23, 2025 advisory opinion clears only products that use payroll data, collect by payroll deduction, give up any claim against the worker, and skip credit checks. A bank-debit app fails the payroll deduction test. The opinion doesn’t call those apps credit. It leaves the question open.
States and cities have filed their own suits. The D.C. attorney general sued EarnIn in November 2024, and EarnIn’s counsel says a court dismissed most claims in May 2025. The Colorado attorney general sued EarnIn on August 27, 2026. Minnesota’s attorney general sued Brigit in June 2026, New York’s sued MoneyLion in April 2025, and Baltimore sued Dave in December 2025. The FTC and the Department of Justice have a case pending against Dave and its CEO. Every one of those cases targets an app that debits a bank account.
Availability depends on your state, too. Connecticut caps EWA charges at $4 an advance and $30 a month, and Cleo, Tilt, and FloatMe don’t offer advances to Connecticut residents. Maryland banned EWA tips on October 1, 2026. Check your state in our earned wage access laws by state tracker.
Who should skip pay advance apps without an employer
Skip direct-to-consumer apps if you’d use one every pay period, if your bank balance runs near zero on payday, or if your employer already offers a cheaper program.
- Repeat users. Taking a cash advance against your wages every paycheck means the timing gap never closes. You have a budget gap, and our beginner’s guide to budgeting will help more.
- Anyone close to an overdraft. A payday debit that lands before your paycheck clears can trigger a $35 bank fee, which wipes out any savings from the app.
- Workers with an employer program. Use the employer version of EWA. You’ll pay less, with no interest and no bank debit.
- People who hate subscriptions. Brigit, Tilt, and Cleo bill monthly, and Dave charges a membership, whether you borrow or not.
- Anyone in a state where your app isn’t licensed or offered. Check the app’s availability list before you link your bank.
How to use one without paying a fee
You pay $0 by choosing an app with a free standard transfer, requesting money two to five days before the bill is due, and setting every tip to $0.
- Request early. EarnIn’s free transfer usually takes 1–2 business days (up to 3), Klover’s 2–5, and Current’s up to 3.
- Turn tips to $0. EarnIn and MoneyLion say tips don’t affect your access or limit.
- Skip optional plans. Klover+, MoneyLion’s membership, and FloatMe’s membership are all optional for advances.
- Take one advance, not five. Every extra advance adds a fee if you go instant, and every one adds a payday debit.
- Look for a free alternative first. Early direct deposit at Chime, Varo, Current, SoFi, and Capital One can release your paycheck up to two days early at no cost and with no debt. Gig workers can also cash out free through Uber’s Uber Pro Card and DoorDash’s Crimson account.
The cheapest fix for surprise expenses still beats every app. A starter emergency fund of a few hundred dollars ends the fees for good, and our list of ways to get money in a hurry covers options that don’t touch your next paycheck or your financial future.
Earned wage access without employer FAQ
Conclusion: use the free transfer, then fix the gap
Earned wage access without employer involvement works, and EarnIn, Klover, MoneyLion, and Chime MyPay all let you pay $0 if you can wait a few days. Paying for speed every paycheck costs $78 to $307 a year on $100 advances, and Dave charges even when you wait. Ask your employer about a payroll-linked program first, compare the field in our best earned wage access apps roundup, and see how the money flows in how earned wage access companies make money. Then build a buffer, so next payday arrives on time.
Free guide
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
- Track your money with the tools that still work in 2026.
- The order to invest in, with the 2026 401(k) and IRA limits.
- Three ways to earn your first $100 on the side this month.
Bonus: The 7-day Personal Profitability Bootcamp, one short lesson in your inbox each day