Our Dave review finds Dave ExtraCash costs at least $5 per advance plus a membership of up to $5 a month, so a $100 advance repaid in seven days runs about 261% APR. Dave works without your employer, and our earned wage access guide explains why a payroll-linked program usually costs less.
Last checked: October 31, 2026, against each company’s own fee and terms pages.
Personal Profitability may earn a commission from partner links on this page, at no cost to you. Partners don’t decide what we recommend or where it ranks. Fees and terms are each company’s as of 2026-10-31. Confirm them on the company’s site before you apply.
Dave review: key numbers
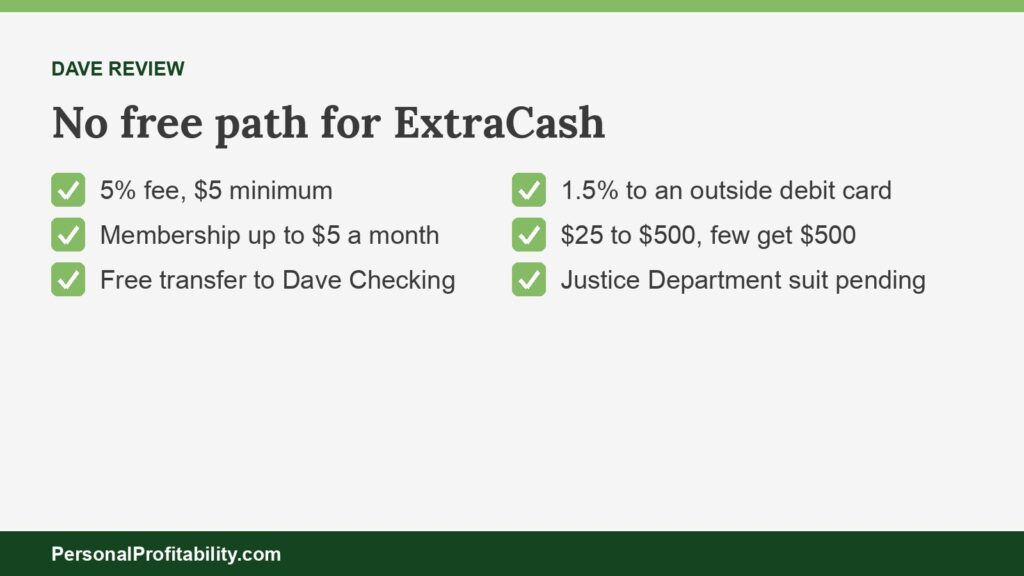
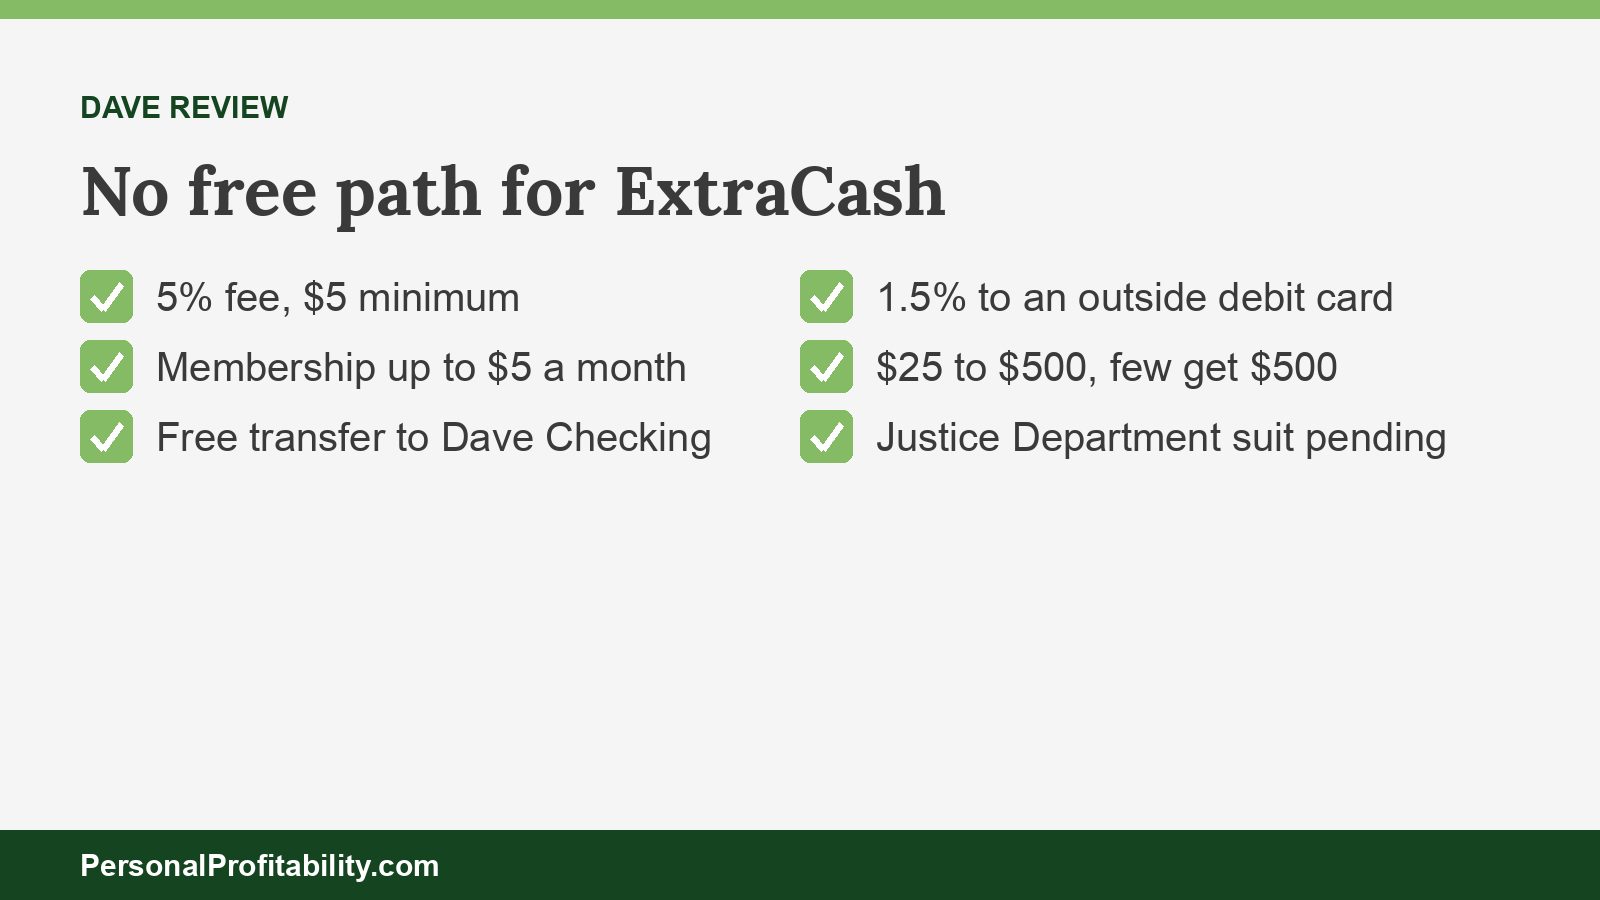
Dave charges a 5% ExtraCash fee with a $5 minimum on every advance of $25 to $500, according to its ExtraCash fee schedule, and Dave’s homepage lists a membership of up to $5 a month on top.
| Item | Dave’s published terms |
|---|---|
| Company | Dave Operating LLC (NMLS ID 2675197). Dave is a fintech company, not a bank |
| Product | Dave ExtraCash, an overdraft on an ExtraCash account at Coastal Community Bank, Member FDIC |
| Advance amounts | $25–$500. Dave says “few qualify for $500” |
| ExtraCash fee | 5% of each overdraft, $5 minimum. Dave’s Coastal fee schedule caps it at $15. Dave’s older Evolve Bank & Trust schedule lists no maximum |
| Membership | Up to $5 a month. Dave raised the fee for new members from $1 to $3 in June 2025 |
| Delivery | Free to Dave Checking in seconds. Free ACH to another bank within 3 business days. 1.5% to an outside debit card, within an hour |
| Other fees | $5 a month inactivity fee on the ExtraCash account after 12 months with no activity |
| Tips | None. Dave dropped optional tips in February 2025 |
| Credit check | None. Dave’s CashAI reviews 180+ data points from your bank account |
| Repayment | “Repayable on demand.” You agree to a settlement date when you take ExtraCash |
| App ratings | 4.80 on the App Store (924,872 ratings) and 4.75 on Google Play (636,482) as of October 2026 |
| Legal | U.S. Justice Department suit against Dave and CEO Jason Wilk (pending, motion to dismiss denied). City of Baltimore suit (pending) |
Fees and terms verified 2026-10-31.
Key takeaways
- Dave charges a fee on every ExtraCash, so Dave users can’t get cash advances for $0 the way EarnIn or Chime MyPay users can.
- Dave’s fee math favors larger advances. The $5 minimum makes a $25 advance cost 20% of the amount.
- You get free instant delivery only to Dave Checking, so Dave works best for customers who’ll move their banking to Dave.
- The Justice Department’s case against Dave and its CEO survived a motion to dismiss and is still pending.
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
Dave review: what you get
Dave gives you a checking account, an overdraft feature called ExtraCash for extra cash before payday, a savings goals account, and tools to find side work, all inside one app and all without your employer’s involvement.
Dave ExtraCash
Dave ExtraCash is the reason most people download the Dave app. Most reviewers group ExtraCash with cash advances, and so do we, though Dave structures ExtraCash as an overdraft service. You link your bank, open an ExtraCash account, and Dave lets you overdraft that account by $25 to $500. Dave then moves the money to your Dave Checking account or to another bank. Dave says it typically authorizes ExtraCash within five minutes and checks no credit. Its underwriting system, CashAI, reviews “180+ data points, including income, gig or irregular work, bank balance, and spending patterns.”
Dave’s own disclaimer matters more than the headline. “Not all members qualify for ExtraCash and few qualify for $500,” Dave’s homepage says. In its quarterly report for the period ending June 30, 2026, Dave put its average ExtraCash amount at $215 for the second quarter, so plan around $215, not $500, and expect your limit to move from week to week.
Dave also calls ExtraCash something other than a cash advance. Its About ExtraCash page says “ExtraCash isn’t a cash advance, it’s different,” and the legal structure is a bank overdraft. Regulators read it differently, which we cover in the lawsuit section below.
Dave Checking, Goals, and side-income tools
- Dave Checking: a digital account with no minimum balance and no monthly account fee, through Dave’s partner banks, plus fee-free cash at 40,000+ MoneyPass ATMs, according to Dave’s checking page. Dave requires it for ExtraCash, and it’s the only place you can receive ExtraCash instantly for free.
- Goals account: a savings account for setting money aside, with round-ups.
- Side hustle tools: part of the membership. Dave calls these features Income Opportunity Services and lists side jobs and survey offers inside the Dave app.
- Financial management tools: also part of the membership, with automated budgeting and savings goals.
- Customer service: Dave offers support by in-app chat and by phone at 844-857-3283. Dave says it offers no customer support at its headquarters.
- Dave Flex: a pay-in-four credit card Dave began testing with a small group of members in April 2026, according to its quarterly report. Most members can’t get it yet.
Dave says Coastal Community Bank, Member FDIC, insures deposit account funds, and “conditions must be met to qualify for this insurance,” so your Dave deposits get pass-through FDIC coverage when you meet the bank’s conditions. Dave’s requirements for ExtraCash are short. You link a bank account with regular deposits that Dave can read, open the ExtraCash and Dave Checking accounts, and pass Dave’s eligibility review. Dave doesn’t publish a minimum income or deposit count, so Dave sets your amount inside the app based on your account history. Sources: Dave’s homepage and About ExtraCash.
What Dave costs, and the catch
Dave costs a $5 minimum on every ExtraCash plus the monthly membership, and the catch is that Dave offers no $0 path for the advance itself, so you pay even when you wait for the free transfer.
| Fee | Amount | How to avoid the fee |
|---|---|---|
| ExtraCash fee | 5% of the advance, $5 minimum, $15 maximum on Dave’s Coastal schedule | You can’t. Dave charges the fee on every ExtraCash |
| Membership | Up to $5 a month, per Dave’s homepage. Dave’s 10-Q says Dave raised the fee for new members from $1 to $3 in mid-2025, so your price depends on when you joined | Cancel the membership |
| Transfer to Dave Checking | Free, in seconds | No fee to avoid |
| ACH to an external bank account | Free, within 3 business days | No fee to avoid |
| Express to an outside debit card | 1.5% of the transfer | Use Dave Checking or ACH |
| Inactivity fee | $5 a month after 12 months with no activity | Close the ExtraCash account when you stop using ExtraCash |
Fees and terms verified 2026-10-31. Dave charges 5% of each overdraft amount, with a $5 minimum and a $15 maximum, according to its Coastal Community Bank fee schedule (last updated July 6, 2026). Dave’s Evolve Bank & Trust fee schedule (last updated October 17, 2024) lists 5% with a $5 minimum and no maximum.
The $15 cap deserves a second look. In its quarterly report for the period ending June 30, 2026, Dave says it removed the maximum fee, which it calls the “fee cap,” “for certain Member cohorts during the second quarter of 2026.” Dave’s marketing pages describe the fee as “the greater of $5 or 5%” and never mention a cap. So a $500 ExtraCash could cost you $15 or $25. Check the fee Dave shows you in the app before you accept.
The APR math on a Dave ExtraCash advance
A flat $5 fee on a short advance turns into a triple-digit APR. Divide the fee by the amount, multiply by 365, and divide by the days until you repay. Dave says its average settlement period runs about 12 days.
| ExtraCash | Fee | Days to repay | APR equivalent |
|---|---|---|---|
| $25, to Dave Checking | $5.00 (the minimum) | 7 | 1,043% |
| $25, to Dave Checking | $5.00 | 14 | 521% |
| $100, to Dave Checking | $5.00 | 7 | 261% |
| $100, to Dave Checking | $5.00 | 12 | 152% |
| $100, to an outside debit card | $6.50 ($5 plus 1.5%) | 7 | 339% |
| $200, to Dave Checking | $10.00 | 14 | 130% |
| $500, $15 cap applies | $15.00 | 14 | 78% |
| $500, no cap | $25.00 | 14 | 130% |
The $5 minimum hits small advances hardest, and small advances are the ones most new members get. For comparison, the CFPB’s 2024 Data Spotlight put the average fee at $3.18 on a $106 advance across employer-partnered providers. Dave’s floor sits above that average before you count the membership.
What Dave costs in a year
Take a $100 ExtraCash every two weeks and you pay $130 a year in ExtraCash fees, plus up to $60 in membership, for up to $190. The CFPB found the average worker in its sample made 27 transactions a year. At Dave’s $5 minimum, 27 advances cost $135 in fees alone. That money could seed a starter emergency fund that charges you nothing the next time a bill lands early.
How Dave makes money
Dave makes most of its money from ExtraCash fees, memberships, and debit card interchange, according to its SEC filings. Dave replaced its old optional tip and express fee model with the mandatory 5% fee in February 2025, and it reported no tip revenue in 2026. Subscription revenue hit $15.1 million in the second quarter of 2026, up 87% from a year earlier, after the membership increase. Our guide on how earned wage access companies make money compares Dave’s model with tip-based and employer-paid apps.
How Dave ExtraCash repayment works
You pay Dave back automatically on the settlement date you agree to when you take the money, usually your next payday, and Dave’s terms also say ExtraCash is “repayable on demand.”
- Timing: Dave sets settlement around your forecasted paycheck date. Its quarterly report puts the average settlement period at about 12 days.
- Source of funds: Dave automatically collects the money from your Dave accounts or your linked external bank account, not from your employer’s payroll.
- On demand: Dave’s homepage footnote says “ExtraCash is repayable on demand.” Dave’s About page talks about a settlement date instead, and it doesn’t reconcile the two.
- Late payment: Dave says it charges no interest and no late fees on the cash you take. But you can’t take a new ExtraCash until you settle the old one.
- Overdraft risk: if your paycheck lands late, a pull from your outside bank can trigger that bank’s overdraft or NSF fee.
This bank-debit model is the line between Dave and employer EWA. With DailyPay or Branch, your employer repays the provider through payroll. The CFPB’s December 23, 2025 advisory opinion says “covered EWA” isn’t credit, but covered EWA repays through payroll. Dave’s product falls outside that definition. Our guide to earned wage access vs. cash advance walks through the split.
Is Dave legit? The Justice Department lawsuit and other cases
Yes, Dave is a legitimate, publicly traded company with licensed partner banks, and it’s also defending a federal lawsuit from the U.S. Justice Department and a consumer protection suit from the City of Baltimore, both pending as of October 31, 2026.
United States v. Dave, Inc. and Jason Wilk
The FTC sued Dave on November 5, 2024, in federal court in the Central District of California (No. 2:24-cv-09566). The FTC then referred the case to the Justice Department, which filed an amended complaint on December 30, 2024, and added CEO Jason Wilk as a defendant. According to the FTC’s release, the government alleges Dave advertised advances of “up to $500” but rarely offered amounts near that, charged an express fee it didn’t clearly disclose, and charged “tips” without consumers’ consent. The FTC also alleges Dave said a tip would provide meals to children while donating 10 cents per percentage point of the tip. The government seeks refunds, civil penalties, and an injunction under the FTC Act and the Restore Online Shoppers’ Confidence Act.
The court denied Dave’s motion to dismiss on September 12, 2025, and Dave answered the amended complaint on October 10, 2025, according to Dave’s own quarterly report. The FTC’s case page still lists the case as pending. Dave recorded an accrual of $9.7 million for probable legal losses across its cases as of June 30, 2026. Dave doesn’t say how it splits that figure, and no court has approved a settlement. These are allegations, and Dave disputes the claims.
Baltimore and private suits
The City of Baltimore sued Dave on December 30, 2025, calling ExtraCash “high-cost, high-frequency, small-amount, short-term loans.” The city alleges Dave “routinely charges more than 10 times the maximum APR allowed for consumer loans in Maryland, which is 33%.” Dave moved the case to federal court, and the city asked the court to return the case to state court. Both sides finished their briefs on that motion on April 22, 2026. Source: Baltimore mayor’s release.
A private class action, Russell v. Dave, alleges ExtraCash violates the Military Lending Act and the Truth in Lending Act. A federal judge denied Dave’s motion to dismiss and its motion to compel arbitration in December 2025, and Dave appealed to the Ninth Circuit. Our tracker of earned wage access laws shows how states treat products like ExtraCash.
Dave review: pros and cons
Dave’s biggest pros are fast free delivery to Dave Checking and no credit check, and its biggest cons are a fee on every advance, a monthly membership, and a pending federal lawsuit.
Pros
- Works without your employer.
- No credit check, no interest, and no late fees.
- Free instant delivery to Dave Checking, and free ACH to another bank.
- No tip prompts since February 2025.
- Dave publishes its fee schedules, so you can price an advance before you download the Dave app.
Cons
- No free path for the advance. Dave charges at least $5 on every ExtraCash, even a $25 one.
- A monthly membership of up to $5, whether you take ExtraCash that month or not.
- Dave removed the $15 fee cap for some members in 2026, and its marketing pages don’t mention a cap.
- Dave requires you to open two Dave accounts to use ExtraCash.
- Few members qualify for $500.
- The Justice Department and Baltimore suits are pending.
Who should use Dave, and who should skip ExtraCash
Dave fits someone who wants to switch banks, needs a few hundred dollars once, and has no employer EWA, and it’s a poor fit for anyone borrowing small amounts every pay period.
Dave is a good fit if you
- Have no employer earned wage access program.
- Will move your direct deposit to Dave Checking anyway, so the free instant transfer works for you.
- Need $200 or more, where the 5% fee beats the $5 minimum on a small advance.
- Need a one-time bridge, such as a tire repair before payday.
- Will cancel the membership when the gap closes.
Skip Dave if you
- Have employer EWA through DailyPay, Branch, or another provider. Those programs offer free paths and repay through payroll. Our DailyPay review shows how to pay $0.
- Need $100 or less. EarnIn’s standard transfer costs $0, and Chime MyPay’s free advance arrives within 24 hours.
- Don’t want to open a new checking account.
- Expect to take ExtraCash every pay period. That’s a budget gap, and our guide to budgeting with irregular income will help more than any app.
- Already use two or three cash advance apps. Stacked paybacks on one payday start the cycle that the Baltimore suit describes.
How Dave compares
Dave costs more than similar apps such as EarnIn and Chime MyPay on small advances because those apps offer a $0 path, and Dave costs less than Brigit or Klover on larger advances once you count their subscriptions and express fees.
| App | Needs employer? | Free path | Cost on a $100 advance | Monthly fee | Repayment source |
|---|---|---|---|---|---|
| Dave ExtraCash | No | None for the advance | $5.00 | Up to $5 | Your Dave or linked bank account |
| EarnIn Cash Out | No | Standard, usually 1–2 business days, up to 3 | $0 standard, $5.99 Lightning Speed | None | Your bank account |
| Chime MyPay | No, but needs Chime direct deposit | Within 24 hours | $0 scheduled, $3 instant | None | Your Chime account |
| Brigit Instant Cash | No | Only by emailing Brigit | Plan fee, plus an express fee on Plus | $8.99 Plus, $15.99 Premium | Your bank account |
| Klover | No | Standard, 2–5 business days | $0 standard, up to $9.49 express | Optional, $4.99 | Your bank account |
| MoneyLion Instacash | No | To MoneyLion Spend, 1–2 business days | $0 standard, $7.50 Turbo to Spend | Optional | Your bank account |
| DailyPay | Yes | Next-business-day ACH or the DailyPay Card | $0 free path, paid instant transfers | None | Your paycheck |
Fees and terms verified 2026-10-31.
For a direct matchup, read EarnIn vs. Dave and Dave vs. Brigit. Our EarnIn review, Brigit review, and Klover review cover each rival in depth. You can compare nine Dave alternatives side by side in our guide to apps like Dave, and if you have no employer program, start with earned wage access without an employer.
The Personal Profitability test
Dave fails our test on its free path and its legal record, and passes on transparency and delivery, which earns it a narrow yes for one larger, one-time need.
- Can you pay $0? No. Dave charges at least $5 on every ExtraCash, plus the membership.
- Is the paid option fair? On $200 or more, the 5% fee lands near 130% APR over two weeks. On $25, the $5 minimum tops 500%.
- Does repayment protect you? No. Dave collects from your accounts, not from payroll, so a late paycheck can cost you a bank fee.
- Are the fees easy to find? Mostly. Dave publishes its fee schedules, but its marketing pages leave out the cap, and Dave removed the cap for some members.
- Does it beat a payday loan? Yes. Our guide to earned wage access vs. payday loans shows the gap.
- Does it beat an emergency fund? No. $500 in savings costs nothing to tap and never debits your account on payday.
How to sign up for Dave
You sign up for Dave in the app by linking your bank, opening the ExtraCash and Dave Checking accounts, and taking your first ExtraCash to Dave Checking to skip the 1.5% express fee.
- Download the app from Dave’s site and create an account.
- Link the bank account where your paycheck lands.
- Open the ExtraCash account and Dave Checking account when Dave asks.
- Check your offer, and request only what the bill needs. On amounts under $100, compare the $5 fee with a free option first.
- Send the money to Dave Checking (free, in seconds) or ACH to your bank (free, within 3 business days).
- Write down your settlement date and keep that amount in the account.
- Cancel the membership when you no longer need ExtraCash, and close the ExtraCash account so the $5 inactivity fee never starts.
Dave review FAQ: common questions
Is Dave worth the fees? Our Dave review verdict
Our Dave review lands here: Dave ExtraCash works for a single, larger gap if you’ll bank with Dave, and it’s an expensive habit for small advances, since the $5 minimum and the membership never stop. If your employer offers EWA, use that first. If you need under $100, try a free option from our best earned wage access apps roundup. Either way, put the $130 or more a year you’d spend on Dave into a buffer, and check our earned wage access fees table before you pick an app.
Free guide
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
- Track your money with the tools that still work in 2026.
- The order to invest in, with the 2026 401(k) and IRA limits.
- Three ways to earn your first $100 on the side this month.
Bonus: The 7-day Personal Profitability Bootcamp, one short lesson in your inbox each day