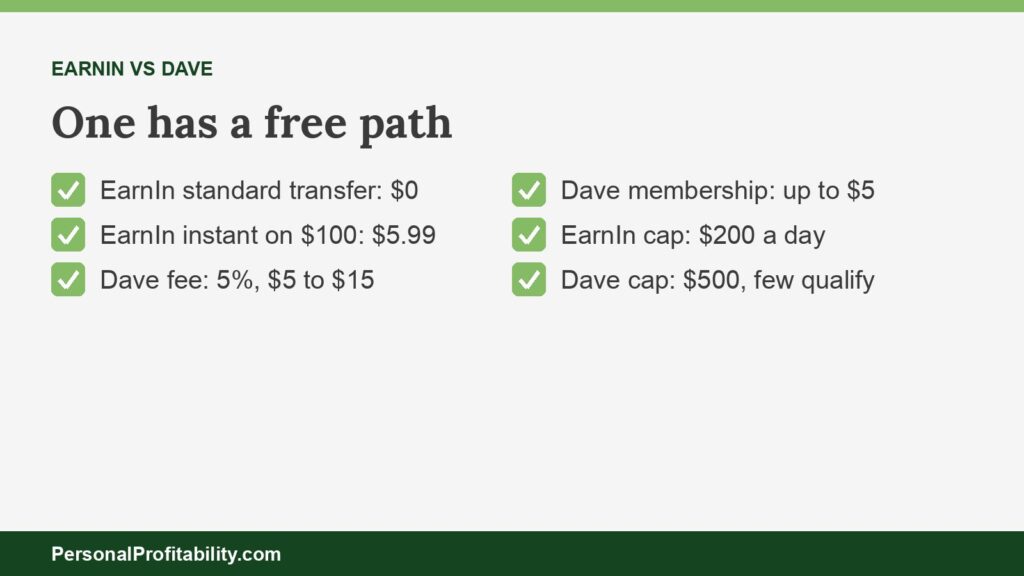
EarnIn vs Dave comes down to the fee on a $100 advance: EarnIn charges $0 if you wait one to three business days, and Dave charges $5 on every $100 ExtraCash plus a membership of up to $5 a month. EarnIn costs less for most people. Dave makes sense for a larger advance you need in minutes, if Dave approves you for one. Both are direct-to-consumer apps that collect from your bank account, which our guide to earned wage access explains.
Personal Profitability may earn a commission from partner links on this page, at no cost to you. Partners don’t decide what we recommend or where it ranks. Fees and terms are each company’s as of 2026-10-31. Confirm them on the company’s site before you apply.
Last checked: October 31, 2026, against each company’s own fee and terms pages.
EarnIn vs Dave compared at a glance
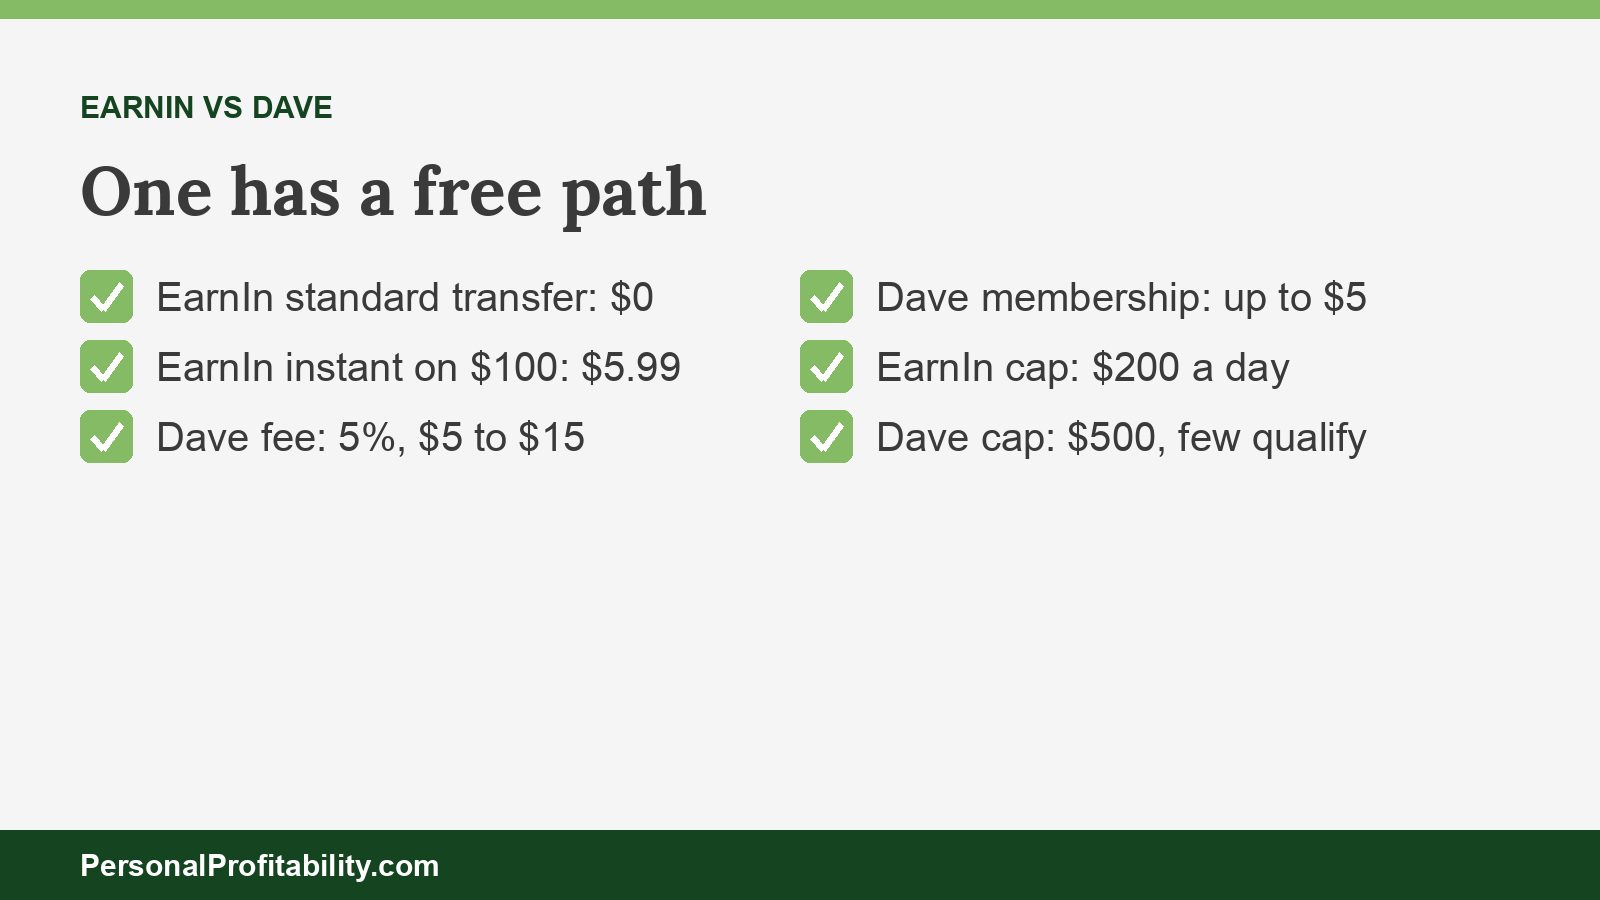
EarnIn gives you a free way to get paid early and no monthly bill, while Dave gives you a bank account and a capped fee that gets cheaper, as a percentage, the more you take. We pulled every number below from each company’s own site: its fee schedule, product page, or help center.
| Feature | EarnIn | Dave |
|---|---|---|
| What you get | Early access to pay you’ve already earned, sent to the checking account you have | An overdraft of $25–$500 on a Dave ExtraCash account, moved into Dave Checking |
| Free path | Standard transfer, $0, 1–2 business days in EarnIn’s FAQ, up to 3 on its Cash Out page | None. Free delivery still carries the 5% ExtraCash fee |
| Per-advance fee | None on standard. Lightning Speed: $3.99 ($75 or less), $5.99 ($75.01–$150), $8.99 (over $150) | 5% of each overdraft, $5 minimum. The fee schedule lists a $15 maximum, which Dave removed for some members in 2026 |
| Fast delivery | Lightning Speed, within minutes | Free to Dave Checking in seconds. An optional fee of 1.5% to an external debit card, within an hour |
| Monthly fee | None | Membership of up to $5 a month |
| Tips | Optional (removed in Colorado and Wisconsin) | None on Dave’s current fee schedule |
| Limit | Up to $200 a day and $1,000 a pay period ($100 a day in New York, $150 in Maryland) | ExtraCash amounts range from $25 to $500. Dave says “few qualify for $500” |
| New bank account? | No | Yes, Dave Checking at Coastal Community Bank |
| Repayment | EarnIn debits your linked bank account on payday | “Repayable on demand,” with a settlement date you accept up front |
| Credit check | None | None |
| Legal matters | Colorado AG suit (pending). D.C. AG suit (mostly dismissed, per EarnIn’s counsel) | FTC and Justice Department suit (pending). Baltimore suit (pending) |
| App Store rating | 4.79 (464,096 ratings) | 4.80 (924,872 ratings) |
Fees and terms verified 2026-10-31. App ratings as of October 2026. Sources: EarnIn’s fee table (last updated October 29, 2026), its Cash Out page, Dave’s ExtraCash fee schedule (last updated July 6, 2026), and Dave’s About ExtraCash page.
Dave says ExtraCash is “typically authorized within 5 minutes,” and EarnIn says Lightning Speed arrives “in minutes for a small fee.” Both cash advance apps are fast. The difference is what you pay for instant transfers. Two notes on those sources. EarnIn’s Cash Out page says a standard transfer “arrives in 1-3 business days,” while its FAQ on the same page says one to two. Dave’s homepage describes the fee as “the greater of $5 or 5%” and leaves out the $15 cap, which you’ll find only on the fee schedule.
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
What a $100 advance costs on each app
A $100 advance costs $0 on EarnIn if you wait and $5.99 if you want it now, and Dave charges $5 either way, plus up to $5 a month in membership.
EarnIn charges $5.99 for Lightning Speed on a Cash Out between $75.01 and $150, according to its fee table. Dave charges an ExtraCash fee of 5% of each overdraft amount, with a $5 minimum and a $15 maximum, according to its fee schedule. On $100, 5% is $5, which also happens to be the minimum. Take the money in seconds or wait three business days for a free bank transfer, and Dave charges the same $5.
We used the same assumptions on both sides: a $100 advance, repaid on payday 14 days later, in a state with EarnIn’s standard pricing, with no tip. To turn a flat fee into an APR, divide the fee by the amount, multiply by 365, and divide by the days until you repay.
| How you take $100 | EarnIn cost | Dave cost | APR equivalent (14 days) |
|---|---|---|---|
| Wait for the free transfer | $0 | $5.00 (ACH to your bank in up to 3 business days) | EarnIn 0%, Dave 130% |
| Fast, to the app’s own account | Not offered (EarnIn uses your bank) | $5.00 (Dave Checking, in seconds) | Dave 130% |
| Fast, to your own bank’s debit card | $5.99 (Lightning Speed) | $6.50 ($5 fee plus 1.5% express fee) | EarnIn 156%, Dave 170% |
| Fast, counting one month of Dave membership | $5.99 | $10.00 ($5 fee plus $5 membership) | EarnIn 156%, Dave 261% |
Here’s the math on the first row: $5 divided by $100 is 0.05, times 365 is 18.25, divided by 14 is 1.30, or 130%. EarnIn’s $5.99 works out to 156%. Neither company charges interest, so neither one quotes an APR. The comparison still tells you what you pay to see your own money two weeks early.
Your state can change the EarnIn column. EarnIn charges Indiana and Florida residents 5% with a $3.99 minimum, so $5 on $100. New York residents pay $3.99 on $100 or less. In Colorado and Wisconsin, where EarnIn removed tipping in July 2025, Lightning Speed on $76 to $150 costs $6.99, per EarnIn’s Colorado and Wisconsin fee page. Our earned wage access fees guide runs this math for every major provider.
Yearly cost: occasional, monthly, and every payday
Over a year, EarnIn costs less than Dave at every level of use for instant advances, because Dave’s membership runs even in months you don’t borrow and Dave’s fee has no $0 option.
Same assumptions on both sides: $100 cash advances each time, instant transfers (EarnIn’s Lightning Speed at $5.99, Dave’s free transfer to Dave Checking with the $5 ExtraCash fee), and Dave’s membership at the full $5 for all 12 months.
| How often you take $100 | EarnIn, free transfer | EarnIn, Lightning Speed | Dave, fees plus membership |
|---|---|---|---|
| Twice a year (an emergency) | $0 | $11.98 | $10 + $60 = $70 |
| Once a month (12 times) | $0 | $71.88 | $60 + $60 = $120 |
| Every payday (26 times) | $0 | $155.74 | $130 + $60 = $190 |
Look at the bottom row. Take $100 from EarnIn every two weeks at Lightning Speed and you pay $155.74 a year to borrow your own paycheck. Do the same at Dave and you pay $190. The free column matters more than either one. EarnIn lets you pay nothing if you plan up to three business days ahead, and Dave doesn’t offer that choice.
The every-payday row is also a warning. If you need an advance from either app every pay period, the problem is the budget, not the timing. A starter emergency fund of a few hundred dollars ends the cycle, and our guide to budgeting with irregular income shows how to build one on an uneven paycheck. Earning an extra $100 a pay period from a side hustle closes the same gap with no fee, and our guide to taxes for gig workers covers what you’d owe on side hustle income.
Dave vs EarnIn on limits: where Dave wins
Dave can win one job: a single advance of $300 to $500 that you need in minutes, if your account still has Dave’s $15 fee cap, because EarnIn limits you to $200 a day.
Say your car needs a $500 repair today, paid before you can drive to work. If Dave approves you for $500, the ExtraCash fee hits the $15 cap, which is 3% of the advance. If Dave removed the cap for your account, the fee is 5% of $500, or $25. EarnIn’s Daily Max tops out at $200, so you’d need three days of transfers to reach $500. At Lightning Speed that’s $8.99, $8.99, and $5.99, or $23.97, and you’d still wait until day three for the last $100. That beats Dave’s uncapped $25 but loses to the capped $15. Take EarnIn’s free transfers instead and you pay $0, but the money arrives over several business days.
That example assumes you qualify for the top limit on both apps, and most people won’t. Dave says “not all members qualify for ExtraCash and few qualify for $500.” EarnIn says your Max depends on a positive bank balance, your paycheck history, on-time repayment, and how few other cash advance apps you use, and new members start lower, per EarnIn’s Max article. EarnIn’s ceiling per pay period, $1,000, is twice Dave’s $500, so a steady EarnIn user with a high Max can reach more money over a full pay period.
- EarnIn requires a consistent direct deposit schedule, a checking account (no prepaid or savings), US residence, and age 18 or older. If you have a job, EarnIn asks for a work email or work location. EarnIn accepts Social Security, SSDI, SSI, and VA payments as income, but not unemployment. EarnIn doesn’t offer Cash Out in Connecticut.
- Dave requires you to open an ExtraCash account and a Dave Checking account at Coastal Community Bank. Dave says its CashAI reviews “180+ data points, including income, gig or irregular work, bank balance, and spending patterns” in place of a credit check.
Membership fees vs tips
Dave charges you a membership whether you borrow or not, and EarnIn asks for a tip that you can always set to $0.
Dave’s homepage lists an “up to $5 monthly membership fee for ExtraCash, Income Opportunity Services, and Financial Management Services.” At $5, that’s $60 a year before your first advance. Dave also charges a $5 monthly inactivity fee on the ExtraCash account after 12 months with no deposits or withdrawals, per its fee schedule. If you stop using Dave, close the account rather than leave it open.
EarnIn charges no subscription. EarnIn does prompt for tips in most states, and EarnIn says tips “are always optional and do not affect the quality or availability of service.” Tips are fees with better marketing, so tip $0 every time. Colorado’s attorney general alleges EarnIn’s app “required numerous taps to select no tip,” which tells you to check the tip screen before you confirm.
Dave used to ask for tips too. The FTC alleged in 2024 that Dave defaulted members into a 15% tip and charged express fees of $3 to $25. Dave’s current fee schedule shows no tips and lists a $15 maximum, which Dave’s quarterly report says Dave removed for some members in 2026.
Repayment and your bank account
Both cash advance apps collect from an account you control instead of from your paycheck, so a late or short direct deposit becomes your problem on both.
- EarnIn debits your linked bank account on payday “for the amount you transferred out, plus any optional tips or fees,” according to its repayment article. You can reschedule the debit if you contact support at least one business day ahead, by 8 a.m. Pacific time on that business day. If your paycheck lands late, your own bank can charge you an overdraft fee.
- Dave says “ExtraCash is repayable on demand,” and you agree to a settlement date when you take the money. Dave doesn’t publish a fixed debit day on the pages we read, so check the settlement date in the app before you accept.
Neither app runs a credit check. EarnIn says Cash Out “won’t get reported to credit bureaus.” Dave says “we don’t do credit checks, so there’s no impact on your score.” Neither one builds your credit or helps you pay down debt, so if that’s the goal, our guide on how to build credit from scratch is the better route.
Employer pay programs work differently from both apps. Your employer repays the provider through payroll, so nobody debits your bank. If your job offers one, read how EarnIn compares with an employer program before you download either app. If it doesn’t, our guide to earned wage access without an employer covers every option.
Lawsuits and regulators
Both companies face government lawsuits that call their advances unlicensed loans, and none of the cases has reached a final ruling.
- EarnIn, Colorado: Attorney General Phil Weiser sued EarnIn on August 27, 2026. The AG says EarnIn made more than 3.1 million loans to 56,778 Coloradans from January 2023 to July 2025 and collected more than $16 million in tips and Lightning Speed fees. The suit targets EarnIn’s direct-to-consumer product. Status: pending.
- EarnIn, D.C.: the D.C. attorney general sued on November 19, 2024, alleging an average APR over 300%. EarnIn’s counsel says a court dismissed most claims in May 2025 and that the D.C. Court of Appeals declined the AG’s mid-case appeal in February 2026. We found no official update on the remaining claims.
- Dave, federal: the FTC sued Dave on November 5, 2024, and the Justice Department filed an amended complaint on December 30, 2024, adding CEO Jason Wilk and seeking civil penalties. The FTC’s case page still lists the case as pending. A court denied Dave’s motion to dismiss on September 12, 2025, according to Dave’s quarterly report. Dave calls the case government overreach.
- Dave, Baltimore: the city sued on December 30, 2025, alleging ExtraCash is an unlicensed loan that charges more than 10 times Maryland’s 33% APR cap. Status: pending.
At the federal level, the CFPB’s December 23, 2025, advisory opinion says covered earned wage access isn’t credit under Regulation Z. Neither EarnIn’s bank-debit model nor Dave’s overdraft model fits that definition cleanly. Our explainer on whether earned wage access is a loan covers the split, and our earned wage access laws tracker covers your state.
EarnIn vs Dave: which should you pick?
Pick EarnIn if you can wait a day or two for free transfers or want to keep your bank, and pick Dave only if you want a new checking account and need a $300 to $500 advance in minutes.
Pros and cons of each
| EarnIn | Dave | |
|---|---|---|
| Pros | $0 standard transfer. No subscription and no mandatory fees. Keeps your bank. Up to $1,000 a pay period. Accepts Social Security and VA income. | Free instant delivery to Dave Checking. Fee capped at $15 for members who still have the cap, so big cash advances can cost 3% to 5%. No credit check. Banking features in one app. |
| Cons | Lightning Speed up to $8.99, and tip prompts in most states. A $200 daily cap, plus employment verification for workers. Two AG lawsuits. | No fee-free cash advance. Up to $5 a month in membership. $5 minimum fee hits small advances. External debit transfers cost 1.5% more. Federal and city lawsuits. |
Neither company lists late fees on its fee schedule. Both still collect on payday, so a missed paycheck can cost you a bank overdraft fee instead.
Pick EarnIn if
- You can plan one to three business days ahead and take the $0 standard transfer.
- You want to keep the checking account you have.
- You borrow a few times a year and don’t want a monthly bill in the other months.
- You’ll set every tip to $0.
Pick Dave if
- You want a checking account and will move your direct deposit to Dave Checking.
- You need a larger single advance fast, where the $15 fee cap, if your account still has it, brings the cost to 3% to 5%.
Skip both if
- Your employer offers a pay-access program that repays through payroll.
- Your checking balance sits near $0 on payday, where a debit can trigger an overdraft fee. Our guide on getting overdraft fees refunded helps if one already hit.
- You’d use an advance every pay period. That’s a budget gap, and no app fixes one.
Want the full picture on each? Read our EarnIn review and our Dave review, or compare more options in apps like EarnIn and apps like Dave. For other matchups, see EarnIn vs Brigit, EarnIn vs Klover, and Dave vs Brigit.
EarnIn vs Dave FAQ
EarnIn vs Dave: the bottom line
EarnIn wins the EarnIn vs Dave matchup on cost for most readers. EarnIn gives you a $0 path and no monthly bill, while Dave charges at least $5 on every advance and up to $60 a year in membership. Dave earns its spot for one reader: someone who wants a new checking account and needs $300 to $500 in minutes, where Dave’s $15 cap, if it still applies to you, keeps the fee to 3% to 5%. Whichever you pick, take the free option when you can, tip $0, and treat a second advance in the same month as a signal to build a cash buffer.
For the wider field, see how the direct-to-consumer apps compare with employer programs in earned wage access vs cash advance, or browse the best earned wage access apps.
Free guide
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
- Track your money with the tools that still work in 2026.
- The order to invest in, with the 2026 401(k) and IRA limits.
- Three ways to earn your first $100 on the side this month.
Bonus: The 7-day Personal Profitability Bootcamp, one short lesson in your inbox each day