
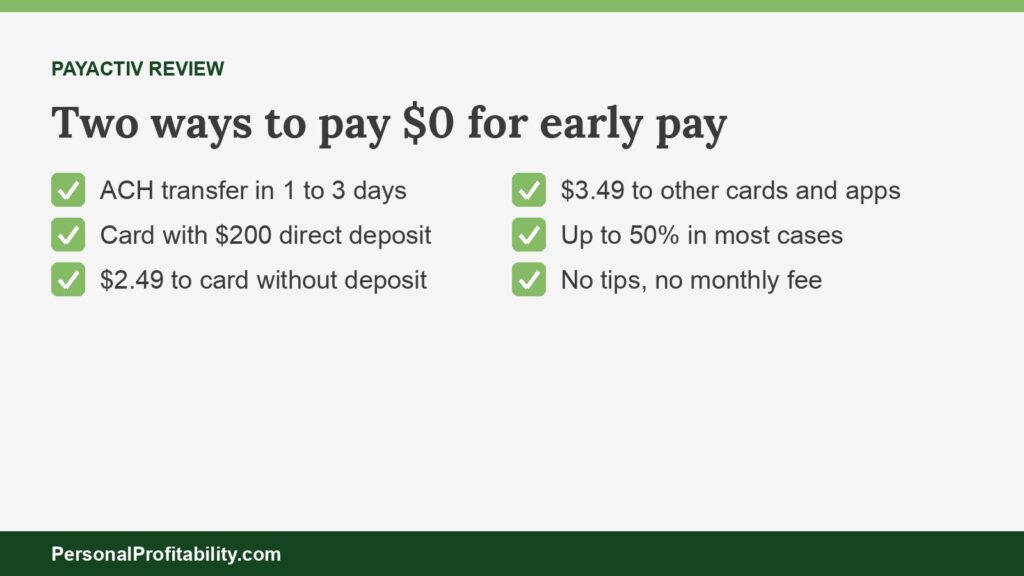
This Payactiv review lands on one rule: Payactiv costs you $0 if you wait one to three business days or send at least $200 of each paycheck to its Visa card, and $2.49 or $3.49 per instant transfer if you don’t. Your employer has to offer Payactiv, and your employer’s settings decide how much you can take. Use it to cover a short gap before payday. If you need it every pay period, fix the budget or build a small buffer first. Our guide to earned wage access covers the basics.
Eric Rosenberg, who founded Personal Profitability, wrote for Payactiv as a freelancer and later worked there as a marketing manager, until June 2026. Nobody at Payactiv reviewed this page. We held Payactiv to its own published fees and terms, the same standard we used for every other company here.
Personal Profitability may earn a commission from partner links on this page, at no cost to you. Partners don’t decide what we recommend or where it ranks. Fees and terms are each company’s as of 2026-10-24. Confirm them on the company’s site before you sign up.
Payactiv review: the key numbers
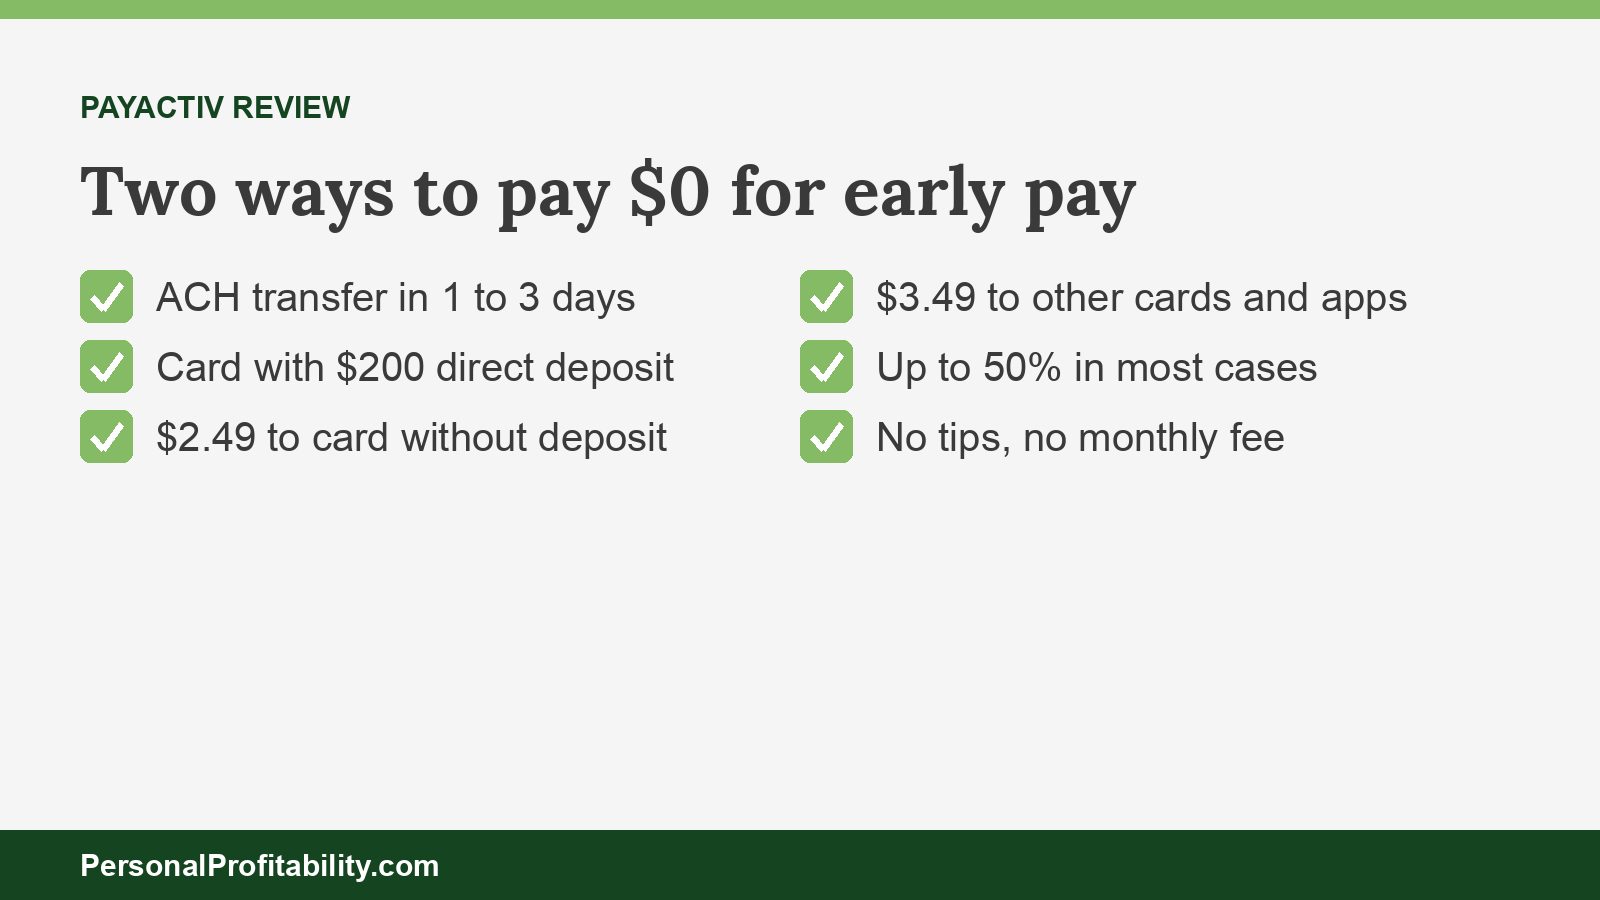
Payactiv gives you a free bank transfer, a free instant transfer to its own card if you meet a direct deposit condition, and a flat fee for everything faster. Every number in this Payactiv review comes from Payactiv’s pricing page, its card fee schedule, or its own FAQ.
| Item | Payactiv |
|---|---|
| Free transfer | $0 by ACH to your bank, 1–3 business days |
| Free instant transfer | $0 to the Payactiv Visa Card with one direct deposit of $200+ to the card per pay period |
| Instant fee to the Payactiv Card without that deposit | $2.49 |
| Instant fee to other cards, Venmo, PayPal, or Walmart Cash Pickup | $3.49 |
| Monthly program fee | None listed on the pricing page |
| Tips | “Never any tips” |
| How much you can take | “A portion” of earned wages. Its FAQ says up to 50% and $500 a pay period in most cases |
| Card | Payactiv Visa Prepaid Card from Central Bank of Kansas City, $0 monthly fee |
| Cost to employers | “At no cost” |
| Powers | UKG Wallet, OnShift Wallet, Paychex Pay on Demand, Paylocity On-Demand Pay, Paycor Wallet |
| Licenses | NMLS 2591928, Wisconsin 2591928EWA |
| App ratings | 4.7 on the App Store (84,296 ratings), 4.5 on Google Play, as of October 2026. |
We last checked the fees and terms for this Payactiv review on 2026-10-24.
Spend less, earn more and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing and side income, plus the free 7-day Bootcamp.
What you get: how Payactiv works
Payactiv lets you pull part of the pay you’ve already earned before payday, then takes it back out of your next paycheck. Your employer connects Payactiv to its payroll and time systems. As you work shifts, Payactiv calculates your earnings and shows how much you can access in the app. On payday, Payactiv deducts what you took, you receive the rest of your paycheck as usual, and the deduction shows up as a line item on your pay stub. Our guide to the earned wage access deduction shows how to read that line.
Payactiv’s FAQ says the service “is not a loan or an advance against future earnings.” Payactiv doesn’t publish what happens if your paycheck comes up short of what you took, so ask your employer before you rely on it.
How much you can get
This is Payactiv’s fuzziest term. Its pricing page says only that “employees can only access a portion of the wages they have earned to date,” with no number. Payactiv’s get-started FAQ goes further. It says the amount depends on your employer’s settings, that “in most cases” you can access up to 50% of earned wages with a maximum of $500 per pay period, and that with direct deposit to the Payactiv Card you “may be able to access up to $1,000 per request.” The Payactiv-powered programs at Paychex, Paylocity, and Paycor each say up to 50%, measured against net earnings, eligible gross pay, or earned pay. So plan on half of what you’ve earned, and treat anything above $500 a pay period as a bonus your employer may or may not allow.
How often you can use it
Payactiv doesn’t publish a limit on how many transfers you can make. Its Paychex page says Payactiv uses “the hours you worked” after every shift to recalculate what you can access, so your balance grows as you work. Payactiv doesn’t say whether balances update on weekends. That depends on when your employer sends hours to Payactiv.
The apps Payactiv powers
You may use Payactiv without seeing its name. Payactiv says its pricing “applies to our Payactiv program and our affiliated programs: UKG Wallet and OnShift Wallet.” Paychex runs Pay on Demand in Paychex Flex Perks through Payactiv, Paylocity says its On-Demand Pay is “backed by Payactiv,” and Paycor Wallet runs on Payactiv with a $200 direct deposit rule for free access. One change is coming: ZayZoon announced on October 8, 2026, that UKG picked it as the exclusive earned wage access provider for UKG Wallet in UKG Ready, rolling out in early 2027. ZayZoon’s announcement doesn’t mention UKG Pro.
Other features
- Payactiv Visa Card: a prepaid card (and a payroll card version) you can use anywhere Visa debit works, with free MoneyPass ATM withdrawals.
- Bill pay, Uber rides, and Amazon loads: Payactiv lets you pay bills and spend earned wages on these at no fee.
- Saving tools: custom goals and automatic set-asides.
- Discount marketplace for shopping deals.
- Tips and mileage: same-day access to eligible tips and mileage reimbursements.
- Off-cycle and term pay for employers who need to pay outside the schedule.
- Financial counseling: one-on-one sessions with independent professionals, plus financial education.
What it costs, and the catch
Payactiv costs $0 on the slow path and on its card with direct deposit, and $2.49 or $3.49 for instant cash anywhere else. Payactiv’s pricing page lists no monthly program fee today, and Payactiv’s own milestones page says it removed standard EWA fees in 2022.
| How you get the money | Payactiv’s fee |
|---|---|
| ACH to your bank (1–3 business days) | $0 |
| Uber rides, Amazon load, bill pay | $0 |
| Instant to the Payactiv Visa Card, with $200+ direct deposit to the card that pay period | $0 |
| Instant to the Payactiv Visa Card, without that deposit | $2.49 |
| Instant to a non-Payactiv debit or payroll card | $3.49 |
| Walmart Cash Pickup, Venmo, or PayPal | $3.49 |
The $200 direct deposit condition
Free instant access needs “one (1) successful direct deposit of $200 or more to the Payactiv Visa Card per pay period,” in Payactiv’s words. That means moving at least part of your paycheck from your bank to the Payactiv Card. Miss it in a pay period, and every instant transfer to the card costs $2.49 until the next qualifying deposit. Payactiv also says “disbursement options may vary depending on location,” and fees “may vary by program,” so check the app before you confirm.
The APR math on $2.49 and $3.49
Payactiv charges no interest, so you won’t see an APR on its disclosures. Regulators still annualize flat fees to compare them with loans: fee divided by the amount, times 365, divided by the days until payday.
| Payactiv fee | $100 for 7 days | $106 for 10 days | 27 uses a year |
|---|---|---|---|
| $0 (ACH, or card with $200+ deposit) | 0% | 0% | $0 |
| $2.49 (card, no qualifying deposit) | 130% | 86% | $67.23 |
| $3.49 (other cards, Venmo, PayPal, cash pickup) | 182% | 120% | $94.23 |
The $106 and 27-use figures come from the CFPB’s July 2024 Data Spotlight, which found the average employer-partnered transfer ran $106, the average fee paid was $3.18, and the average worker made 27 transfers a year. That worker paid $85.86 a year for speed. A $3.49 fee beats a $35 overdraft by miles, but $0 beats both, and Payactiv gives you two ways to pay $0. Our earned wage access fees guide runs this math for every big provider.
The card fee schedule
The free instant path runs through the card, so the card’s fees matter. Here’s the Payactiv Visa Prepaid Card fee schedule (last updated April 23, 2025) from Payactiv’s card411 page.
| Card fee | Amount |
|---|---|
| Card purchase, activation, monthly fee | $0 |
| Purchases in the US | $0 |
| MoneyPass ATM withdrawal | $0 |
| Out-of-network ATM withdrawal | $2.95, plus any ATM operator fee |
| ATM balance inquiry | $0.50 |
| Transfer out through Google, Apple, or Samsung wallets | $2.95 |
| Payment through a linked third-party debit card or e-wallet | $2.95 |
| Withdrawal through a third-party banking app | $2.95 |
| International transaction | 3% |
| International ATM withdrawal | $2.95 |
| Retail cash load at Green Dot (third party) | Up to $5.95 |
| Inactivity fee | $0 |
Read the $2.95 rows twice. If you take a free instant transfer to the card and then pull it out through a digital wallet, a linked debit card, or another banking app, you pay $2.95 and most of the savings disappear. Spend from the card, or use a MoneyPass ATM. The card holds up to $15,000, carries no overdraft feature, and your funds are FDIC-insured at Central Bank of Kansas City up to $250,000 if you register the card.
Is Payactiv legit?
Yes, Payactiv is a licensed earned wage access provider with a long regulatory record and no enforcement action we could find. Here’s what the record shows.
- Company: Safwan Shah (CEO), Sohail Aslam, and Ijaz Anwar founded Payactiv in 2012. Payactiv is a public benefit corporation and a Certified B Corp, and Eldridge Industries led its $100 million Series C in August 2020.
- Licenses: Payactiv lists NMLS ID 2591928 and Wisconsin earned wage access license 2591928EWA. Central Bank of Kansas City issues its cards.
- CFPB history: The CFPB issued Payactiv an approval order on December 30, 2020, finding its product as then designed was not credit. The CFPB ended that order on June 30, 2022, at Payactiv’s request, when Payactiv wanted to change its fee model.
- Federal position today: The CFPB’s December 23, 2025, advisory opinion says “Covered EWA,” repaid through payroll with no recourse and no credit check, is not credit under federal Truth in Lending law. The CFPB named no company.
- Lawsuits: We found no regulator action against Payactiv on official sources. The state attorney general suits in New York, D.C., Colorado, and Minnesota target other companies.
- Scale: Payactiv claims 245,000+ employers and 7 million+ workers served, and estimates its users have saved over $1 billion in overdraft fees, late fees, and penalties.
User Payactiv reviews run high, at 4.7 on the App Store from 84,296 ratings and 4.5 on Google Play as of October 2026. For the loan question in detail, see is earned wage access a loan, and for state rules, our earned wage access laws tracker.
The employer side: cost and integrations
Employers add Payactiv to their benefits as a financial wellness perk. Payactiv says “employers can offer Payactiv Earned Wage Access to employees at no cost,” and it publishes no employer price. If your employer pays nothing, the instant fees workers pay fund the service, which is why the free paths matter.
- Integrations: On its EWA page, Payactiv says its platform “connects to 150+ payroll and workforce systems.” Its partner page says 190+ integration partners. Payactiv names ADP, Paychex, UKG, Paycor, Oracle, and Workday.
- Marketplaces: Payactiv shows up on the ADP Marketplace (Workforce Now and Enterprise HR), Workday Marketplace, and isolved’s marketplace.
- Setup: Payactiv says referral integrations can go live immediately and reseller integrations typically within weeks.
- Customers: Payactiv names Urban Outfitters in a case study, and says it settles hundreds of millions of dollars each month for employer customers.
Employers comparing vendors can see pricing and setup across the market in our list of the best earned wage access providers.
Who it’s for, and who should skip it
Payactiv suits a worker whose employer offers it, who’ll route $200 of each paycheck to the Payactiv Card or wait a few days, and who needs a few hundred dollars now and then.
Payactiv review: pros and cons
| Pros | Cons |
|---|---|
| Free ACH, plus free instant transfers to its card with $200+ direct deposit | $2.49 or $3.49 per instant transfer otherwise |
| No tips and no monthly program fee listed | “A portion” of wages, with only a “most cases” cap of 50% and $500 |
| Bill pay, Uber, and Amazon spending at $0 | $2.95 to move card money out through wallets or linked cards |
| Repaid through payroll, not a bank debit | No published rule for a paycheck that comes up short |
| Saving tools, discounts, and counseling included | Integration count differs on its own pages (150+ vs 190+) |
Skip Payactiv if
- You’d use it every pay period. At 27 instant transfers a year, $3.49 adds up to $94.23. Steady use signals a budget gap, and our guide on budgeting with irregular income helps more than any app.
- You won’t move $200 of your pay to the Payactiv Card and you want money fast. You’ll pay $2.49 or $3.49 every time.
- You need more than about $500 a pay period. Payactiv’s typical cap may fall short.
- You’re on UKG Ready. Your wallet’s EWA provider is switching to ZayZoon in early 2027, per ZayZoon’s announcement.
- Your employer doesn’t offer it. You can’t join on your own. Our list of apps like Payactiv covers options that work without your employer.
How Payactiv compares
Payactiv has one of the lowest instant fees among big employer-integrated providers and one of the lowest published access caps. This Payactiv review lines it up against four rivals on what each company publishes.
| Provider | Free path | Instant fee | Access cap |
|---|---|---|---|
| Payactiv | ACH in 1–3 days, Payactiv Card with $200+ direct deposit | $2.49 to its card, $3.49 elsewhere | Up to 50% and $500 a pay period in most cases |
| DailyPay | Next-day ACH, DailyPay Card with direct deposit | $1.99–$3.99 ($3.49 on its fees page) | 100% of available balance, $1,000 a day |
| Branch | Branch Wallet, ACH in 3–5 days | $2.99–$4.99 (W-2) | 50% of projected wages, $1,000 a pay period |
| Tapcheck | Prizeout gift cards | “One flat ATM-like fee,” amount not published | Up to 70% of net pay |
| EarnIn (no employer needed) | Standard in 1–2 days | From $3.99 | $200 a day, $1,000 a pay period |
Cash advance apps such as Dave, Brigit, and MoneyLion work differently. Those cash advance apps make advances against deposits to your bank account and collect from that account, with no employer involved, so we left them out of the table. Your employer picks the provider for payroll-based apps, so you’ll rarely choose between these. If you’re weighing two jobs, or your employer offers both, our Payactiv vs DailyPay comparison goes line by line, and our DailyPay review covers DailyPay’s catches. EarnIn needs no employer, but EarnIn collects from your bank account on payday, and you can overdraft if the timing slips. See our EarnIn review or the full list of best earned wage access apps.
The Personal Profitability test
Payactiv passes four of our six checks and gets partial credit on two. For this Payactiv review, we judged Payactiv only by its published terms.
| Check | Result | Why |
|---|---|---|
| Is there a $0 path? | Pass | ACH and the card with $200+ direct deposit both cost $0. |
| No tips, no subscription? | Pass | “Never any tips,” and the pricing page lists no monthly fee. |
| Repaid through payroll? | Pass | Payactiv deducts from your next paycheck. |
| Employer-integrated? | Pass | Only employers and their payroll partners offer it. |
| Clear, published fees? | Partial | One table, but options “may vary” by location and program. |
| Clear access limit? | Partial | “A portion” on the pricing page, 50% and $500 “in most cases” in the FAQ. |
How to sign up for Payactiv
You sign up through a participating employer, and Payactiv charges no enrollment or activation fee. The only requirements Payactiv lists are an employer that offers it and the account details below.
- Ask HR whether your company offers Payactiv, or a Payactiv-powered program like UKG Wallet, Paychex Pay on Demand, or Paycor Wallet.
- Download the Payactiv app and enter your name, mobile number, personal email, employer name, and employee ID.
- Look at your available balance after your next shift.
- Pick a $0 path: an ACH transfer, or the Payactiv Card with $200+ of each paycheck deposited to it.
- Plan for a smaller paycheck, since Payactiv deducts what you took on payday.
Then aim for a small emergency fund. Even $500 in savings covers most of what Payactiv’s typical cap would.
Payactiv review FAQ
Payactiv review: is it worth it?
Payactiv is worth using if your employer offers it and you’ll take one of its two $0 paths. Route $200 of each paycheck to the Payactiv Card, or wait one to three days for ACH, and you pay nothing. Its $2.49 and $3.49 fees sit at the low end for instant transfers, and Payactiv asks for no tips. The catches: Payactiv publishes its access cap only as “a portion” on the pricing page, it charges $2.95 to move card money out through wallets or linked cards, and the free instant path ties part of your paycheck to its card.
The bottom line of this Payactiv review: use Payactiv for a short gap, not a monthly routine. If you pull from it every pay period, build a buffer, and compare it against the field in our best earned wage access apps roundup or against payday lenders in earned wage access vs payday loan.

Free guide
Spend less, earn more and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing and side income, plus the free 7-day Bootcamp.
- Track your money with the tools that still work in 2026
- The order to invest in, with the 2026 401(k) and IRA limits
- Three ways to earn your first $100 on the side this month
Bonus: The 7-day Personal Profitability Bootcamp, one short lesson in your inbox each day