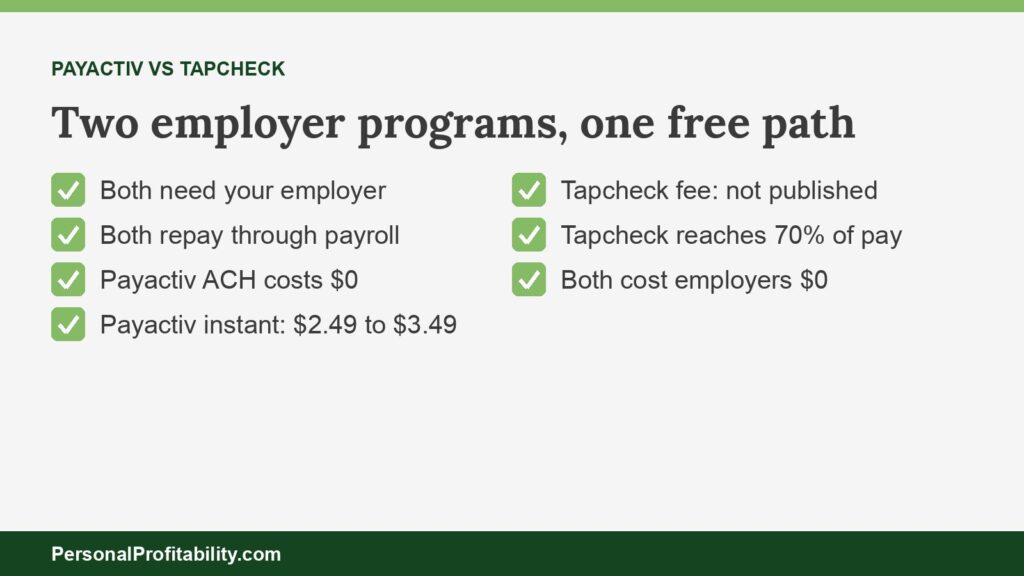
Payactiv vs Tapcheck comes down to the free path: Payactiv publishes a $0 bank transfer and $2.49 to $3.49 instant fees. Tapcheck charges one flat fee it doesn’t publish. Both need your employer, both collect through payroll, and both cost employers nothing. Our guide to earned wage access explains how employer programs work.
Eric Rosenberg, who founded Personal Profitability, wrote for Payactiv as a freelancer and later worked there as a marketing manager, until June 2026. Nobody at Payactiv reviewed this page. We held Payactiv to its own published fees and terms, the same standard we used for every other company here.
Personal Profitability may earn a commission from partner links on this page, at no cost to you. Partners don’t decide what we recommend or where it ranks. Fees and terms are each company’s as of 2026-10-31. Confirm them on the company’s site before you apply.
Last checked: October 31, 2026, against each company’s own fee and terms pages.
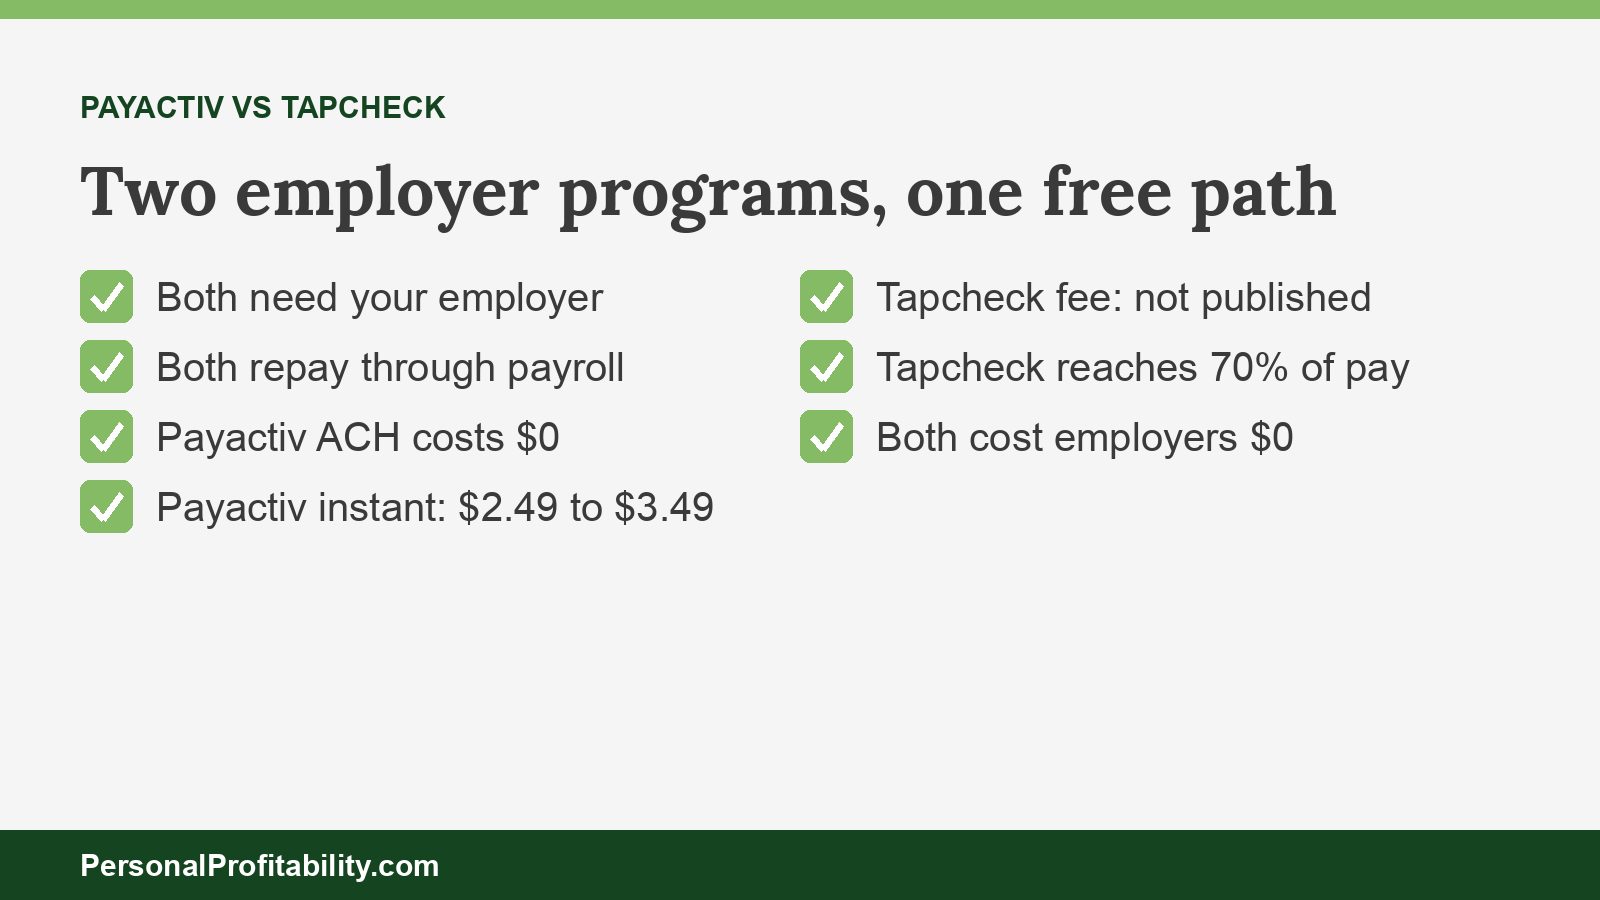
Payactiv vs Tapcheck at a glance
Tapcheck lets you reach a bigger share of your pay, and Payactiv gives you a free way to get cash. We took every row below from each company’s own pages, and we left a cell blank only where the company publishes nothing.
| Feature | Tapcheck | Payactiv |
|---|---|---|
| Needs your employer? | Yes | Yes |
| Free path to cash | None. Prizeout gift cards are fee-free. | ACH in 1–3 business days, or instant to its Visa card with $200+ direct deposit per pay period |
| Instant fee | “One flat ATM-like fee,” amount not published | $2.49 to its card without the deposit, $3.24 to Cash App (early adopters), $3.49 to other cards, Venmo, PayPal, or Walmart |
| Next-day option | “A lower transaction fee,” amount not published | $0 by ACH |
| How much | Up to 70% of net earnings, “typically $100 per day” in available wages | “A portion” of earned wages (pricing page). Up to 50% and $500 a pay period “in most cases” (get-started FAQ) |
| How often | Unlimited transfers, within daily limits your employer can set | No published limit on the number of transfers |
| Repayment | Deducted from your next paycheck | Deducted from your next paycheck |
| Own card | Tapcheck Mastercard, free to apply | Payactiv Visa Card, no credit check |
| Tips or subscription | None published | “Never any tips,” no subscription listed |
| Cost to employers | $0 | $0 |
| Integrations | 300+ payroll and timekeeping providers | 150+ payroll and workforce systems |
Fees and terms verified 2026-10-31 on Tapcheck’s homepage, Tapcheck’s employee page, Tapcheck’s contact FAQ, Tapcheck’s comparison page, Payactiv’s pricing page, and Payactiv’s get-started FAQ.
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
How Payactiv and Tapcheck work
Payactiv and Tapcheck work the same way. Your employer signs up, you see wages after each shift, and your employer takes the money back on payday. You can’t join either one on your own, so your employer’s choice usually decides which app you get.
You can download Tapcheck’s app and register “after your employer signs up with Tapcheck.” Your wages become available “shortly after your employer reports them to us,” and Tapcheck says, “Any money you request is automatically deducted from your next paycheck.” On its contact FAQ, Tapcheck adds, “it’s not a loan. So there’s nothing to repay.”
Payactiv says, “Earned Wage Access requires employer participation.” You create an account with your name, phone number, personal email, employer name, and employee ID. Payactiv pulls your hours from your employer, and the amount you take “appears as a line item on your pay stub.” Our guide to how Payactiv works walks through each step, and our explainer on the earned wage access deduction shows how to read that pay stub line.
Both models fit the CFPB’s definition of “Covered EWA” in its December 2025 advisory opinion. That definition requires repayment through payroll and no recourse against the worker. Under that opinion, the CFPB doesn’t treat either product as credit under federal Truth in Lending rules.
Payactiv vs Tapcheck fees: which costs less?
Payactiv costs less for most workers because it offers two $0 paths to cash and publishes every instant fee. Tapcheck charges a fee on every cash transfer, and it doesn’t publish the amount for instant or next-day delivery.
Tapcheck’s fees
Tapcheck charges “one flat ATM-like fee” per transfer, according to its employee page, and the company doesn’t post a dollar figure anywhere we checked. Its homepage says employees “pay only a single, ATM-like fee for transfers.” Its contact FAQ says you can get money instantly “or, for a lower transaction fee, you can get it the next day.” So next-day cash costs less than instant cash, but neither one is free.
Tapcheck waives the fee “when you transfer money for discounted gift cards through Prizeout,” and it says some brands add “up to 20% in extra gift card value.” That beats any cash fee if you planned to spend the money at that store. You can’t pay rent, a car loan, or a utility bill with one. Tapcheck says registration costs nothing and “there’s zero costs until you transfer.” You’ll see the exact fee in the app before you confirm.
Payactiv’s fees
Payactiv charges $0 for an ACH transfer in one to three business days, according to its pricing page. An instant transfer to its Visa card also costs $0 in any pay period with a $200 direct deposit to that card. Without that deposit, Payactiv calls the $2.49 charge “a load fee.” Cash App costs $3.24 in an Early Adopter Program. Other debit or payroll cards, Venmo, PayPal, and Walmart Cash Pickup cost $3.49. Amazon loads, Uber rides, and bill pay cost $0.
Payactiv says “fees and available transfer options may vary by program.” On its card411 fee schedule, Payactiv lists $2.95 to move card money out through digital wallets, linked debit cards, or banking apps. Our Payactiv fees page lists every charge.
Cost per $100 and per year
Tapcheck keeps its fee private, so we can’t quote one number. We can show what each dollar of fee means. On a $100 transfer you repay in seven days, every $1 of fee works out to about 52% APR. To get the APR equivalent, divide the fee by the amount, multiply by 365, and divide by the days until payday.
| $100 for 7 days | Fee | APR equivalent | 27 uses a year |
|---|---|---|---|
| Tapcheck gift card through Prizeout | $0 | 0% | $0 |
| Payactiv ACH, or its card with $200+ deposit | $0 | 0% | $0 |
| Tapcheck, any $1 of fee | $1.00 | 52% | $27.00 |
| Payactiv instant to its card, no deposit | $2.49 | 130% | $67.23 |
| Payactiv to Cash App (early adopters) | $3.24 | 169% | $87.48 |
| Payactiv to a debit card, Venmo, or PayPal | $3.49 | 182% | $94.23 |
| Tapcheck instant or next-day transfer | Shown in the app | 52% per $1 | $27 per $1 |
The yearly column uses the CFPB’s July 2024 Data Spotlight, which found that workers made about 27 earned wage transactions a year. The CFPB also found an average employer-partnered transfer of $106 and an average fee of $3.18. If Tapcheck’s fee in your app reads $3, that’s about $81 a year at the CFPB’s pace. A worker who uses Payactiv’s free paths pays $0.
How much can you get from each?
Tapcheck publishes the bigger share, up to 70% of your net earnings. Payactiv usually caps access at 50% of earned wages and $500 a pay period. Your employer’s settings decide the final number on both.
Tapcheck says “up to 70% of employee net earnings (minus taxes and deductions) become available for transfer right after a shift.” On its employee page, Tapcheck adds that available wages are “typically $100 per day.” Tapcheck lists “unlimited transfers” on its comparison page, with “configurable daily transfer limits” your employer controls.
Payactiv’s get-started FAQ says, “In most cases, employees can access up to 50% of earned wages, with a maximum of $500 per pay period.” With direct deposit to the Payactiv Visa Card, “you may be able to access up to $1,000 per request.” Payactiv doesn’t publish a limit on how often you can transfer. Your balance grows after each shift, from the hours your employer sends.
A bigger cap isn’t always a better deal. Tapcheck’s 70% leaves less of your paycheck for payday, and each transfer still costs a fee. If you need $300 and can wait two days, Payactiv’s ACH costs $0. On Tapcheck, three $100 days could mean three fees.
Transfer options and speed
Payactiv offers more places to send money, and Tapcheck offers two speeds for cash plus gift cards. Both run their own prepaid card with MoneyPass ATMs.
- Tapcheck: instant transfers, next-day transfers for a lower fee, Prizeout gift cards, and the Tapcheck Mastercard. On its Mastercard page, Tapcheck lists free MoneyPass ATM withdrawals, free domestic purchases, and “no cost to apply.” You can get direct deposit up to two days early. Central Bank of Kansas City, Member FDIC, issues the card. Tapcheck points to its fee schedule for other card fees.
- Payactiv: ACH to your bank, plus instant transfers to its Visa card, other cards, Venmo, PayPal, Cash App for early adopters, and Walmart Cash Pickup. You can also pay bills, Uber rides, or Amazon orders straight from earned wages. Payactiv’s card has no monthly fee, free MoneyPass ATM withdrawals, a $15,000 balance limit, and the $2.95 exit fees covered above.
Payactiv lists ACH at one to three business days and every other option as instant. Tapcheck promises instant delivery on its FAQ (“How does instantly sound?”) and doesn’t publish a business-day schedule for next-day transfers on its main pages. Neither company publishes a weekend policy on the pages we read.
Payactiv vs Tapcheck for employers
Both companies say employers pay $0, so the employer decision comes down to integrations, licenses, and what your workers pay. Tapcheck advertises “$0 Employer Cost” and calls itself “100% free for employers.” Payactiv says employers “can offer Payactiv Earned Wage Access to employees at no cost.”
Payroll integrations
Tapcheck says it “syncs data from over 300+ payroll and timekeeping software providers.” Its ADP Marketplace listing names RUN Powered by ADP, ADP Workforce Now, and ADP Vantage HCM. In an April 2026 release, Tapcheck announced embedded on-demand pay for eligible employees paid through the Paychex HR PEO. Tapcheck claims “12K+” businesses and “$1B+” accessed.
Payactiv says it “connects to 150+ payroll and workforce systems” and names ADP, Paychex, UKG, Paycor, Oracle, and Workday as active partnerships. Payactiv runs Pay on Demand inside Paychex Flex, OnDemand Pay in the Paycor app, and UKG Wallet. If your payroll company already bundles Payactiv, you may not need a new contract. Our Payactiv vs Paychex page covers that setup.
Licenses and the regulatory record
Tapcheck publishes a longer state license list. You’ll find NMLS ID 2634283 on Tapcheck’s licenses page, last updated September 1, 2026. Tapcheck names licenses or registrations in California, Connecticut, Indiana, Kansas, Maryland, Missouri, Nevada, South Carolina, Utah, and Wisconsin. Maine gets a memorandum of understanding. Payactiv lists NMLS ID 2591928 and Wisconsin earned wage access license 2591928EWA on its pricing page.
The CFPB issued Payactiv an approval order in December 2020 and ended it in June 2022 at Payactiv’s request. We found no attorney general lawsuit against either company on official sources. Check your state’s rules in our earned wage access laws tracker, and compare the wider field in our best earned wage access providers roundup.
Employers should ask each vendor four questions before signing. What do workers pay for instant and next-day cash? Is there a free cash path for every worker? What happens if a paycheck comes up short? Who funds the transfers between paydays? Payactiv publishes an answer to the first two. Tapcheck publishes neither fee, so ask for the number in writing.
The catch with each
Tapcheck’s catch is price, since every cash transfer costs a fee you see only in the app. Payactiv’s catch is the fine print around its free card path and its exit fees.
Tapcheck’s catches
- Tapcheck has no free path to cash. Only Prizeout gift cards skip the fee.
- Tapcheck doesn’t publish its instant or next-day fee.
- If you use most of a 70% cap, you get a thin paycheck on payday.
- Available wages “typically” run about $100 a day, so a large bill may take several transfers and several fees.
Payactiv’s catches
- The free instant path requires a $200 direct deposit to the Payactiv Card every pay period.
- Payactiv’s pricing page says only “a portion” of earned wages. Its get-started FAQ gives 50% and $500 “in most cases.”
- Payactiv charges $2.95 to move card money out through digital wallets, linked debit cards, or third-party banking apps.
- Payactiv says fees “may vary by program” and location.
Payactiv vs Tapcheck: which should you use?
Use whichever app your employer offers, and use it the cheap way. If you get to choose, or you’re comparing job offers, Payactiv wins on cost and Tapcheck wins on reach.
Pick Tapcheck if
- Your employer offers Tapcheck, or your job runs through the Paychex HR PEO.
- You need more than half of what you’ve earned before payday.
- You’d spend the money at a Prizeout brand anyway, so a gift card costs $0.
- You check the fee in the app and it fits your budget.
Our list of apps like Tapcheck covers employer programs with a free cash option, if you want to suggest one to HR.
Pick Payactiv if
- Your employer, Paychex, Paycor, or UKG Wallet offers Payactiv.
- You can wait one to three business days for a $0 ACH transfer.
- You’ll route $200 of each paycheck to the Payactiv Card for free instant transfers.
- You need $500 or less a pay period.
Our Payactiv review gives the full verdict. Whichever app you use, a transfer every pay period points to a budget gap, not a timing gap. A starter emergency fund costs $0 to tap and beats both apps.
Payactiv vs Tapcheck FAQ
Payactiv vs Tapcheck: the bottom line
Payactiv wins on cost because it publishes a $0 bank transfer and a $3.49 ceiling on its main instant fees. Tapcheck wins on reach with its 70% cap, but every dollar of cash costs a fee Tapcheck keeps off its website. On Tapcheck, check the fee in the app and take one transfer instead of several. Use Prizeout only for stores where you already shop.
For more head-to-heads, compare Payactiv vs ZayZoon, Payactiv vs DailyPay, Payactiv vs EarnIn, and Payactiv vs Wisely. For every provider’s fees in one table, see our earned wage access fees guide.
Free guide
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
- Track your money with the tools that still work in 2026.
- The order to invest in, with the 2026 401(k) and IRA limits.
- Three ways to earn your first $100 on the side this month.
Bonus: The 7-day Personal Profitability Bootcamp, one short lesson in your inbox each day