
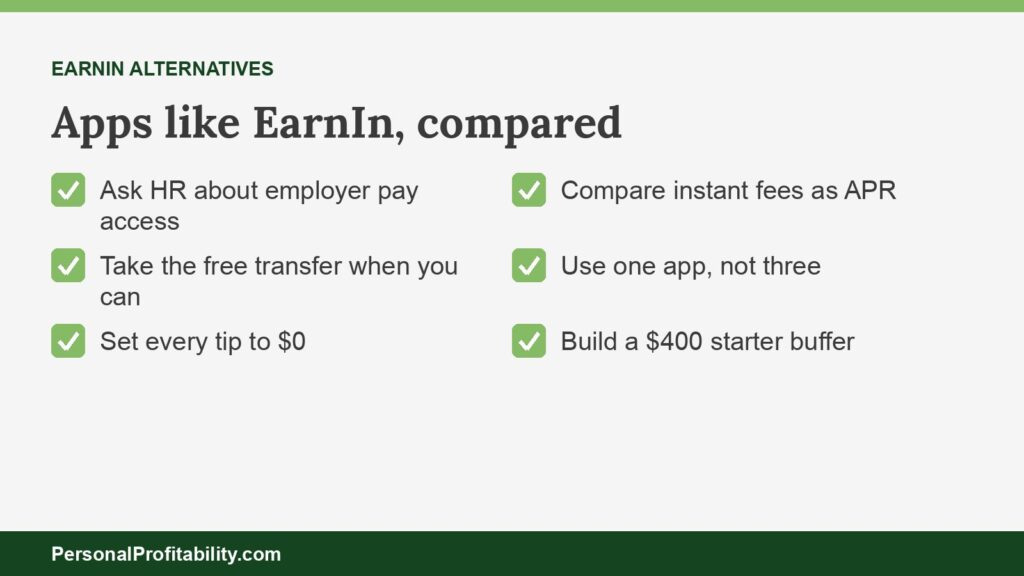
The best apps like EarnIn are Chime MyPay if you’ll bank with Chime, MoneyLion Instacash for bigger limits with no subscription, and your employer’s own program, such as Branch or DailyPay, if your job offers one. People leave EarnIn over its Lightning Speed fees of $3.99 to $8.99, the tip prompts, and two state lawsuits that call Cash Out an illegal loan. Our guide to earned wage access explains how these products work.
Eric Rosenberg, who founded Personal Profitability, wrote for Payactiv as a freelancer and later worked there as a marketing manager, until June 2026. Nobody at Payactiv reviewed this page. We held Payactiv to its own published fees and terms, the same standard we used for every other company here.
Personal Profitability may earn a commission from partner links on this page, at no cost to you. Partners don’t decide what we recommend or where it ranks. Fees and terms are each company’s as of 2026-10-24. Confirm them on the company’s site before you sign up.
EarnIn at a glance
EarnIn lets you Cash Out up to $200 a day and $1,000 a pay period from wages you’ve earned, with no employer sign-up, a free standard transfer, and repayment pulled from your bank account on payday.
| EarnIn | Published terms |
|---|---|
| Who it’s for | Workers with a steady direct deposit pay schedule and a regular checking account. |
| Needs your employer? | No. EarnIn verifies work with a work email, GPS work location, or uploaded timesheets. |
| Free path | Standard transfer in 1–2 business days, with the tip set to $0. No mandatory fees. |
| Fees | Lightning Speed in most states: $3.99 up to $75, $5.99 from $75.01 to $150, and $8.99 above $150. Early Pay costs $2.99 per paycheck. Tips are optional. |
| Max | $200 a day and $1,000 a pay period. New York gets $100 a day and Maryland $150. |
| Subscription | None |
| How you repay | EarnIn debits your linked bank account on payday |
| Credit check | None. EarnIn doesn’t report Cash Out to the credit bureaus. |
| Legal matters | Colorado AG suit (filed August 27, 2026, pending). D.C. AG suit (filed November 19, 2024, partly dismissed). EarnIn’s own suit against Maryland over its tip ban (October 2026). |
| Not offered | Connecticut |
Fees and terms verified 2026-10-24 from EarnIn’s fee table (last updated September 30, 2026) and its Cash Out page. Indiana, Florida, Texas, Ohio, Illinois, Pennsylvania, and New York get different Lightning Speed pricing, and Colorado and Wisconsin have no tips. Our EarnIn review covers every state table.
Spend less, earn more and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing and side income, plus the free 7-day Bootcamp.
Why people look for EarnIn alternatives
Most people who search for EarnIn alternatives want a similar cash advance app with no employer sign-up with a lower instant fee, no tip screen, or a company without a pending lawsuit.
Start with the fee. EarnIn charges no mandatory fee if you wait one to two business days, and that free transfer is hard to beat. But most users don’t wait. The CFPB’s 2024 Data Spotlight found that 96.6% of the fees workers paid for paycheck advances came from expedited transfers. A $100 Cash Out with $5.99 Lightning Speed, repaid in 14 days, works out to about 156% APR.
Then the tips. EarnIn calls them optional, and EarnIn says a tip doesn’t change your Max. Colorado Attorney General Phil Weiser alleges the app “required numerous taps to select no tip.” Tips are fees with better marketing, so set every one to $0, on EarnIn or anywhere else.
Then the lawsuits. Colorado’s AG says EarnIn made more than 3.1 million loans to 56,778 Coloradans from January 2023 to July 2025 and collected more than $16 million in tips and Lightning Speed fees, at APRs “of several hundred percent.” D.C.’s AG sued in 2024. These are allegations, not findings. The legal fights section below has the current status of each case.
One more catch. EarnIn sometimes offers an extra same-day transfer past your Daily Max, but only if you paid for Lightning Speed on your last one. That rule rewards the habit you should break.
Apps like EarnIn compared
Seven of these apps like EarnIn work without your employer, and three need your employer to sign up but usually cost less. Consider the free path on each before you compare instant fees. The last column shows what a $100 instant cash advance costs if you repay it in 14 days, as an APR, so you can compare a flat fee with a percentage fee.
| App | Needs your employer? | Free path | Speed fee or subscription | Max | $100 instant, 14 days | The catch |
|---|---|---|---|---|---|---|
| Chime MyPay | No | Scheduled advance within 24 hours | 3% instant ($2 minimum, $5 maximum). | Up to $750 advertised, limits $20–$1,000. | $3.00 (78% APR) | You must move your direct deposit to Chime |
| MoneyLion Instacash | No | Standard delivery to a MoneyLion Spend account | Turbo: 7.5% to Spend (capped at $14.99), 9% to another bank. | $500 ($1,000 with qualifying direct deposit). | $7.50 (196% APR) | No standard delivery to an outside bank |
| Current Paycheck Advance | No | Wait up to 3 days | Instant Access Fee, shown only in the app. | $25–$1,000. | Not published | Needs a $200+ payroll deposit into Current each month |
| Albert Instant Advance | No | Advance lands in Albert Cash free, ACH out free in 2–3 days. | Fast transfer out: greater of $5.99 or 1.75% (cap $25). | $25–$1,000. | $5.99 (156% APR) | Due in 6 days. Albert also sells a line of credit in the same flow. |
| Klover | No | Standard transfer in 2–5 business days | Express up to $3.99 ($25) to $37.49 ($750). Optional Klover+ costs $4.99 a month. | $750 | Up to $9.49 (247% APR) | Highest express fees here |
| Varo Advance | No | None | Flat fee per advance, $1.60–$100. | $250 without qualifying deposits. $700 with $800+ in deposits. | $8.00 with qualifying deposits | Every advance carries a fee |
| Dave ExtraCash | No | None | Membership up to $5 a month. The fee is 5% per advance ($5 minimum and $15 maximum). | $25–$500 | $5.00 (130% APR) to Dave Checking | Membership plus a fee on every advance. |
| Branch | Yes | Instant to Branch Wallet. ACH in 3–5 business days. | $2.99–$4.99 to a debit card (W-2 workers) | 50% of projected earned wages, $1,000 a pay period. | $2.99–$4.99 (78%–130% APR) | Free only inside Branch’s wallet |
| DailyPay | Yes | Next-business-day ACH. Instant to DailyPay Card with direct deposit. | $1.99–$3.99 in its Program Terms, $3.49 on its fees page. | Up to 100% of your available balance, $1,000 a day. | $3.49 (91% APR) | Your whole paycheck routes through DailyPay |
| Payactiv | Yes | ACH in 1–3 business days. Payactiv Card with $200+ direct deposit. | $2.49 to its card without direct deposit, $3.49 to other cards. | Up to 50% and $500 a pay period in most cases, set by your employer. | $2.49–$3.49 (65%–91% APR) | Your employer has to offer it |
| EarnIn (for comparison) | No | Standard transfer in 1–2 business days | Lightning Speed $3.99–$8.99, tips optional. | $200 a day, $1,000 a pay period. | $5.99 (156% APR) | Bank debit on payday, state lawsuits. |
Fees and terms verified 2026-10-24. APR equals the fee divided by the advance, times 365, divided by the days until repayment. Every free path in the table costs 0% APR.
EarnIn alternatives that don’t need your employer
These seven direct-to-consumer cash advance apps work the way the EarnIn app does: you link a bank account, the company reads your deposits, and you repay from your account or the company’s own account on payday. Each one lets you receive money before payday without asking your employer.
Chime MyPay: best for workers who’ll move their direct deposit
Chime MyPay beats EarnIn on the cost of speed. Chime charges nothing for a scheduled cash advance that arrives within 24 hours, and an instant cash advance costs 3% with a $2 minimum and a $5 maximum. On a $200 instant cash advance, you’d pay Chime $5 and EarnIn $8.99. Chime advertises up to $750 per pay period, its footnote lists credit limits of $20 to $1,000, and Chime says most members start between $50 and $100.
The catch is the bank switch. To qualify, you need a qualifying direct deposit of $200 or more into Chime within the past 36 days, an activated physical Chime card, and an eligible state. Chime calls MyPay “a line of credit” from The Bancorp Bank or Stride Bank, with limits based on estimated income and risk-based criteria, though Chime says it runs no credit check and doesn’t report your payment history. No subscription, no tips. Source: Chime MyPay.
MoneyLion Instacash: best for higher limits without a subscription
MoneyLion Instacash offers up to $500, or up to $1,000 if you send qualifying recurring direct deposits to a MoneyLion Spend account, with no required membership. Standard delivery to Spend costs $0. You can’t get standard delivery to an outside checking account, though. MoneyLion lists that option as “Not available.” Turbo delivery costs 7.5% of the advance to Spend, capped at $14.99, or 9% to an outside account, and MoneyLion caps each disbursement at $100.
To qualify, you need a checking account open at least two months with regular income deposits and a positive balance. MoneyLion says it runs no credit check. On repayment, MoneyLion “may deduct a partial repayment and make additional debit attempts,” which can trip overdraft fees at your bank. The legal record is longer than EarnIn’s. The CFPB won a stipulated final judgment on November 24, 2025, with $1.75 million in consumer redress, and New York’s AG sued in April 2025, alleging “more than half” of MoneyLion’s advances carried APRs above 500%. Source: MoneyLion Instacash.
Current Paycheck Advance: best for a free advance if you can wait three days
Current Paycheck Advance gives you $25 to $1,000 for free if you wait up to three days, which matches EarnIn’s free path with a higher ceiling. Current calls the product “not a loan or credit product,” runs no credit check, and doesn’t report it. Its terms say you have “NO OBLIGATION TO REPAY,” but Current blocks new advances until you do, and Current collects automatically from your next payroll deposit.
Two catches. You need at least one eligible payroll deposit of $200 or more each month into Current, and peer-to-peer, mobile check, and cash deposits don’t count. And Current shows its Instant Access Fee only inside the app, so you can’t compare it before you sign up. Source: Current’s Paycheck Advance help article.
Albert Instant Advance: best for spending the advance by debit card
Albert offers $25 to $1,000 with no subscription required, no interest, and no late fees, though Albert says “few qualify for $1,000.” Your advance lands in an Albert Cash account for free, and you can spend it there with Albert’s card. Moving it to another bank costs nothing by ACH in two to three business days, or the greater of $5.99 or 1.75% (capped at $25) for a fast transfer.
Repayment comes due six days after you advance, with one extension of up to seven days, so the APR on a paid fast transfer runs higher than EarnIn’s: $5.99 on $100 over six days is about 364%. Albert says it won’t send a late advance to collections or report it, but it can suspend access for 30 to 90 days or longer. Watch the menu, too. Albert sells a separate “Instant line of credit” from FinWise Bank, with draw fees and possible late fees, in the same “Instant” flow. Source: Albert’s cash advance help page.
Klover: best for EarnIn users who always take the free transfer
Klover works like EarnIn without a subscription requirement. Its FAQ says “Standard transfers are free” and usually take two to five business days. Advances run $25 to $750, and Klover says it runs no credit checks. You qualify once you have three consistent direct deposits from your employer, and Klover collects automatically on your next payday. Klover+ costs $4.99 a month and is optional. Klover’s terms call the service non-recourse, with no obligation to repay, though Klover may limit your service if you don’t.
Skip Klover if you want speed. Klover’s express fees run up to $3.99 on $25, $9.49 on $100, $15.25 on $200, and $37.49 on $750, the steepest published fees on this page. A $100 express cash advance at $9.49 over 14 days is about 247% APR, versus 156% at EarnIn. Klover lets you offset fees with points at 500 points per $1. A private class action, Moss v. Klover in federal court in Illinois, survived a motion to dismiss, per the Center for Responsible Lending’s tracker. Source: Klover pricing.
Varo Advance: best for a longer repayment window
Varo Advance gives you 15 to 30 days to repay, on an autopay date you pick, where EarnIn debits on your next payday. That cushion helps if your pay schedule is irregular. Varo offers up to $250 without qualifying deposits and up to $700 with $800 or more in deposits in the current or prior month. Varo Bank, N.A., calls it “a small dollar line of credit.” Varo charges no subscription, late, or penalty fees, and covered military borrowers pay nothing.
Varo charges a flat fee on every cash advance, so you get no free path. With $800 or more in deposits, that’s $8 on $100 and $16 on $200. Without them, $20 on $100 and $40 on $200. A $100 cash advance at $8 repaid in 30 days is about 97% APR. Varo also says advances are “subject to evaluation of consumer reports” and doesn’t say whether that’s a soft or hard pull. Source: Varo fees.
Dave ExtraCash: best for members who want checking and an advance in one app
Dave ExtraCash offers $25 to $500 with no credit check, and an instant transfer to Dave Checking is free. Dave says “few qualify for $500.” Dave’s fee schedule, updated July 6, 2026, charges 5% of each cash advance with a $5 minimum and a $15 maximum, plus 1.5% to send it to an outside debit card. Membership costs up to $5 a month, and Dave charges no interest or late fees. You’ll open both an ExtraCash account and a Dave Checking account at Coastal Community Bank.
For an EarnIn user, Dave costs more. EarnIn’s standard transfer is free. Dave has no fee-free advance, since the 5% fee applies whichever way you take the money. Dave also faces a federal suit filed by the FTC and later taken over by the Justice Department, plus a Baltimore suit. Our apps like Dave guide covers those cases and the cheaper options. Source: Dave’s fee schedule.
Cheaper EarnIn alternatives if your employer offers one
Employer programs usually beat EarnIn, since your employer repays the provider through payroll, so no company debits your bank account and risks an overdraft. The CFPB’s December 23, 2025 advisory opinion says this “covered EWA” isn’t credit. The CFPB also said expedite fees and voluntary tips generally aren’t finance charges for those programs. Bank-debit apps like EarnIn fall outside that definition. Ask HR before you download anything.
Branch: best for hourly and gig workers whose employer uses it
Branch gives you up to 50% of your projected earned wages in a pay period, up to $1,000, with a $500 cap per request. You’ll pay $0 for instant delivery to your Branch Wallet or a standard ACH in three to five business days. Instant delivery to an outside debit card costs $2.99 to $4.99 for W-2 workers and 2% (minimum $2.99) for 1099 accounts. Branch charges employers nothing.
The catch is the wallet. You keep the cost at $0 only if you spend from Branch’s account and card, which charges $2.00 after eight free in-network ATM withdrawals a month. Branch Flex, the version embedded in some work platforms, repays from your linked checking account like EarnIn, and Branch doesn’t offer Flex in Connecticut. Source: Branch transfer fees.
DailyPay: best for workers who want the biggest daily limit
DailyPay lets you transfer up to 100% of your available balance, capped at $1,000 a day ($1,500 to the DailyPay Card), up to five times a day. The next-business-day ACH transfer is free, and DailyPay waives instant fees for transfers to a DailyPay Card set up with direct deposit. DailyPay’s Program Terms list instant fees of $1.99 to $3.99, set by your employer, while its fees page shows $3.49. DailyPay charges no tips or subscription.
The catch: after your first transfer, your whole paycheck routes to DailyPay, which sends you the rest on payday. New York’s AG sued DailyPay in April 2025, alleging a typical seven-day $20 cash advance with a $2.99 fee works out to over 750% APR. DailyPay moved to dismiss in January 2026, and we found no ruling. Our DailyPay review has the details.
Payactiv: best for workers who’ll use a free card with direct deposit
Payactiv charges $0 for an ACH transfer in one to three business days and $0 for a real-time transfer to the Payactiv Visa Card if you get at least $200 per pay period by direct deposit. Without that deposit, the card transfer costs $2.49. Transfers to other debit cards, Venmo, PayPal, or Walmart Cash Pickup cost $3.49. Payactiv promises “always a free option and never any tips,” and employers pay nothing. You also get free financial counseling, bill pay, and saving tools.
The catch: your employer’s settings decide your limit. Payactiv’s FAQ says you can reach up to 50% and $500 a pay period in most cases. You may already have Payactiv under another name, since UKG Wallet, Paychex, Paylocity, and Paycor run their on-demand pay through it. Our Payactiv review and our list of apps like Payactiv compare it with other employer programs. Source: Payactiv pricing.
The APR math on a typical EarnIn advance
A typical paid cash advance costs a triple-digit APR at EarnIn and most of its alternatives, even though none of them charges interest, and the free path costs 0% everywhere it exists.
The CFPB’s 2024 data gives the baseline: the average advance was $106, the average fee when a worker paid one was $3.18, and the average worker made 27 transactions a year. The CFPB put that at an illustrative 109.5% APR over about 10 days. Here’s what 27 instant $100 advances a year would cost at each app’s published price.
| App | Fee on one $100 instant advance | 27 advances a year | Using only the free path |
|---|---|---|---|
| Payactiv (to its card, no direct deposit). | $2.49 | $67.23 | $0 |
| Chime MyPay | $3.00 | $81.00 | $0 |
| DailyPay (fees page) | $3.49 | $94.23 | $0 |
| EarnIn Lightning Speed | $5.99 | $161.73 | $0 |
| Dave ExtraCash | $5.00 plus up to $60 a year in membership. | $195.00 | No free path ($135 in fees plus membership). |
| MoneyLion Turbo to Spend | $7.50 | $202.50 | $0 |
| Klover express | Up to $9.49 | Up to $256.23 | $0 |
Fees and terms verified 2026-10-24. Switching from EarnIn’s Lightning Speed to Chime MyPay’s instant fee saves about $80 a year at that pace. Switching from Lightning Speed to EarnIn’s own free transfer saves $161.73. The cheapest EarnIn alternative is often EarnIn with a little patience. Our earned wage access fees guide runs the same math for more providers.
Do apps like EarnIn offer budgeting tools and other features?
Several apps like EarnIn bundle budgeting tools, credit building, or overdraft protection with the cash advance, but the extra features matter less than the fee you pay for the money itself.
- Overdraft protection: With Chime’s separate SpotMe feature, members who get $200 or more in monthly qualifying direct deposits can overdraw up to $20 at first and up to $200 later, and Chime charges no overdraft fees. EarnIn’s Balance Shield sends an alert when your balance drops below a level you set, from $0 to $500.
- Credit building: EarnIn Cash Out doesn’t report to the bureaus, but the EarnIn Card does. Brigit puts its Credit Builder in a $15.99 monthly plan. A secured card does the same job for less, as our guide to building credit from scratch explains.
- Early direct deposit: Chime, Varo, and Current let you receive your paycheck up to two days early for free. EarnIn charges $2.99 per paycheck for Early Pay.
- Speed: EarnIn says Lightning Speed typically arrives within 30 minutes, and Dave advertises ExtraCash in five minutes or less. You pay for those minutes, so plan around bills a day or two ahead and use the free transfer.
Watch the monthly charges that ride along with these features. Albert’s paid plans cost $19.99 to $39.99 a month, and Brigit’s run $8.99 to $15.99. Our apps like Brigit guide shows how a subscription turns a small cash advance into a triple-digit APR. Free budgeting tools exist elsewhere, and our beginner’s guide to budgeting covers the basics of managing your finances without a paid app.
How users rate EarnIn and its alternatives on the App Store and Google Play
Users rate every cash advance app on this page between 4.4 and 4.9 stars, so ratings won’t separate a cheap app from a costly one.
| App | App Store rating | Google Play rating |
|---|---|---|
| EarnIn | 4.79 (464,096 ratings) | 4.82 (310,047) |
| Chime | 4.83 (1,627,532) | 4.73 (1,132,935) |
| MoneyLion | 4.77 (330,252) | 4.46 (220,126) |
| Current | 4.77 (197,131) | 4.44 (180,028) |
| Albert | 4.65 (339,392) | 4.45 (162,824) |
| Klover | 4.76 (396,041) | 4.64 (174,338) |
| Varo | 4.86 (233,539) | 4.46 (245,364) |
| Dave | 4.80 (924,872) | 4.75 (636,482) |
| Branch | 4.75 (68,172) | 4.6 (37.6K) |
| DailyPay | 4.83 (508,616) | 4.7 (247K) |
| Payactiv | 4.74 (84,296) | 4.5 (46.4K) |
Ratings as of October 2026, from Apple’s App Store and each app’s Google Play listing. Stars reward speed and an easy sign-up. They don’t show what users paid in fees and tips, and the Colorado AG’s complaint describes one EarnIn customer who took 1,151 advances and paid $4,038.50 in Lightning Speed fees. Weigh the fee table above more heavily than the stars.
Are EarnIn and its alternatives legal? The lawsuits, and where they stand
EarnIn and most of its direct-to-consumer rivals operate legally today, but regulators in several states argue their cash advances are unlicensed loans, and no court has issued a final ruling on that question.
- Colorado v. EarnIn: filed August 27, 2026, in Denver District Court under the state’s consumer credit and payday lending laws. The AG says consumers paid a tip or expedite fee on more than 92% of transactions, for an average APR near 388%. Pending. Source: Colorado AG.
- D.C. v. EarnIn: filed November 19, 2024, alleging an average APR over 300% on instant Cash Outs against D.C.’s 24% cap. EarnIn’s lawyers say the court dismissed most claims in May 2025. The Center for Responsible Lending’s tracker listed the case in discovery as of September 2026. Source: D.C. AG.
- EarnIn v. Maryland: Law360 reported in October 2026 that EarnIn sued Maryland’s attorney general and financial regulation commissioner, arguing the state’s ban on EWA tips, in effect since October 1, 2026, violates the First Amendment.
- MoneyLion: CFPB judgment with $1.75 million in redress (November 24, 2025). New York AG suit pending, with a motion to dismiss filed January 23, 2026.
- Dave: FTC and Justice Department suit pending in federal court in Los Angeles, plus suits from Baltimore and Montgomery County, Pennsylvania.
- DailyPay: New York AG suit pending, no ruling found on DailyPay’s motion to dismiss.
- Chime MyPay, Current, Varo, Branch, and Payactiv: no government action found against these products.
The federal picture leans toward the industry for employer programs. Congress hasn’t passed H.R. 9330, which would declare compliant EWA “not credit” and override state laws, and the House Financial Services Committee approved it 29 to 22 on June 30, 2026. Our explainers on whether earned wage access is a loan and on earned wage access laws by state track each change.
How to choose an app like EarnIn
Pick the app that gives you a $0 path you’ll use, with repayment you can cover on payday, and work through these questions in order before using any of them.
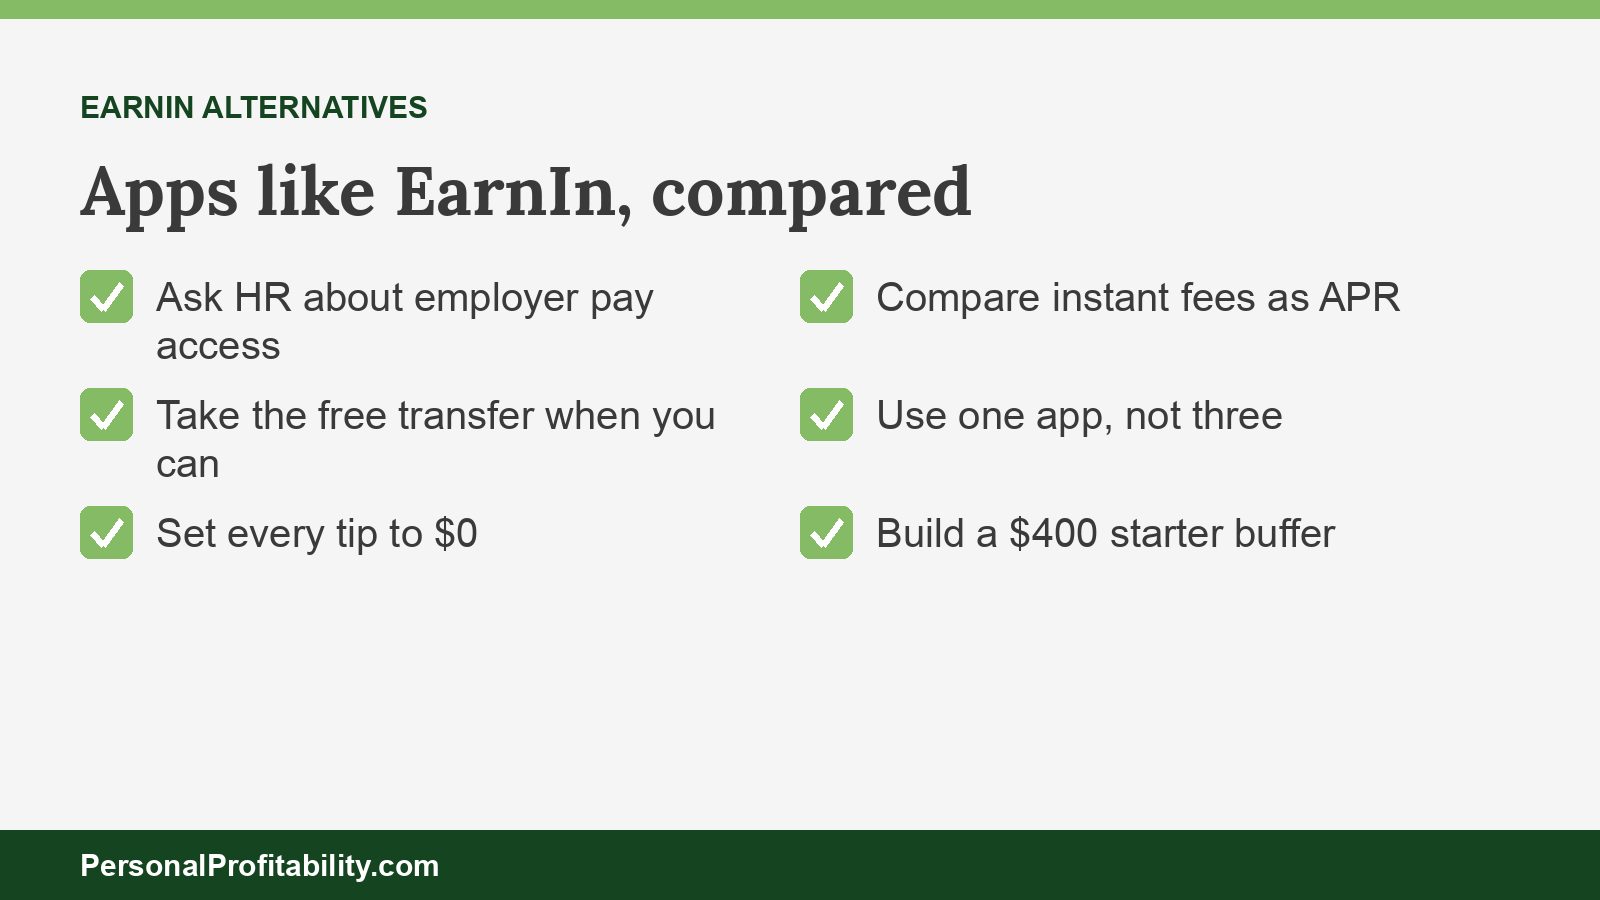
- Does your employer offer earned wage access? Ask HR or check your payroll app. If Branch, DailyPay, Payactiv, or another program is available, start there. Payroll repayment means no bank debit.
- Will you wait a day or two? If yes, EarnIn’s standard transfer, Klover’s standard transfer, and Current’s three-day option all cost $0. Staying on EarnIn may be the cheapest choice.
- Will you move your direct deposit? If yes, Chime MyPay caps its instant fee at $5, the lowest cap on this page. MoneyLion and Current also reward a deposit switch.
- What advance amounts do you need? EarnIn caps you at $200 a day. MoneyLion, Current, and Albert advertise up to $1,000, and Chime’s footnote allows limits up to $1,000. Few users qualify for the top amount.
- Can you cover the debit? If your paycheck lands late or short, a bank debit can trigger an overdraft fee at your own bank. Pick a payday you trust.
- Is the app offered in your state? EarnIn isn’t available in Connecticut, and several rivals skip Connecticut, Maine, or D.C.
Eligibility requirements to check first
- EarnIn: a consistent direct deposit schedule, a checking account (no prepaid or savings accounts), US residence, and age 18 or older.
- Chime MyPay: a $200+ qualifying direct deposit into Chime in the past 36 days and an activated Chime card.
- MoneyLion: a checking account open at least two months, with regular income deposits and a positive balance.
- Current: at least one $200+ payroll deposit into Current each month.
- Klover: three consistent direct deposits from your employer.
- Albert: a linked bank account with a long transaction history and an Albert Cash account.
Avoid stacking apps. EarnIn says your Max depends partly on how few other cash advance apps you use, and juggling two or three repayment dates on one paycheck is how a timing gap becomes a budget gap. For the full field, see our list of the best earned wage access apps.
When none of these EarnIn alternatives fit
If you’d use one of these apps every pay period, the fix is a buffer, not a better app. EarnIn and its rivals solve a timing gap between work and payday. They don’t solve a gap between income and spending.
- Build a starter emergency fund. Even $400 covers the expense the Federal Reserve uses as its benchmark, and 37% of adults told the Fed in late 2025 they wouldn’t cover it with cash or its equivalent. Our guide to emergency funds shows how to start.
- Ask the biller for time. Utilities, landlords, and medical offices often accept a short delay or a payment plan for free. Our list of ways to get money in a hurry covers more no-fee options.
- Skip payday loans. A payday loan costs more than any app on this page. See our earned wage access vs. payday loan comparison.
- Fix the budget. Our irregular income budget guide helps if your hours swing from week to week.
Apps like EarnIn: FAQ
The cheapest app like EarnIn is the one you use for free
If your employer offers Branch, DailyPay, or Payactiv, use it, since payroll repayment beats a bank debit. If not, Chime MyPay charges the least for instant delivery on a $100 cash advance, and MoneyLion and Current give you higher limits. EarnIn’s own free transfer still beats any paid option. Compare more choices in our guide to the best earned wage access apps, our earned wage access hub, and our lists of apps like Dave, apps like Brigit, apps like MoneyLion, and apps like Klover. Then start a $400 buffer so the next gap costs you nothing.

Free guide
Spend less, earn more and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing and side income, plus the free 7-day Bootcamp.
- Track your money with the tools that still work in 2026
- The order to invest in, with the 2026 401(k) and IRA limits
- Three ways to earn your first $100 on the side this month
Bonus: The 7-day Personal Profitability Bootcamp, one short lesson in your inbox each day