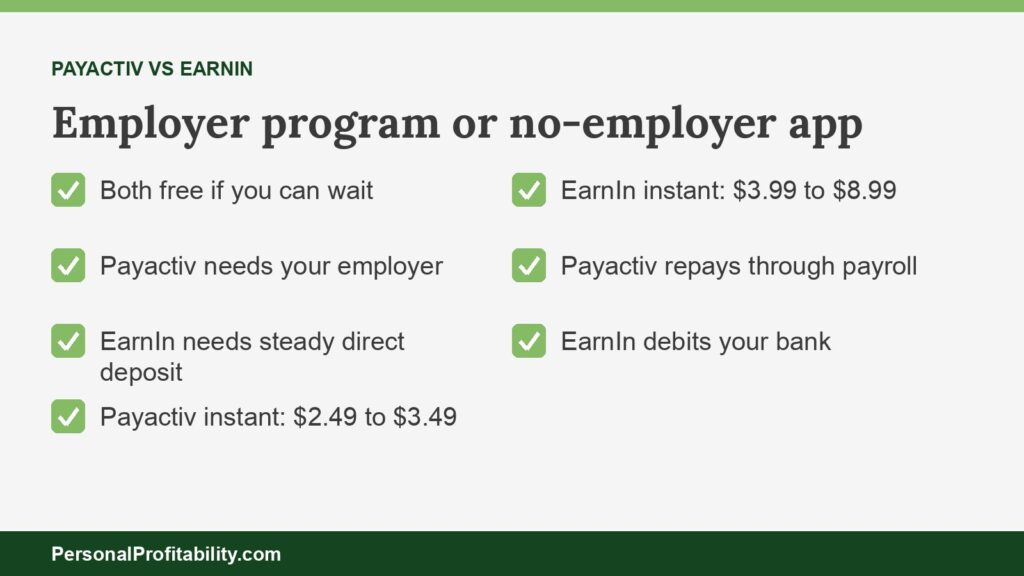
Payactiv vs EarnIn comes down to your job: Payactiv needs your employer and costs $0 to $3.49 per transfer, while EarnIn Cash Out needs no employer and costs $0 to $8.99 in most states. Payactiv collects from your paycheck. EarnIn collects from your bank account. Neither charges interest or a subscription. Our guide to earned wage access explains how both models work.
Eric Rosenberg, who founded Personal Profitability, wrote for Payactiv as a freelancer and later worked there as a marketing manager, until June 2026. Nobody at Payactiv reviewed this page. We held Payactiv to its own published fees and terms, the same standard we used for every other company here.
Personal Profitability may earn a commission from partner links on this page, at no cost to you. Partners don’t decide what we recommend or where it ranks. Fees and terms are each company’s as of 2026-10-31. Confirm them on the company’s site before you apply.
Last checked: October 31, 2026, against each company’s own fee and terms pages.
Payactiv vs EarnIn at a glance
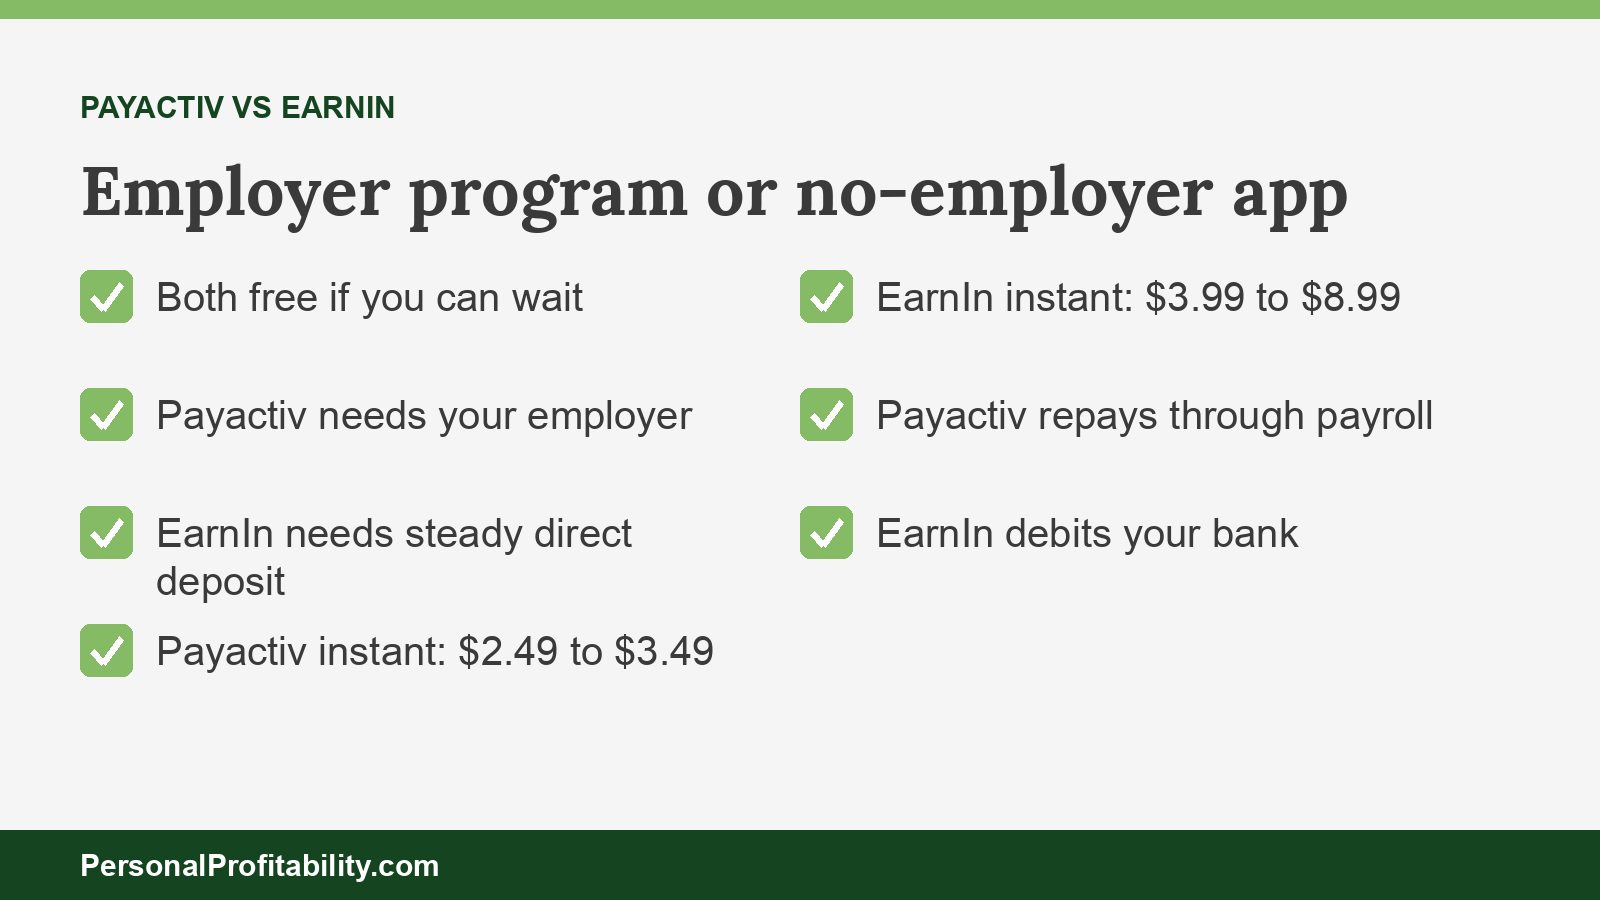
EarnIn works for almost anyone with steady direct deposit, and Payactiv works only through a participating employer but charges less for speed. We took every row below from each company’s own fee table, pricing page, or help center.
| Feature | EarnIn Cash Out | Payactiv |
|---|---|---|
| Needs your employer? | No | Yes |
| Free path | Standard speed, usually 1–2 business days, up to 3, $0 | ACH in 1–3 business days, or instant to its Visa card with $200+ direct deposit per pay period, $0 |
| Instant fee, most states | Lightning Speed: $3.99 (up to $75), $5.99 ($75.01–$150), $8.99 (over $150) | $2.49 to its card without the deposit, $3.24 to Cash App (early adopters), $3.49 to other cards, Venmo, PayPal, or Walmart |
| Tips | Optional, except in Colorado and Wisconsin | “Never any tips” |
| Subscription | None | None listed |
| How much | Up to $200 a day and $1,000 a pay period ($100 a day in New York, $150 in Maryland) | “A portion” of earned wages on its pricing page. Its get-started FAQ says up to 50% and $500 a pay period “in most cases,” and up to $1,000 a request with card direct deposit |
| Repayment | EarnIn debits your linked bank account on payday | Your employer deducts it from your next paycheck |
| Credit check | None, and EarnIn doesn’t report Cash Out to credit bureaus | None for its Visa card |
| Where it’s unavailable | Connecticut, plus other states for some features | Anywhere your employer doesn’t offer it |
Fees and terms verified 2026-10-31 on EarnIn’s fee table (last updated October 29, 2026), EarnIn’s Cash Out page, Payactiv’s pricing page, and Payactiv’s get-started FAQ.
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
Who can use Payactiv or EarnIn?
You can use Payactiv only through a participating employer. EarnIn users need only a job, or eligible benefits, paid by direct deposit on a steady schedule. That one difference decides the choice for most workers, since you can’t sign up for Payactiv on your own.
Payactiv’s requirements
- An employer, or a payroll program such as UKG Wallet, Paychex Pay on Demand, or Paycor Wallet, that offers Payactiv. Payactiv’s employee page says, “Earned Wage Access requires employer participation.”
- Your name, mobile phone number, personal email, employer name, and employee ID to create an account.
- For the optional Payactiv Visa Card: US residence and age 18 or older. Payactiv says the card needs no bank account and no credit check.
EarnIn’s requirements
- A consistent direct deposit pay schedule: weekly, biweekly, semi-monthly, or monthly.
- A primary residence in the US, age 18 or older, a US checking account, and a US cell phone number. EarnIn can’t send money to prepaid or savings accounts.
- A work email or work location if you have a job. EarnIn also accepts Social Security, SSDI, SSI, and VA payments, but not unemployment.
- A state where Cash Out is available. EarnIn stopped offering Cash Out in Connecticut at the end of 2023.
Requirements verified 2026-10-31 in EarnIn’s Who can use EarnIn article. EarnIn says it doesn’t contact your employer, beyond a one-time email to verify a work address. EarnIn also sells payroll to employers under the EarnIn Payroll name, but you can use Cash Out without EarnIn Payroll.
How much can you get from each?
EarnIn caps Cash Out at $200 a day and $1,000 a pay period. Payactiv usually caps access at 50% of earned wages and $500 a pay period. Both set your personal limit lower or higher based on factors you only partly control.
EarnIn calls your limit your Max. In its Max article, EarnIn sets the Daily Max at $100 for New York residents, $150 for Maryland residents, and up to $200 elsewhere. EarnIn bases your Base Max on a positive bank balance, your paycheck history, on-time repayment, and “using fewer cash advance apps.” New members may start lower. EarnIn may offer an extra same-day transfer past your Daily Max, but only if you used Lightning Speed on your previous transfer. With the EarnIn Card, EarnIn’s Live Pay feature raises the limit to $1,500 a pay period.
Payactiv lets your employer set the limit. In its get-started FAQ, Payactiv says, “In most cases, employees can access up to 50% of earned wages, with a maximum of $500 per pay period.” With direct deposit to the Payactiv Visa Card, “you may be able to access up to $1,000 per request.” Your balance grows after each shift. Payactiv calculates it from the hours and payroll data your employer sends. Our guide to how Payactiv works covers those limits in detail.
Payactiv vs EarnIn fees: which costs less?
Payactiv costs less for instant money on every amount we tested, and both cost $0 if you can wait. EarnIn charges $5.99 to deliver $100 instantly in most states. Payactiv charges $3.49 to a debit card, $2.49 to its own card, or $0 to its card with qualifying direct deposit.
EarnIn’s fees
EarnIn charges $0 for standard speed and $3.99 to $8.99 for Lightning Speed on Cash Out in most states, according to its fee table. A few states get their own pricing, which EarnIn posts in separate help articles:
| Where you live | EarnIn Lightning Speed on Cash Out | Tips |
|---|---|---|
| Most states | $3.99 (up to $75), $5.99 ($75.01–$150), $8.99 (over $150) | Optional |
| Indiana and Florida | 5% of the transfer, $3.99 minimum | Optional |
| New York | $3.99 ($100 or less), $5.99 (over $100) | Optional |
| Colorado and Wisconsin | $4.99 ($10–$75), $6.99 ($76–$150), $9.99 ($150.01–$200) | None since July 2025 |
Fees verified 2026-10-31 in EarnIn’s fee table and its Indiana, Florida, and New York and Colorado and Wisconsin articles. EarnIn also charges $2.99 per paycheck for Early Pay. Its bank-provided Cash Out Link product adds a $1.99 service fee on each transfer. Tips are fees with better marketing, and EarnIn says tips don’t affect your Max, so set every tip to $0.
Payactiv’s fees
Payactiv charges $0 for ACH and for instant transfers to its card with $200 of direct deposit per pay period, according to its pricing page. Other instant transfers cost $2.49 to $3.49. Payactiv lists $2.49 for its card without the deposit and $3.24 for Cash App in an early adopter program. Other debit cards, Venmo, PayPal, and Walmart Cash Pickup cost $3.49. Payactiv says fees “may vary by program,” and its card charges $2.95 to move money out through digital wallets or linked cards. Our Payactiv fees page lists every charge.
Cost per $100, both ways
| $100 for 7 days | Fee | APR equivalent |
|---|---|---|
| EarnIn, standard speed, $0 tip | $0 | 0% |
| Payactiv, ACH or card with $200+ deposit | $0 | 0% |
| Payactiv, instant to its card without the deposit | $2.49 | 130% |
| Payactiv, instant to a debit card | $3.49 | 182% |
| EarnIn Lightning Speed, New York | $3.99 | 208% |
| EarnIn Lightning Speed, Indiana or Florida | $5.00 | 261% |
| EarnIn, standard speed, $5 tip | $5.00 | 261% |
| EarnIn Lightning Speed, most states | $5.99 | 312% |
| EarnIn Lightning Speed, Colorado or Wisconsin | $6.99 | 364% |
To get the APR equivalent, divide the fee by the amount, multiply by 365, and divide by the days until payday. On $200, the gap widens: EarnIn charges $8.99 for Lightning Speed in most states, and Payactiv charges $3.49 to a debit card.
What each costs in a year
The CFPB’s July 2024 Data Spotlight found that the average worker made 27 earned wage transactions a year. The average employer-partnered transfer ran $106. At that pace, here’s what instant delivery costs on each:
- Payactiv, free paths only: $0.
- Payactiv, $2.49 to its card without the deposit: $67.23 a year.
- Payactiv, $3.49 to a debit card: $94.23 a year.
- EarnIn, standard speed with no tip: $0.
- EarnIn Lightning Speed at $5.99 in most states: $161.73 a year.
- EarnIn Lightning Speed at $6.99 in Colorado or Wisconsin: $188.73 a year.
Both free paths cost $0 a year. If you plan two days ahead, the fee comparison disappears, and repayment becomes the bigger difference.
Repayment: your paycheck vs your bank account
Your employer repays Payactiv through a payroll deduction before your paycheck reaches you. EarnIn debits your bank account after your pay lands. That difference decides who carries the risk when payday goes wrong.
With Payactiv, your employer deducts what you accessed, plus any fee. Payactiv says the amount “appears as a line item on your pay stub,” on its earned wage access page. Payactiv collects through payroll, not from your bank account, so repayment can’t overdraw your checking. Payactiv doesn’t publish what happens if your paycheck comes up short of what you took.
EarnIn customers repay differently. In its repayment article, EarnIn says it “will automatically debit your linked bank account for the amount you transferred out, plus any optional tips or fees.” If you request a transfer after 10 a.m. ET on the day before payday, EarnIn typically debits on the payday after next. You can reschedule a debit by contacting EarnIn support by 8 a.m. PT at least one business day before the debit date. If your paycheck lands late or short, your own bank can charge an overdraft fee when EarnIn pulls its money back.
Regulators draw the same line. The CFPB’s December 2025 advisory opinion says “Covered EWA” isn’t credit under federal Truth in Lending rules, and Covered EWA requires a payroll deduction. The CFPB wrote that “a transfer to the provider from any of the consumer’s regular transaction accounts after the payment of wages into that account is not a payroll process deduction.” The CFPB added that its opinion doesn’t call other EWA products credit. Our guide on whether earned wage access is a loan explains the split.
Speed, weekends, and credit
EarnIn publishes a weekend schedule, and Payactiv doesn’t. EarnIn says Lightning Speed money “arrives within 30 minutes, even on weekends and holidays.” Standard transfers arrive in one to two business days, according to EarnIn’s transfer timing article. One step on EarnIn’s Cash Out page says one to three business days instead. Payactiv lists its card, debit card, Venmo, PayPal, and Walmart options as instant, and its free ACH as one to three business days.
Neither one checks your credit for early pay. EarnIn says Cash Out “won’t get reported to credit bureaus.” Its separate EarnIn Card does report to Equifax, TransUnion, and Experian. Payactiv’s card FAQ says its Visa card involves no credit check and doesn’t affect your credit.
Pros, cons, and the legal record
EarnIn’s biggest catches are its bank debit, its fees for speed, and two state lawsuits. Payactiv’s are its employer requirement, its “in most cases” limit, and its card exit fees.
The pros of each
| EarnIn pros | Payactiv pros |
|---|---|
| Works without your employer, for people with steady direct deposit | Lower instant fees: $2.49 to $3.49 |
| No subscription and no interest | Two $0 paths: ACH and its card with $200+ direct deposit |
| Standard transfers cost $0 | No tips, ever, on its own terms |
| Up to $200 a day of earnings you already earned | Repayment through payroll, so no bank debit |
| EarnIn doesn’t report Cash Out to credit bureaus | Free bill pay, saving tools, and financial counseling services |
| Published weekend timing for Lightning Speed | No cost to employers |
EarnIn’s catches
- EarnIn debits your bank account, so a late paycheck can trigger an overdraft fee from your bank.
- Lightning Speed costs up to $8.99 in most states and $9.99 in Colorado and Wisconsin.
- EarnIn prompts for optional tips in most states.
- Extra same-day transfers past your Daily Max require Lightning Speed on your previous transfer.
- Colorado’s attorney general sued EarnIn on August 27, 2026, calling Cash Out illegal high-cost lending. The AG says EarnIn made more than 3.1 million loans to 56,778 Coloradans from January 2023 to July 2025. The AG also says EarnIn collected more than $16 million in tips and Lightning Speed fees. These are allegations, and the case is pending.
- D.C.’s attorney general sued EarnIn on November 19, 2024. EarnIn’s counsel says a court dismissed most claims in May 2025, and a consumer group’s tracker still lists the case as active.
Payactiv’s catches
- Your employer has to offer Payactiv, and your employer picks the provider.
- Payactiv’s pricing page says only “a portion” of earned wages, and its get-started FAQ gives 50% and $500 “in most cases.”
- The free instant path requires routing $200 of each paycheck to the Payactiv Card.
- The card charges $2.95 to move money out through digital wallets, linked debit cards, or third-party banking apps.
- Payactiv’s pricing page says fees “may vary by program” and location.
- Payactiv doesn’t publish a rule for a paycheck that comes up short.
On the regulatory side, the CFPB issued Payactiv an approval order in December 2020 and ended it in June 2022 at Payactiv’s request. We found no attorney general lawsuit against Payactiv on official sources. Payactiv lists NMLS ID 2591928 and a Wisconsin earned wage access license. EarnIn lists Activehours, Inc., NMLS #2535570. Our EarnIn review and Payactiv review cover each record in full.
Payactiv vs EarnIn: which should you use?
Use EarnIn if your employer doesn’t offer earned wage access, and use Payactiv if your employer does, since Payactiv charges less and repays through payroll. Most workers never get to choose between the two.
Pick EarnIn if
- Your employer offers no earned wage access program.
- Your employer pays you by direct deposit on a steady weekly, biweekly, semi-monthly, or monthly schedule.
- You keep a cushion in checking, so a payday debit won’t overdraw your account.
- You can wait one to three business days for the free transfer and will set the tip to $0.
- You need up to $200 for a one-time gap.
If EarnIn fits, you can sign up for EarnIn, pick standard speed, and set the tip to $0 on your first Cash Out request. Our EarnIn review walks through the setup, and our list of apps like EarnIn compares other no-employer options.
Pick Payactiv if
- Your employer or payroll provider offers Payactiv, UKG Wallet, OnShift Wallet, Paychex Pay on Demand, or Paycor Wallet.
- You’ll send $200 of each paycheck to the Payactiv Card, or you can wait one to three business days for ACH.
- Your checking balance runs close to $0, so you’d rather repay through payroll than a bank debit.
- You need $500 or less a pay period.
Don’t stack the two. EarnIn lowers your Max when you use other cash advance apps, and every app you add takes another bite out of the same paycheck. If you reach for either app every pay period, the gap is in the budget, and a small emergency fund beats both. For more options, see apps like Payactiv and our guide to earned wage access without an employer.
Payactiv vs EarnIn FAQ
Payactiv vs EarnIn: the bottom line
If your employer offers Payactiv, Payactiv wins on cost and on repayment. You pay $3.49 or less for instant money, and your employer collects repayment through payroll instead of a bank debit. If your employer doesn’t offer Payactiv, EarnIn is the option you can use, and you pay nothing for its standard transfer with a $0 tip. Either way, take the free path when the bill can wait.
If your employer offers a different program, read our matchups of Payactiv vs Tapcheck, Payactiv vs ZayZoon, Payactiv vs Wisely, and Payactiv vs Paychex.
For the wider field, compare Payactiv vs DailyPay, the full best earned wage access apps roundup, and our earned wage access fees table.
Free guide
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
- Track your money with the tools that still work in 2026.
- The order to invest in, with the 2026 401(k) and IRA limits.
- Three ways to earn your first $100 on the side this month.
Bonus: The 7-day Personal Profitability Bootcamp, one short lesson in your inbox each day