
Personal financial statements are three reports that show your money the way a company shows its books. First, a personal balance sheet lists what you own and what you owe, and the difference is your net worth. Next, an income statement shows what you earned and spent over a month. Finally, a cash flow statement shows where your cash went, so you can build all three in an hour with a spreadsheet or a free tool.
Personal Profitability may earn a commission from partner links on this page, at no cost to you. Partners don’t decide what we recommend or where it ranks.
I worked as a corporate accountant and financial analyst for nearly a decade before I went full-time on my own business, and I’ve built a personal balance sheet every month since July 2008. I last updated this guide on October 31, 2026.
Why run your money like a business?
Good companies don’t guess how they’re doing. At the multibillion-dollar companies where I worked, we knew the revenue and costs behind every product and customer. Nobody wondered if a product line made money, because the monthly reports answered the question.
Your household works the same way. Think of “the business of you.” There you need enough income to cover your costs, with money left over for savings, investments, and some fun. These reports also show you if that’s happening, since they answer four questions: where your money comes from, where it goes, what you own, and what you owe.
| Statement | The question it answers | The number to watch |
|---|---|---|
| Personal balance sheet | What do I own and owe today? | Net worth, and whether it rises each month |
| Personal income statement | Did I earn more than I spent this month? | Net income, which must stay above zero |
| Personal cash flow statement | Where did my cash go? | Net change in cash |
Build a budget you'll keep this month
Get my free 2026 guide to picking categories, setting limits, automating your savings, and choosing a budgeting tool.
Step 1: Get your financial information in one place
Before you build any statement, gather every balance in one spot. You could pull a stack of paper statements, but I’d rather log in to one dashboard. I’ve used account aggregators since 2007, and my longtime favorite is the free Empower Personal Dashboard, formerly Personal Capital.
Once you link your bank, credit card, loan, and investment accounts, you can see every balance and recent transaction on one screen. You’ll also see your net worth and your spending by category, which covers most of the data you need below.
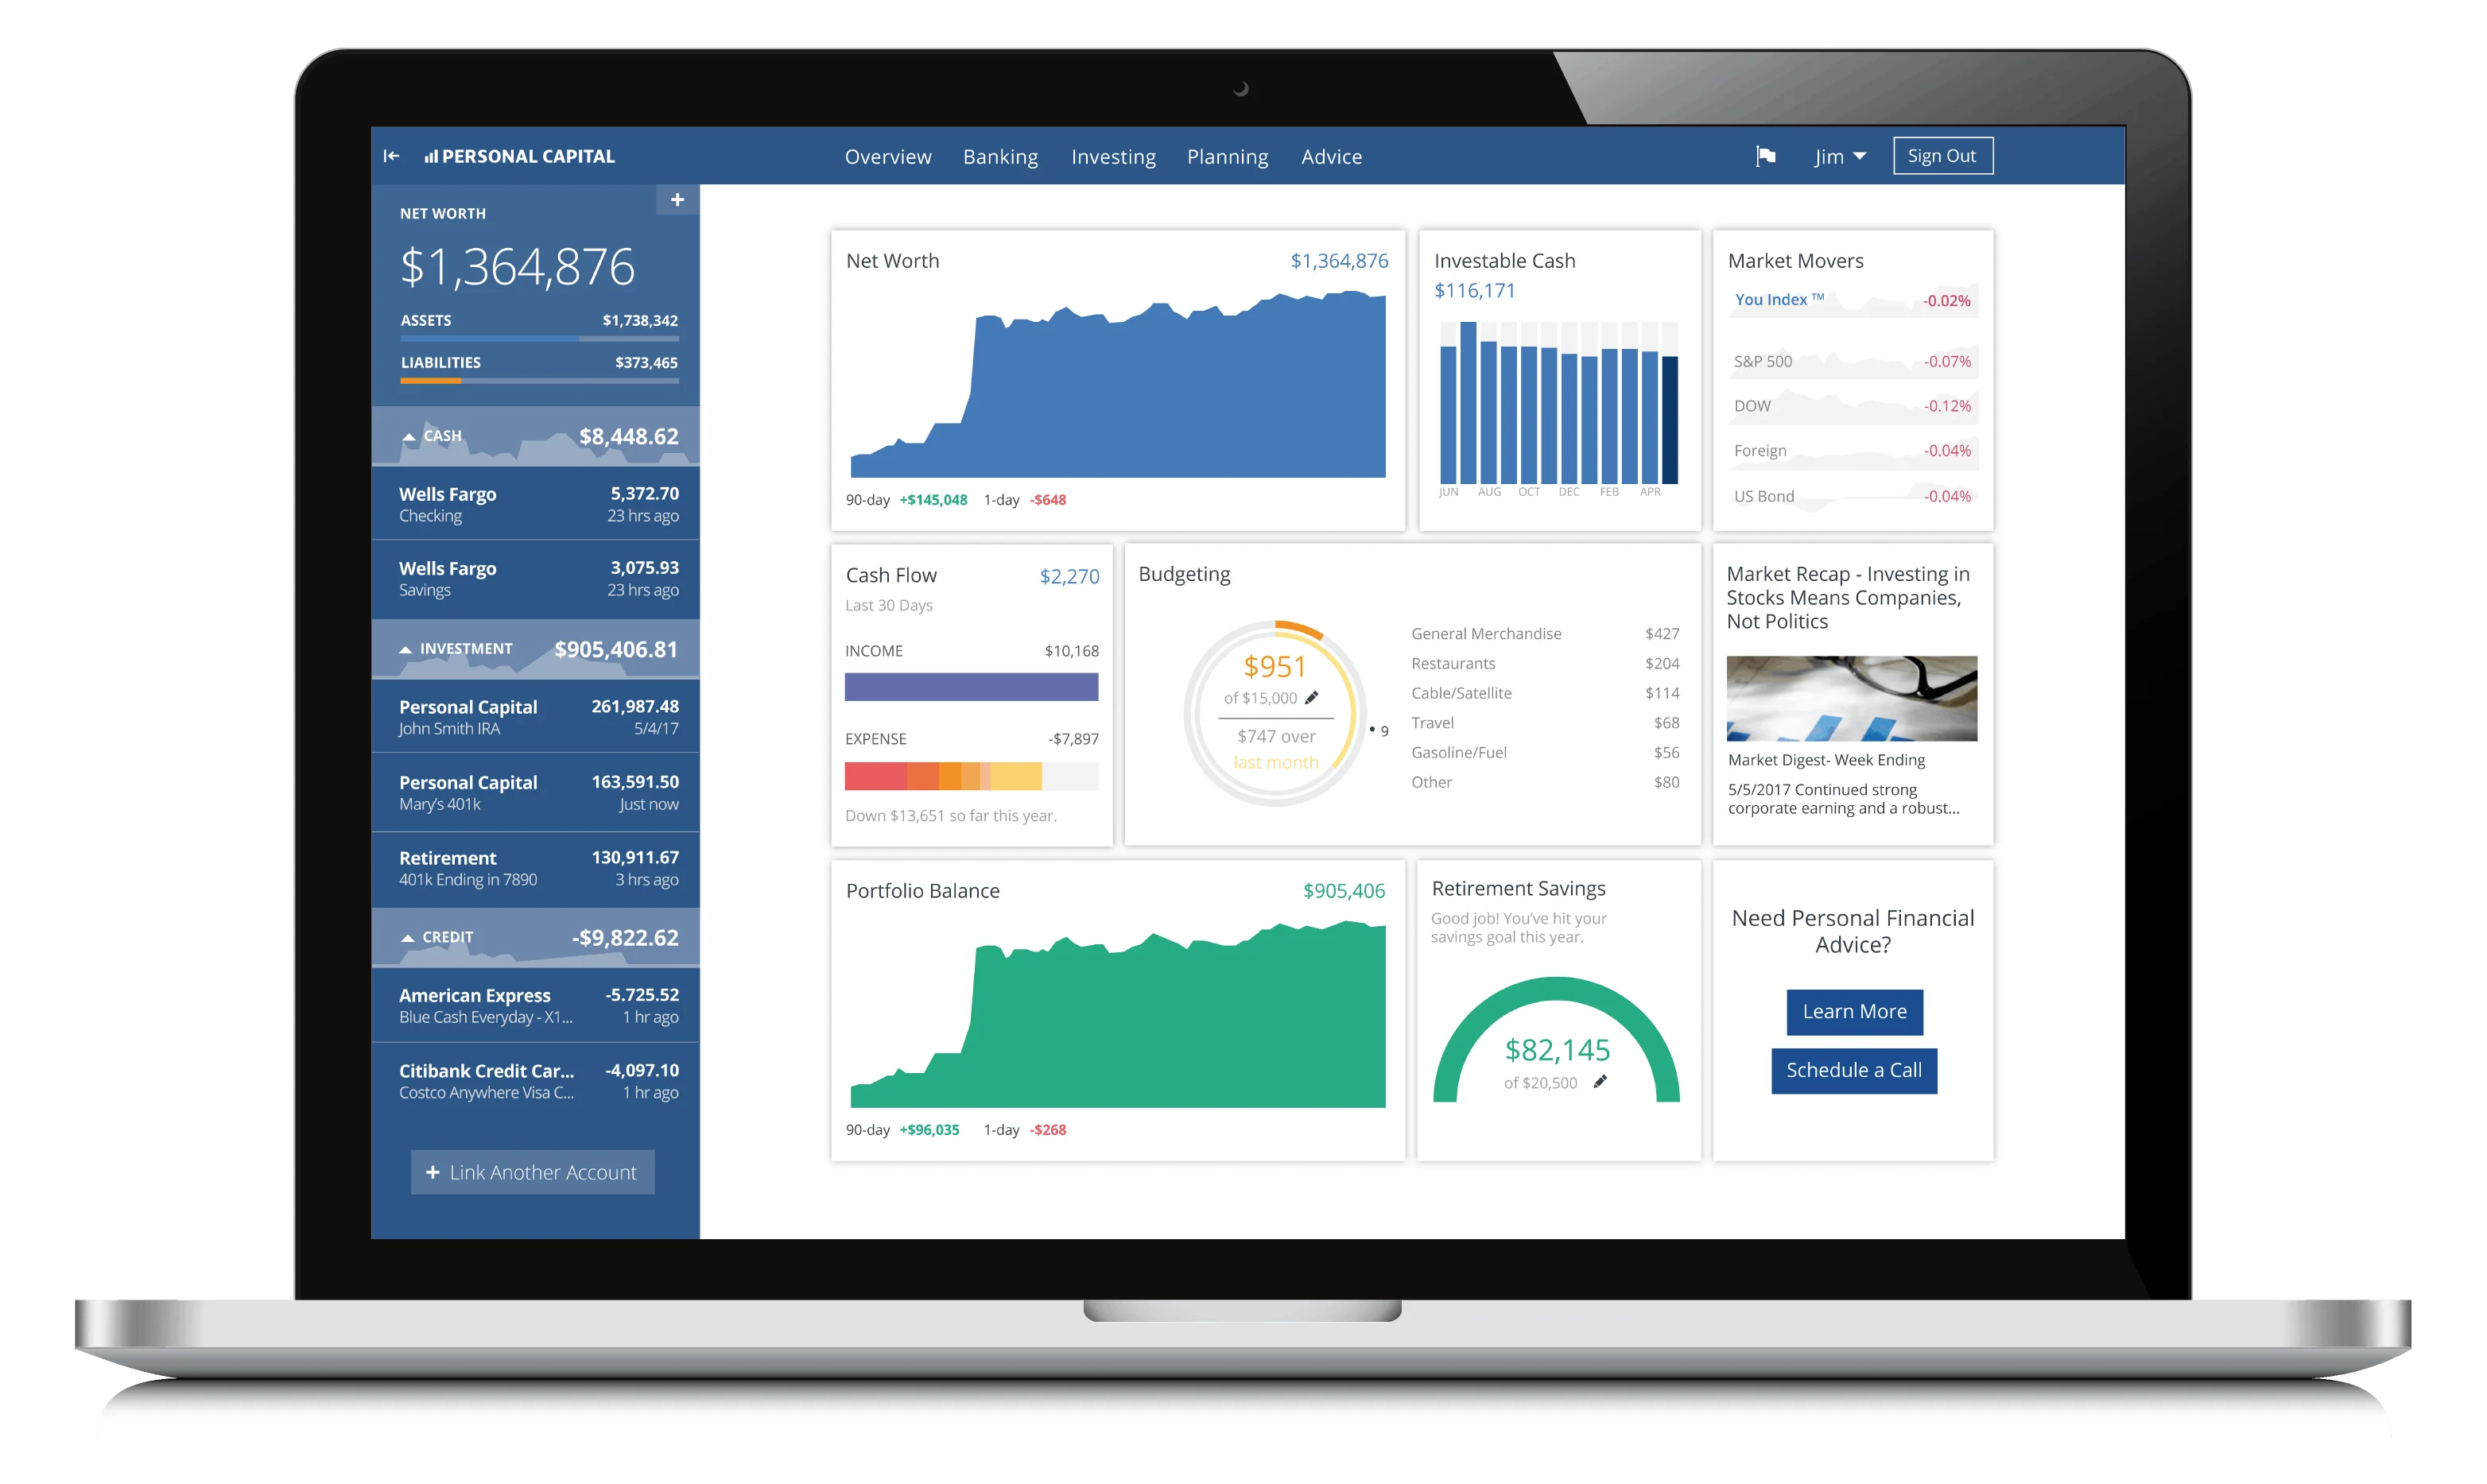
For me, the investment tools matter most. When I ran Empower’s fee analysis on my accounts, I found similar funds with lower fees and cut my investment costs by more than $300 a year. Over decades, that savings adds up to thousands of dollars in my retirement accounts.
Everything above is free. Still, if you link $100,000 or more in investments, Empower may call you about its paid advisory service, Personal Strategy, which costs 0.89% a year. You can say no and keep using the free dashboard.
Personal financial statements: the balance sheet
A personal balance sheet lists everything you own (assets) and everything you owe (liabilities) on one date. Then subtract your liabilities from your assets to get your net worth, which companies call shareholders’ equity.
Assets − Liabilities = Net worth
Your balance sheet is a snapshot, so the numbers change every day. Swipe a credit card, and your liabilities rise. Deposit a paycheck, and your assets rise. Pay a bill from checking, and your assets fall. Because of those swings, I take my snapshot on the same day each month.
A sample personal balance sheet
Here’s a balance sheet for a made-up household. Of course, the numbers are illustrations and don’t belong to anyone.
| Assets | Value | Liabilities | Balance |
|---|---|---|---|
| Checking | $4,500 | Credit card (paid in full monthly) | $1,200 |
| Savings (emergency fund) | $15,000 | Car loan | $9,500 |
| 401(k) | $85,000 | Student loans | $14,000 |
| Roth IRA | $32,000 | Mortgage | $310,000 |
| Brokerage account | $12,000 | ||
| Home | $425,000 | ||
| Car | $18,000 | ||
| Total assets | $591,500 | Total liabilities | $334,700 |
| Net worth | $256,800 |
How to build your personal balance sheet
- List every account balance: checking, savings, retirement, brokerage, and HSA. You can pull each balance from your dashboard.
- Add your home at a fair market value. For my home, I use the estimate on Redfin.
- Add your cars at their private-party value. Then update the values once a year with Kelley Blue Book.
- Next, list every debt at today’s balance: credit cards, car loans, student loans, and your mortgage.
- Finally, subtract total liabilities from total assets, and write down the date.
Skip furniture, clothes, and electronics unless one item is worth thousands on resale. Those things lose value fast, so counting them inflates your net worth. For more on tracking the number over time, read our guides to growing your net worth.
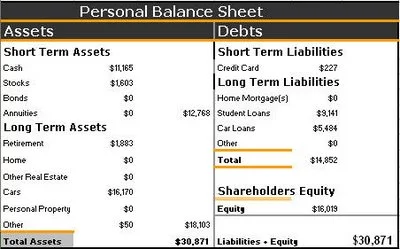
How to read your balance sheet
Your goal is a net worth that rises over time. Personal finance is a marathon, so don’t expect a jump overnight. Instead, watch the trend over a year.
A negative net worth is common, especially right after school. Student loans and other debt can outweigh everything you own for years. In that case, flipping your number from red to black should become your top priority. Spend less than you earn, put the gap toward debt and savings, and your net worth will climb.
Analysts also use ratios to judge a company’s health, and two of them work for households:
- Quick ratio. Divide your cash by the bills and debt payments due in the next month. In the sample above, $19,500 in checking and savings divided by $3,810 in payments due this month (the card balance, plus the mortgage, car, and student loan payments) equals 5.1. A ratio of 1.0 means you’re living paycheck to paycheck, while anything below 1.0 means you can’t cover this month’s bills from cash.
- Debt-to-asset ratio. Divide total liabilities by total assets. The sample household’s ratio is $334,700 divided by $591,500, or 57%. You want that percentage to fall each year as you pay down debt and your investments grow.
Most companies measure the quick ratio over a year. For a household, I use one month, since most of us pay bills monthly and a big expense can change the picture fast.
The personal income statement
A personal income statement shows what you earned and spent over a set period, usually a month. Businesses call it a profit and loss statement, or P&L. I’ve run one every month for my own business for years, and the format also works at home.
| Sample monthly income statement | Amount |
|---|---|
| Salary (gross) | $7,500 |
| Side income | $500 |
| Total income | $8,000 |
| Taxes and payroll deductions | −$1,900 |
| 401(k) contribution | −$600 |
| Housing (mortgage, taxes, insurance) | −$2,100 |
| Transportation (car payment, gas, insurance) | −$650 |
| Groceries | −$700 |
| Health insurance | −$300 |
| Utilities | −$250 |
| Student loan | −$160 |
| Dining out and fun | −$500 |
| Everything else | −$340 |
| Net income | $500 |
Net income is what you keep after everything you earn and spend. There’s one rule: net income has to stay above zero. The bigger, the better. For example, the household saves $600 into the 401(k) plus $500 of net income, a savings rate of about 14% of gross pay.
I list savings as an expense line, the way the 401(k) appears above, so I pay myself before the fun money. Each month’s net income then rolls onto your balance sheet as more cash or investments.
You don’t have to build the statement by hand, though. Once you link your accounts, Empower’s cash flow view lets you see income and spending by category.
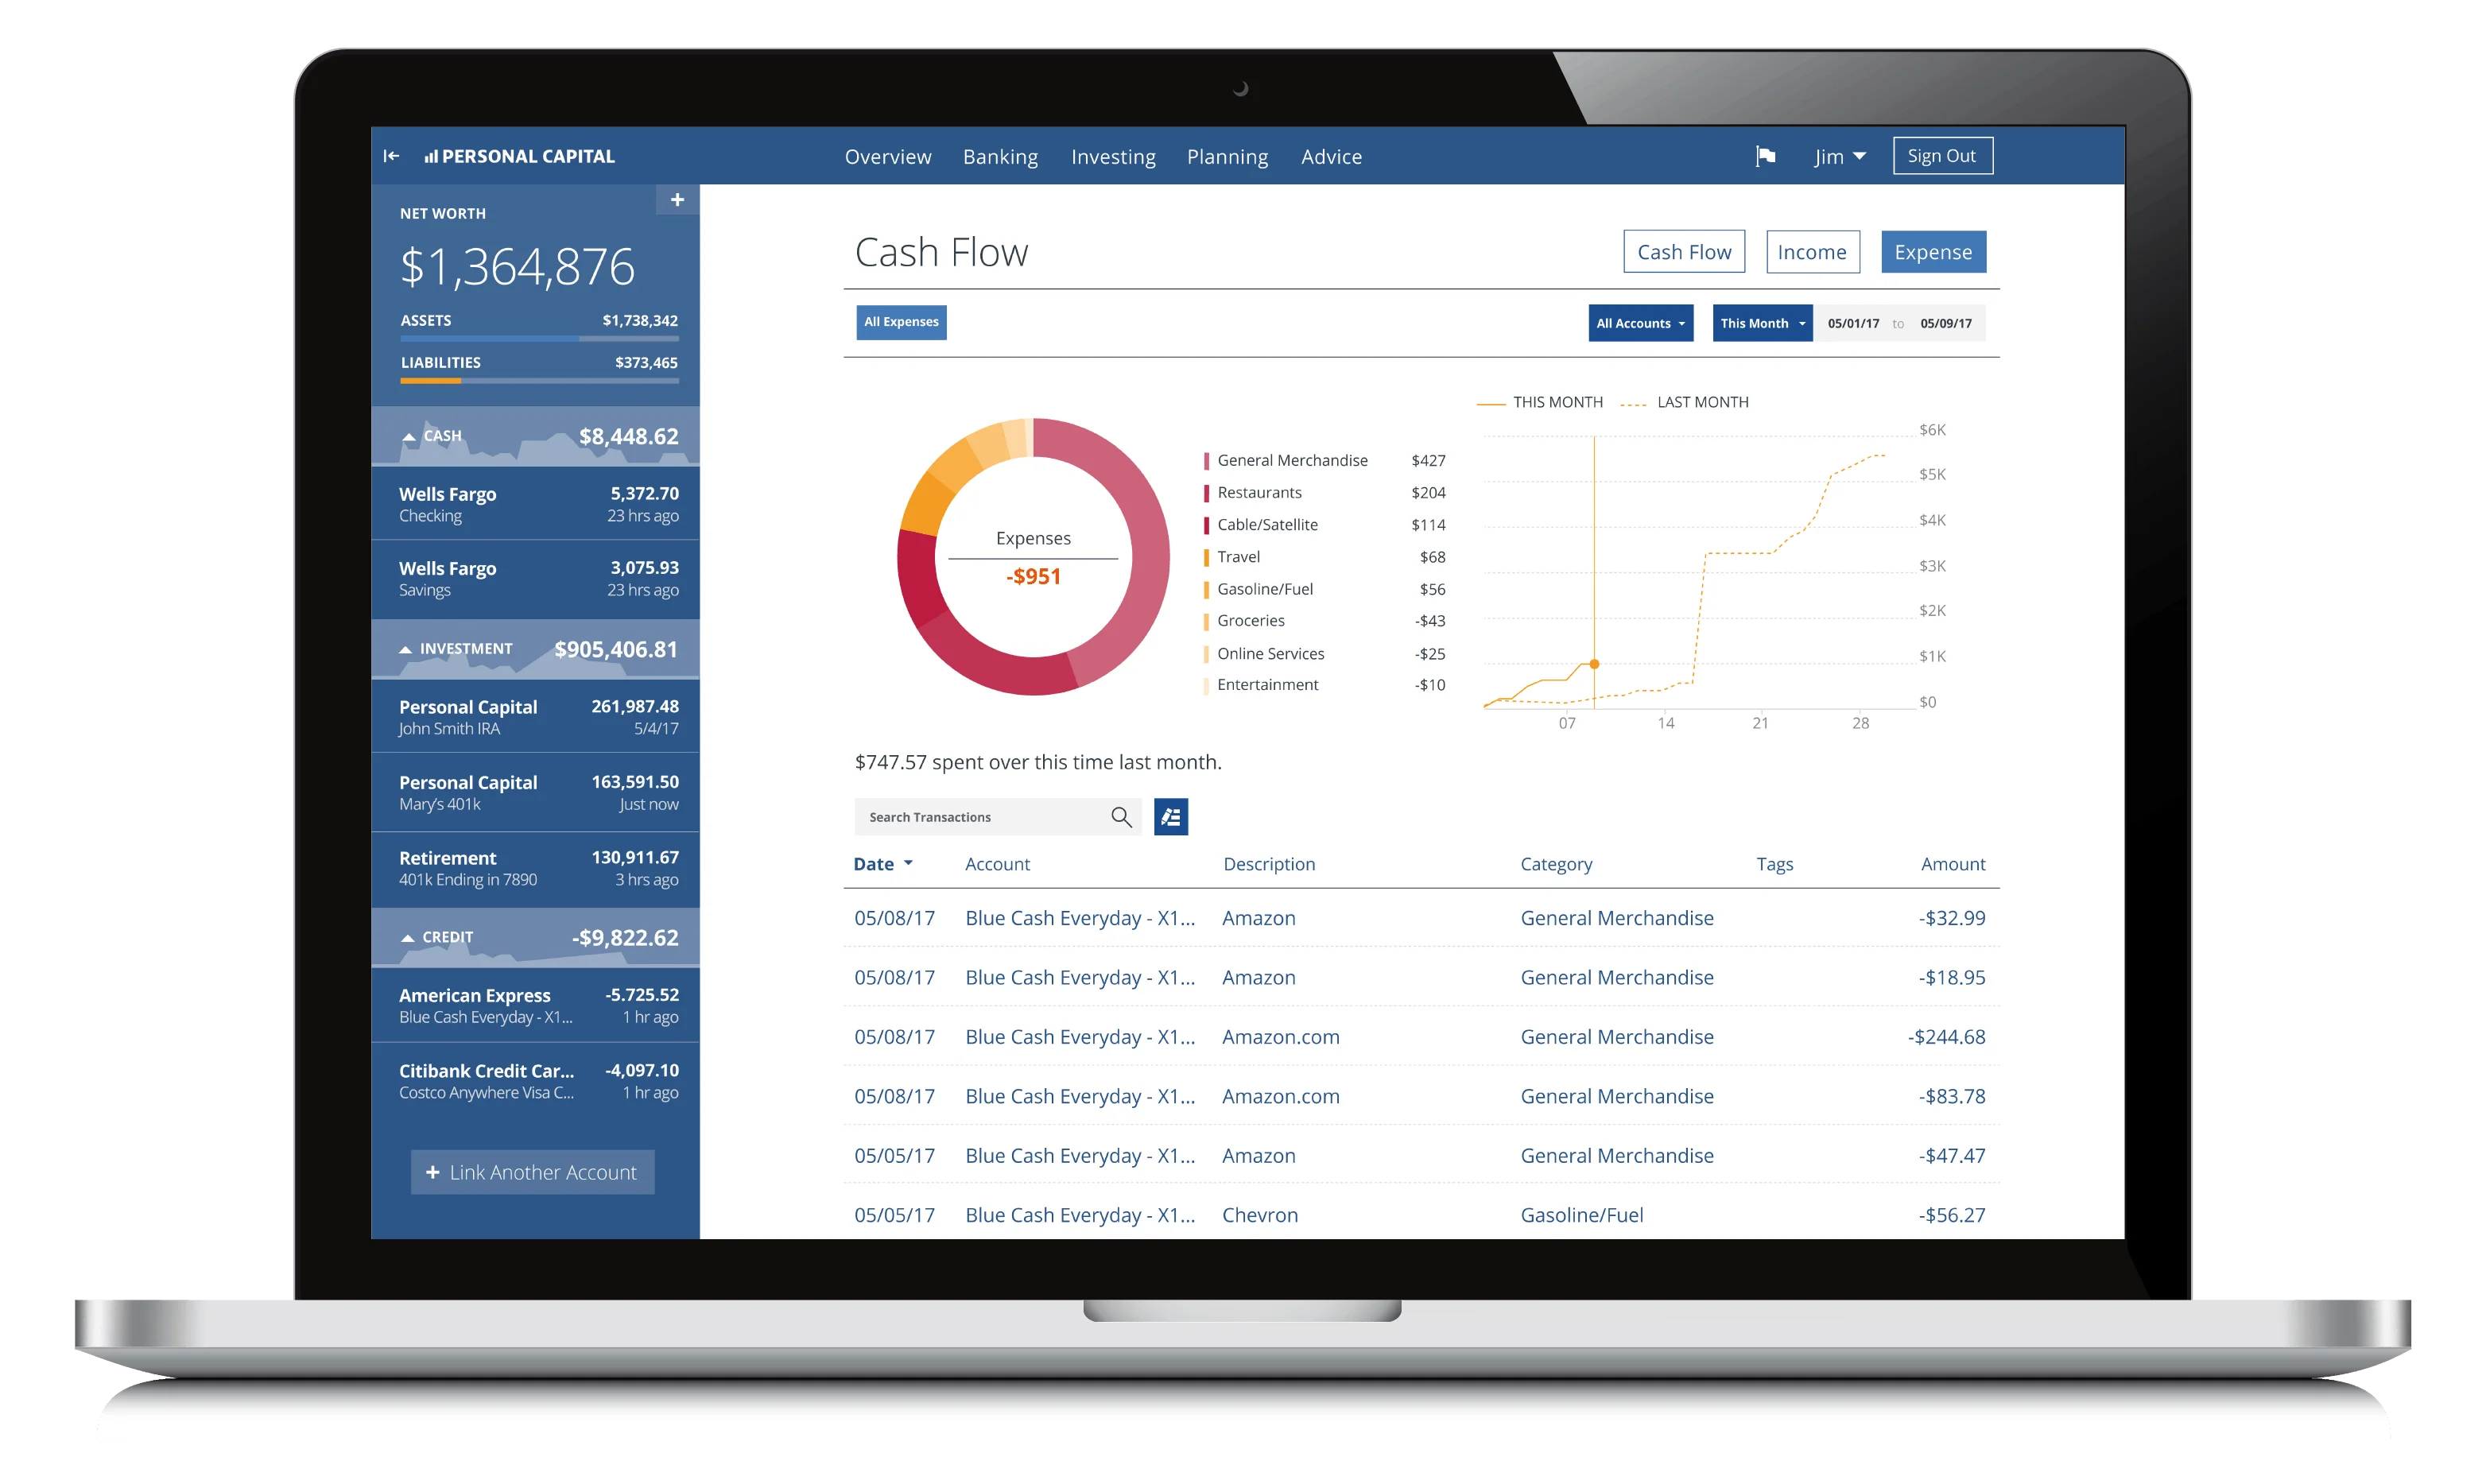
Then use the categories to find savings. Specifically, look for a line you can cut, a subscription you forgot, or a bill you can negotiate. Our complete beginner guide to budgeting walks through setting limits for each category.
The personal cash flow statement
A personal cash flow statement tracks the cash that moved in and out of your checking and savings accounts during the month. It looks like the income statement, but with one big difference. You’ll see where the cash went, including debt payments and investments that never appear as expenses.
Companies sort cash flow into three groups: operating, investing, and financing. I use the same three groups for a household:
| Sample monthly cash flow | Amount |
|---|---|
| Take-home pay and side income deposited | $5,500 |
| Living costs (groceries, utilities, gas, insurance, fun, other) | −$2,390 |
| Cash from living (operating) | $3,110 |
| Mortgage, car loan, and student loan payments | −$2,610 |
| Cash for debt (financing) | −$2,610 |
| IRA contribution from checking | −$300 |
| Cash for investing | −$300 |
| Net change in cash | $200 |
The two statements also tie together. In the sample, the household’s $500 of net income went to $300 in the IRA and $200 of extra cash. Want the operating number high and the net change positive? Keep living costs low. A negative month is fine when you’re paying off debt fast or making a big investment, but too many negative months will drain your emergency fund.
What do your personal financial statements tell you?
With all three personal financial statements, you can see if you’re getting richer or poorer, and why. So read your statements in this order:
- Balance sheet: Check your net worth trend and your quick ratio. If you can’t cover next month’s bills from cash, fix the gap first.
- Income statement: Check net income. When the number is negative, you’re spending more than you make and need to cut costs or earn more.
- Cash flow statement: Check where your cash went. Then look at the financing line, because a big one means debt is eating your income.
Stock analysts grade companies with the return on assets and profit margin, and you can grade yourself the same way. Would an investor buy shares in your household? If not, look for ways to grow your income with your job or a side hustle, and cut the costs your income statement flags.
Frequently asked questions about personal financial statements
Build your first statement this month
Start with the balance sheet, because it takes the least work and gives you your net worth today. Link your accounts to the free Empower Personal Dashboard, add your home and car values, and write down the total. Next month, add an income statement and compare. Your money should help you live the life you want, so use these three reports to check your progress.
Free guide
Build a budget you'll keep this month
Get my free 2026 guide to picking categories, setting limits, automating your savings, and choosing a budgeting tool.
- Set category limits from what you spend now.
- Try envelope, zero-based, and one-line budgets.
- Compare free and paid budgeting tools for 2026.
Bonus: The 30-Day Money Reset, a one-task-a-day plan to put your budget to work