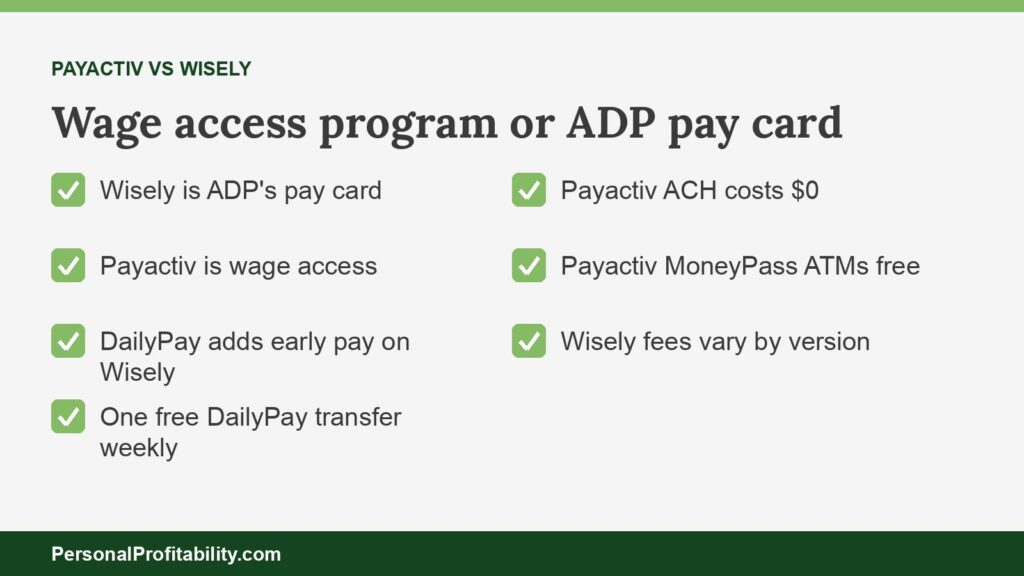
Payactiv vs Wisely pits wage access against a pay card: Payactiv lets you reach wages before payday for $0 to $3.49. Wisely by ADP delivers your paycheck up to two days early. Wisely users get early wages through ADP partners such as DailyPay. Our guide to earned wage access explains the difference.
Eric Rosenberg, who founded Personal Profitability, wrote for Payactiv as a freelancer and later worked there as a marketing manager, until June 2026. Nobody at Payactiv reviewed this page. We held Payactiv to its own published fees and terms, the same standard we used for every other company here.
Personal Profitability may earn a commission from partner links on this page, at no cost to you. Partners don’t decide what we recommend or where it ranks. Fees and terms are each company’s as of 2026-10-31. Confirm them on the company’s site before you apply.
Last checked: October 31, 2026, against each company’s own fee and terms pages.
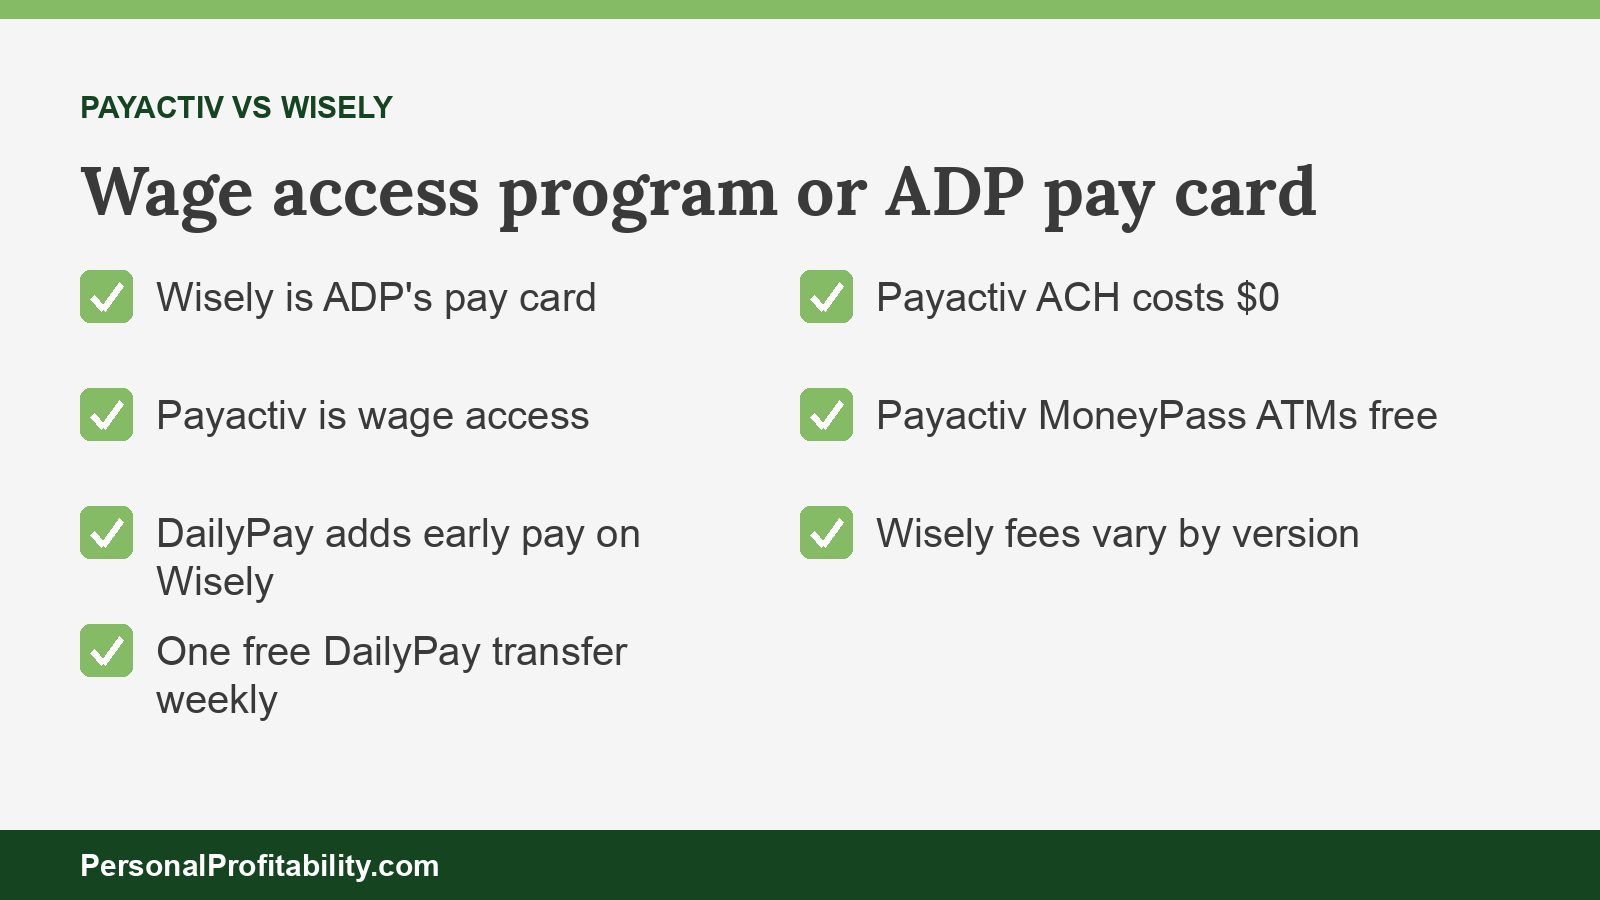
Payactiv vs Wisely at a glance
ADP employers use the Wisely card and app to pay workers. Payactiv runs a wage access program with its own card. So the fair comparison runs card against card, and Payactiv’s wage access against the programs ADP offers Wisely users.
| Feature | Wisely by ADP | Payactiv |
|---|---|---|
| What it is | Wisely Pay payroll card and Wisely Direct card, run in the myWisely app | Earned wage access program plus the Payactiv Visa Prepaid Card |
| Who offers each | Employers that pay through ADP | Employers and payroll partners that offer Payactiv |
| Early wages before payday | Through ADP partners, such as DailyPay Preferred for Wisely | Part of Payactiv. “A portion” of earned wages (pricing page), up to 50% and $500 a pay period “in most cases” (get-started FAQ) |
| Free early-wage option | One no-fee instant DailyPay transfer a week, if your employer uses DailyPay Preferred | ACH in 1–3 business days, or instant to its card with $200+ direct deposit per pay period |
| Paid early-wage option | $3.49 per extra instant DailyPay transfer | $2.49 to $3.49 per instant transfer |
| Early direct deposit | Up to 2 days early | Up to 2 days early to its card |
| Monthly fee | $0 | $0 |
| ATM cash | Varies by card version. One filed version: one free in-network withdrawal a week, then $3.25. | $0 at MoneyPass ATMs, $2.95 out of network |
| Overdraft | None. Prepaid, so you can’t overdraw. | None. No overdraft or credit feature. |
| Issuing bank | Fifth Third Bank, N.A., Member FDIC | Central Bank of Kansas City, Member FDIC |
| Where the full fee list lives | Inside the myWisely app or mywisely.com, after you log in | Public, on payactiv.com/card411 |
Fees and terms verified 2026-10-31 on Wisely’s fees page, ADP’s DailyPay Preferred for Wisely listing, the CFPB’s prepaid agreements database, Payactiv’s pricing page, and Payactiv’s card411 page.
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
What Wisely is, and what Payactiv is
Wisely is ADP’s prepaid card program for your paycheck. Payactiv is a company that lets you reach earned wages before payday. You get Wisely from an ADP employer, and you get Payactiv’s wage access from an employer that offers Payactiv.
Wisely by ADP
ADP runs two Wisely cards. Fifth Third Bank issues both Wisely cards: the Wisely Pay card, on Visa or Mastercard, and the Wisely Direct Mastercard. ADP manages the program as a registered ISO of Fifth Third. You manage either card in the myWisely app. Wisely lists early direct deposit up to two days early, bill pay through Papaya, and savings envelopes. You can move money to up to three outside bank accounts in one to three days. You can also send money to an outside debit card in minutes. Wisely members can swap up to $1,000 a day by peer transfer at no cost.
Wisely Pay is a payroll card, and you can decline the card. The short-form fee disclosure we read on a filed Wisely Pay agreement opens with “You do not have to accept this payroll card. Ask your employer about other ways to receive your wages.”
Payactiv
Payactiv says, “Earned Wage Access requires employer participation.” Payactiv pulls your hours from your employer, shows the wages you’ve earned, and lets you move part of that balance before payday. Your employer deducts what you took from your next paycheck. The Payactiv Visa Prepaid Card is optional. Payactiv says anyone in the US who is 18 or older can apply, with no bank account and no credit check. Our guide to how Payactiv works covers the steps.
Does Wisely have earned wage access?
Wisely users can get early wages through ADP’s partners, mainly DailyPay. Wisely itself doesn’t publish a current earned wage access page. ADP’s November 2022 release said Wisely offered earned wage access “in partnership with DailyPay” at “no cost,” with opt-in required.
We checked Wisely’s site on October 31, 2026. Wisely’s earned wage access FAQ pages loaded with no questions or answers. Its “What is Earned Wage Access” page returned a 404 error. So we can’t confirm from Wisely’s own pages that the feature still runs inside myWisely. Ask your payroll team before you count on early wages through myWisely.
DailyPay Preferred for Wisely
ADP’s Marketplace lists one wage access program built around the Wisely card: DailyPay Preferred for Wisely. If your employer is a DailyPay Preferred client and pays you on the Wisely card, you “can receive one no-fee instant on-demand pay transfer per week,” according to ADP’s listing. You qualify by linking your Wisely card as your direct deposit destination. ADP’s listing says your full earnings have to go to your Wisely account. Extra instant transfers cost $3.49, and next-business-day ACH transfers cost $0. ADP’s listing says eligible employees can reach up to 100% of earned wages, and “additional fee-free transactions may be available in some states.”
Two caveats from the same listing. “The services are provided by an independent third party and not provided by ADP,” and “ADP receives a commission if you make a purchase from a listing.” DailyPay’s own fees page lists $3.49 instant and $0 in one to three business days. DailyPay adds that your employer’s contract sets the instant fee. Our DailyPay review covers DailyPay in full.
Other ADP partners, including Payactiv
ADP also lists other wage access providers on its Marketplace, and each one sets its own fees. Payactiv’s ADP Workforce Now listing names Wisely as one place employees can send wages, along with bank transfer, debit card, and Walmart cash pickup. Tapcheck and ZayZoon have ADP listings too. Our Payactiv vs Tapcheck and Payactiv vs ZayZoon pages compare those programs.
Early wage fees: DailyPay on Wisely vs Payactiv
Both routes offer a free option, and both charge $3.49 for most paid instant transfers. The difference is the rule you follow to stay free.
- DailyPay Preferred for Wisely: one free instant transfer a week if your whole paycheck lands on your Wisely card. Free next-business-day ACH. $3.49 for each extra instant transfer.
- Payactiv: free ACH in one to three business days. Free instant transfers to the Payactiv Card in a pay period with a $200 direct deposit to the card. Without the deposit, a $2.49 “load fee.” $3.24 to Cash App in an Early Adopter Program. $3.49 to other cards, Venmo, PayPal, or Walmart Cash Pickup.
Payactiv says “fees and available transfer options may vary by program.” Our Payactiv fees page has every charge. Our Payactiv vs DailyPay page compares the two wage access programs head to head.
Can you send Payactiv money to a Wisely card?
Yes, Payactiv’s ADP listing names Wisely as a payout option. By Payactiv’s published fee table, an instant transfer to a Wisely card counts as a non-Payactiv payroll card, so you’d pay $3.49. An ACH transfer to your Wisely account and routing number would cost $0 and take one to three business days. Check the options in the Payactiv app before you rely on either route.
Card fees: Wisely vs the Payactiv Card
Payactiv publishes one card fee schedule for everyone, and Wisely’s fees depend on your employer’s card version. Neither card charges a monthly fee or allows overdrafts.
Wisely’s card fees
Wisely says it charges no minimum balance, monthly, or annual fees. On its fees page, Wisely also lists no fees for early direct deposit, bill pay, savings envelopes, purchases, or card declines. Wisely says “inactivity fees may be assessed after a certain period of inactivity.” For everything else, Wisely tells you to log in to see your cardholder agreement and “List of Fees.” Wisely doesn’t post one public schedule.
The CFPB’s prepaid database holds many Wisely Pay agreements, one per program version, with Fifth Third as issuer and ADP as program manager. We read one the database lists as active, version WPA1070 from August 2022:
| Wisely Pay WPA1070 fee | Amount |
|---|---|
| Monthly fee and purchases | $0 |
| In-network ATM withdrawal | One free a week, then $3.25 |
| Out-of-network ATM withdrawal | $3.25, plus any ATM owner fee |
| ATM balance inquiry or decline | $0 |
| Cash reload at Western Union or Green Dot | $3.95 or $5.95 |
| Expedited mobile check deposit | 1% for payroll and government checks, 5% for others, $5 minimum |
| Monthly paper statement | $1.50 |
| International transaction | 3% |
| Lost card replacement | One free a year, then $6 |
Your version may differ. Wisely’s benefits page promises no fees “for in-network ATMs.” The filed WPA1070 schedule allows one free in-network withdrawal a week. Read your own List of Fees in the myWisely app.
Payactiv Card fees
Payactiv charges $0 for purchases, the monthly fee, and withdrawals at its 37,000 MoneyPass ATMs, according to its card fee schedule. An out-of-network ATM costs $2.95, and an ATM balance inquiry costs $0.50. Payactiv charges $2.95 to move money out through digital wallets, linked debit cards, or banking apps. International transactions cost 3%. A Green Dot cash reload costs up to $5.95. Payactiv says transfers from the card to a linked bank account are free and take one to three business days. The card holds up to $15,000.
What the card fees cost in a year
Say you pull cash twice a week. On the WPA1070 Wisely version, the second weekly withdrawal costs $3.25, or $169 a year. On the Payactiv Card at a MoneyPass ATM, both cost $0. Use an out-of-network ATM with either card, and you pay $3.25 or $2.95 before the ATM owner’s fee.
What early pay costs over a year
A weekly early-pay habit costs $0 on either route if you follow the free-path rules, and up to $181.48 if you don’t. The table shows one $100 transfer a week, with the APR equivalent for a seven-day wait.
| $100 a week, 7 days to payday | Fee | APR equivalent | 52 weeks |
|---|---|---|---|
| DailyPay Preferred, one weekly free transfer to Wisely | $0 | 0% | $0 |
| Payactiv ACH, or its card with $200+ deposit | $0 | 0% | $0 |
| Payactiv to its card without the deposit | $2.49 | 130% | $129.48 |
| Payactiv instant to a Wisely or debit card | $3.49 | 182% | $181.48 |
| Second DailyPay instant transfer that week | $3.49 | 182% | $181.48 |
To get the APR equivalent, divide the fee by the amount, multiply by 365, and divide by the days until payday. The CFPB’s July 2024 Data Spotlight found that workers used earned wage access about 27 times a year. The average transfer ran $106, and the average fee $3.18. If you’re pulling pay early every week, the gap sits in the budget. A starter emergency fund beats every row in the table.
The catch with each
Wisely’s catch is fee transparency. You see your card’s full fee list only after you log in to myWisely. Payactiv’s catch is that both of its free paths come with conditions.
Wisely’s catches
- Wisely’s card fees vary by employer program, and Wisely doesn’t post a public schedule.
- Wisely’s own site no longer explains its earned wage access feature.
- DailyPay’s free weekly transfer requires your whole paycheck on the Wisely card and an employer on DailyPay Preferred.
- Some Wisely versions limit free in-network ATM withdrawals.
Payactiv’s catches
- You need an employer that offers Payactiv for early wages.
- The free instant path requires a $200 direct deposit to the Payactiv Card every pay period.
- Payactiv charges $2.95 to move card money through digital wallets, linked cards, or banking apps.
- Payactiv’s pricing page says only “a portion” of earned wages. Its get-started FAQ gives 50% and $500 “in most cases.”
Payactiv vs Wisely: which should you use?
Your employer makes most of the choice. Use the card your paycheck already lands on, add the wage access program your employer offers, and take the free option every time.
Stick with Wisely if
- Your employer pays through ADP and offers DailyPay Preferred for Wisely.
- You need early wages about once a week, so the free weekly transfer covers you.
- Your Wisely version lists free ATM withdrawals at machines near you.
- You like getting your full paycheck up to two days early.
Pick Payactiv if
- Your employer, Paychex, Paycor, UKG Wallet, or ADP Workforce Now plan offers Payactiv.
- You can wait one to three business days for a $0 ACH transfer.
- You’ll route $200 of each paycheck to the Payactiv Card for free instant transfers.
- You want a card with free MoneyPass ATMs and a public fee schedule.
Our Payactiv review gives the full verdict, and our list of apps like DailyPay covers other options for ADP workers.
Payactiv vs Wisely FAQ
Payactiv vs Wisely: the bottom line
Wisely and Payactiv do different jobs. Wisely gets your paycheck onto a card up to two days early. ADP partners such as DailyPay add early wages on top. Payactiv gives you early wages directly, with a $0 ACH path and a card with a public fee schedule. If your employer offers DailyPay Preferred for Wisely, use the one free weekly transfer and skip the paid ones. If your employer offers Payactiv, take the ACH transfer when the bill can wait.
For more comparisons, read Payactiv vs Paychex, Payactiv vs EarnIn, and our earned wage access fees table.
Free guide
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
- Track your money with the tools that still work in 2026.
- The order to invest in, with the 2026 401(k) and IRA limits.
- Three ways to earn your first $100 on the side this month.
Bonus: The 7-day Personal Profitability Bootcamp, one short lesson in your inbox each day