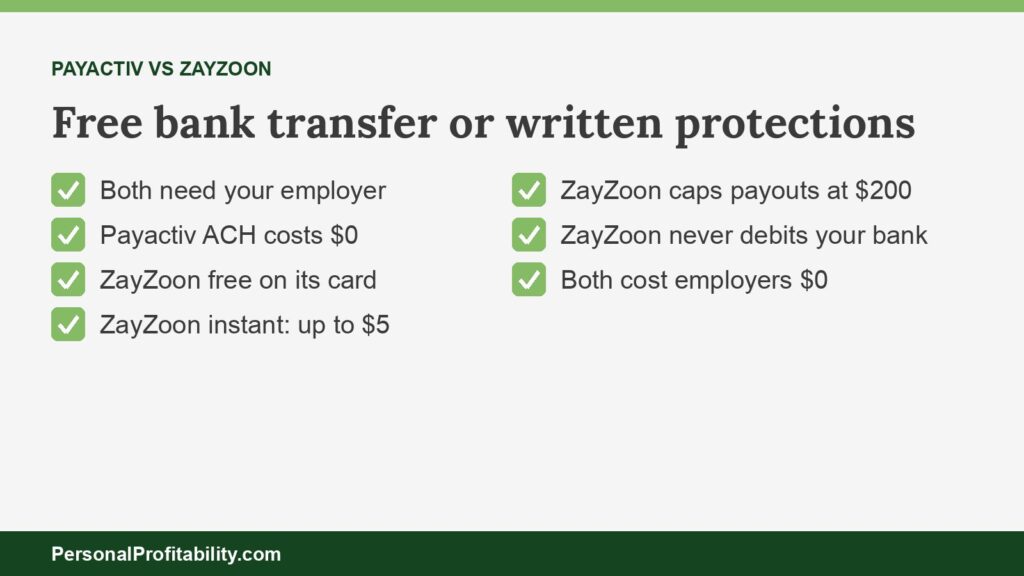
Payactiv vs ZayZoon comes down to where the free money lands. Payactiv sends a $0 bank transfer and caps its main instant fees at $3.49. ZayZoon is free only on its own card or gift cards and charges up to $5 otherwise. Both need your employer. Our guide to earned wage access covers the basics.
Eric Rosenberg, who founded Personal Profitability, wrote for Payactiv as a freelancer and later worked there as a marketing manager, until June 2026. Nobody at Payactiv reviewed this page. We held Payactiv to its own published fees and terms, the same standard we used for every other company here.
Personal Profitability may earn a commission from partner links on this page, at no cost to you. Partners don’t decide what we recommend or where it ranks. Fees and terms are each company’s as of 2026-10-31. Confirm them on the company’s site before you apply.
Last checked: October 31, 2026, against each company’s own fee and terms pages.
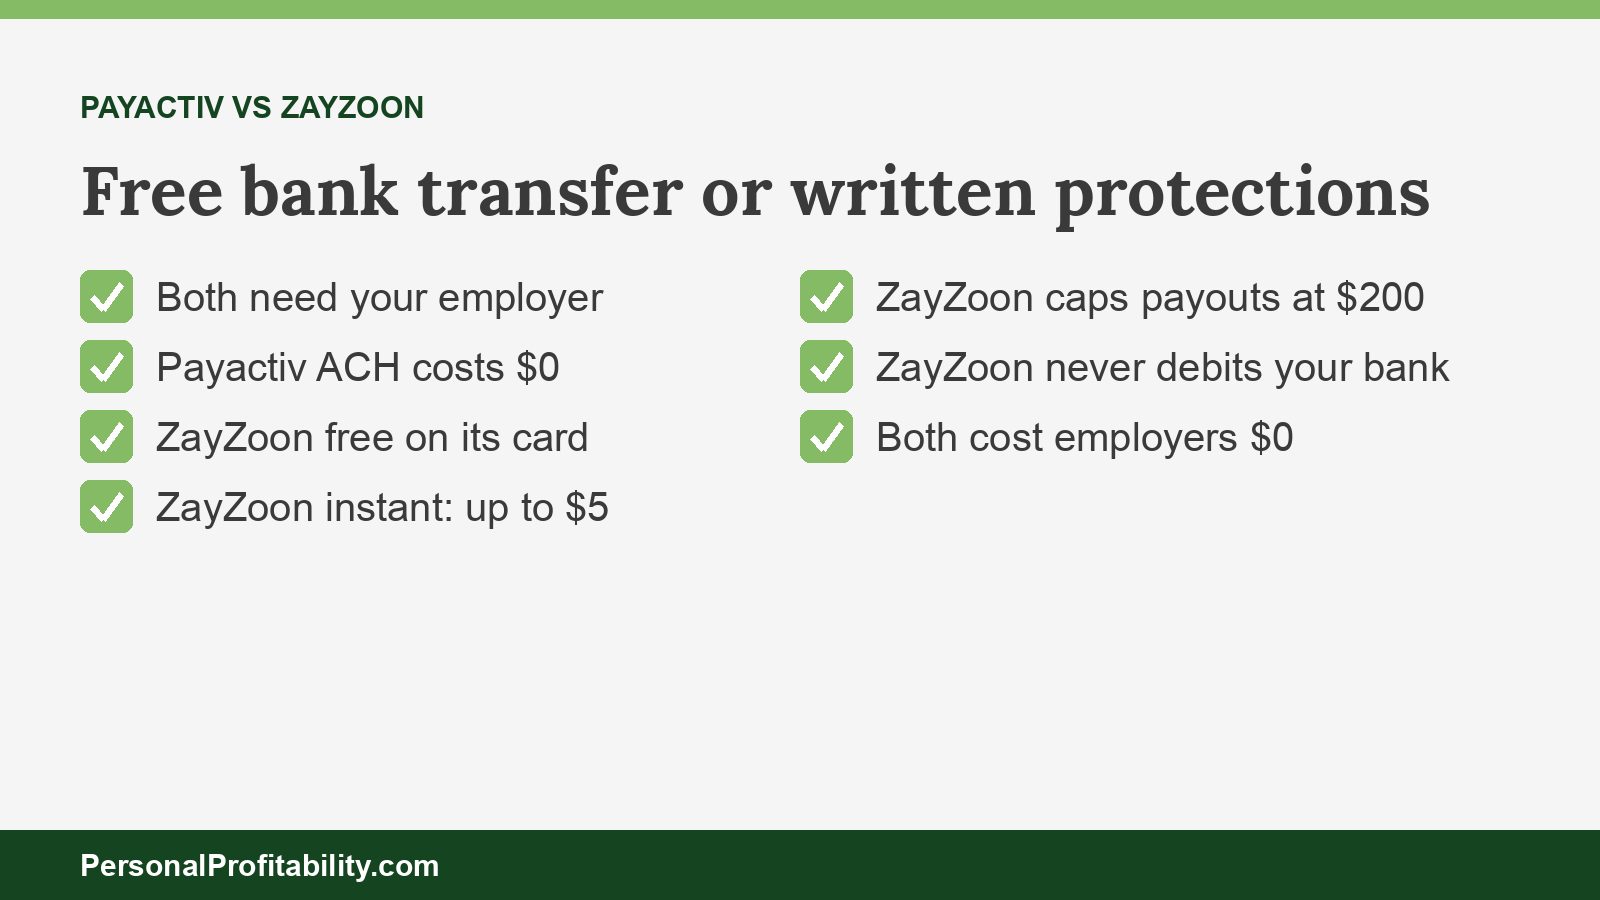
Payactiv vs ZayZoon at a glance
ZayZoon writes stronger worker protections into its terms, and Payactiv gives you more free ways to get cash. We built every row from each company’s terms, pricing page, or help center.
| Feature | ZayZoon | Payactiv |
|---|---|---|
| Needs your employer? | Yes | Yes |
| Free path | ZayZoon Visa Prepaid Card or Boost gift cards | ACH to any bank in 1–3 business days, or instant to its Visa card with $200+ direct deposit per pay period |
| Instant fee | Up to $5 per Near Instant transfer, including Venmo and Zelle. Connecticut: $4, one a pay period. | $2.49 to its card without the deposit, $3.24 to Cash App (early adopters), $3.49 to other cards, Venmo, PayPal, or Walmart |
| How much | Up to 50% of earnings, $200 per payout, one payout a day, about $1,000 a pay period | “A portion” of earned wages (pricing page). Up to 50% and $500 a pay period “in most cases,” and up to $1,000 a request with card direct deposit (get-started FAQ) |
| Tips or subscription | Neither. ZayZoon “does not accept tips.” | “Never any tips,” no subscription listed |
| Repayment | From your next paycheck. ZayZoon won’t debit your bank. | From your next paycheck, as a pay stub line item |
| If payroll comes up short | Nonrecourse, except for fraud | Not published |
| Card ATM fee | $2.50 per withdrawal | $0 at MoneyPass ATMs, $2.95 out of network |
| Credit check | None | None for its Visa card |
| Cost to employers | “Doesn’t cost you a cent” | $0 |
Fees and terms verified 2026-10-31 on ZayZoon’s USA EWA Terms of Service (effective May 15, 2026), ZayZoon’s payout limits article, ZayZoon’s card FAQ, Payactiv’s pricing page, and Payactiv’s get-started FAQ.
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
How Payactiv and ZayZoon work
Both work through your employer’s payroll. Your employer signs up, you see the wages you’ve earned, and your employer repays the provider on payday. Neither company lets you sign up without a participating employer.
ZayZoon tells employees to wait until “your employer is up and running with ZayZoon,” then download the app. ZayZoon says your wages become available “as soon as they’re reported to your payroll provider.” Under its terms, your employer sends ZayZoon “the Payout plus the Processing Fee, if applicable,” from your next paycheck. ZayZoon sells mostly to small and midsize businesses through payroll companies, and it says it was “established in 2014.”
Payactiv says, “Earned Wage Access requires employer participation.” Payactiv gets your hours from your employer. You can move earned wages to a bank, a card, Venmo, PayPal, or Walmart. You can also spend earned wages on bills and Amazon orders. Your employer deducts the total on payday. Payactiv says the amount “appears as a line item on your pay stub.” Our guide to how Payactiv works covers each step.
Payactiv vs ZayZoon fees: which costs less?
Payactiv costs less when you want cash in your own bank. ZayZoon ties at $0 when you spend from its card. ZayZoon’s worst case is $5 a transfer. Payactiv’s main instant fees top out at $3.49.
ZayZoon’s fees
ZayZoon charges up to $5 for a Near Instant transfer, including Venmo and Zelle, according to its USA EWA Terms of Service. The terms say “the Near Instant Transfer fee will not exceed $5 per transfer.” Payouts to the ZayZoon Visa Card and to Boost gift cards cost $0. Connecticut residents pay $4 for an expedited transfer and get one a pay period.
ZayZoon says its fee “is not dependent on the amount that you request.” A $20 payout and a $200 payout cost the same. Your employer can elect to pay the fee for you, and ZayZoon may lower or waive it with a discount. ZayZoon lists no subscription, membership, enrollment, maintenance, inactivity, cancellation, or termination fees. On its employee page, ZayZoon advertises gift card bonuses “up to 25%” and a 5% bonus on its gas card.
Payactiv’s fees
Payactiv charges $0 for ACH to your bank in one to three business days, according to its pricing page. Instant transfers to the Payactiv Visa Card cost $0 too, in any pay period with a $200 direct deposit to the card. Without the deposit, Payactiv charges a $2.49 “load fee.” Cash App costs $3.24 in an Early Adopter Program. Other debit or payroll cards, Venmo, PayPal, and Walmart Cash Pickup cost $3.49.
Payactiv adds that “fees and available transfer options may vary by program.” Our Payactiv fees page lists every charge with worked examples.
The card fees after the free transfer
ZayZoon’s free path comes with a $2.50 ATM fee, and Payactiv’s comes with $2.95 exit fees for wallets and linked cards. Check both before you call either path free.
ZayZoon’s card FAQ lists a $2.50 ATM withdrawal fee and a $1.00 ATM decline fee. ZayZoon also charges $0.50 for a balance inquiry, $3.95 for a cash reload, and $4.95 for a replacement card. ZayZoon names no free ATM network on that page. Payactiv’s fee schedule lists $0 at MoneyPass ATMs, $2.95 out of network, and $0.50 for a balance inquiry. Payactiv also charges $2.95 to move card money out through digital wallets, linked debit cards, or banking apps. If you pull cash from the card, Payactiv’s MoneyPass option costs nothing, and every ZayZoon withdrawal costs $2.50.
Cost per transfer and per year
| $100 for 7 days | Fee | APR equivalent | 27 uses a year |
|---|---|---|---|
| ZayZoon Visa Card or Boost gift card | $0 | 0% | $0 |
| Payactiv ACH, or its card with $200+ deposit | $0 | 0% | $0 |
| Payactiv instant to its card, no deposit | $2.49 | 130% | $67.23 |
| Payactiv to Cash App (early adopters) | $3.24 | 169% | $87.48 |
| Payactiv to a debit card, Venmo, or PayPal | $3.49 | 182% | $94.23 |
| ZayZoon Near Instant, Connecticut | $4.00 | 209% | $108.00 |
| ZayZoon Near Instant, at its ceiling | $5.00 | 261% | $135.00 |
To get the APR equivalent, divide the fee by the amount, multiply by 365, and divide by the days until payday. The yearly column uses the CFPB’s July 2024 Data Spotlight, which found about 27 earned wage transactions per worker a year. The CFPB put the average transfer at $106 and the average fee at $3.18.
How much can you get from each?
Both cap you near 50% of earnings. ZayZoon limits you to one $200 payout a day. Payactiv lets you take up to $500 a pay period in one transfer. That payout cap matters most when a big bill lands.
ZayZoon’s help center says it “provides access to a percentage of your earnings before payday (up to 50%).” ZayZoon sets a “maximum of $200 per payout” and allows “only one payout per day.” The pay-period limit is “typically capped around $1000.” You need at least $20 available to request a payout. ZayZoon’s employer help article lists the same defaults and says employers can lower the percentage below 50%. ZayZoon warns that a lower percentage can mean smaller payouts “with a transaction fee each time.”
Payactiv’s get-started FAQ says, “In most cases, employees can access up to 50% of earned wages, with a maximum of $500 per pay period.” With direct deposit to the Payactiv Visa Card, “you may be able to access up to $1,000 per request.” Payactiv doesn’t publish a daily payout limit.
Run a $500 rent shortfall through both. On Payactiv, one ACH transfer costs $0, and one debit card transfer costs $3.49. On ZayZoon, you need three payouts over three days ($200, $200, and $100). That’s $0 to the ZayZoon card, or up to $15 if you send all three to your bank.
Worker protections in writing
ZayZoon puts more protections in its terms than Payactiv publishes, which is ZayZoon’s strongest edge in this matchup. ZayZoon’s terms say it “will not debit, withdraw from, or otherwise take payment from any of your bank accounts” to recover a payout. ZayZoon also says it “will not perform credit checks on you” and “does not accept tips, gratuities, or donations.”
ZayZoon also promises that payouts “are issued on a nonrecourse basis.” Except for fraud or intentional misrepresentation, ZayZoon won’t pursue you personally if payroll falls short. ZayZoon’s remedies stop at suspending your access and recovering the money from a future paycheck.
Payactiv collects through payroll, so repayment can’t overdraw your checking account. Payactiv says its service “is not a loan or an advance against future earnings” and charges “no interest.” Payactiv doesn’t publish what happens if your paycheck comes up short. We found no earned wage access user agreement on its public site.
The CFPB’s December 2025 advisory opinion says “Covered EWA” isn’t credit under federal Truth in Lending rules. To qualify, a provider collects through payroll and gives up recourse against the worker. ZayZoon’s terms state both conditions. Our guide on whether earned wage access is a loan explains the test.
Payactiv vs ZayZoon for employers
Neither company publishes an employer price above $0, so employers should compare payroll fit, worker fees, and licensing. ZayZoon’s employer page says “ZayZoon doesn’t cost you a cent.” Payactiv says employers “can offer Payactiv Earned Wage Access to employees at no cost.” ZayZoon’s terms also let an employer pay its workers’ fees.
Payroll integrations
ZayZoon gives two counts. On its homepage, ZayZoon claims “300+ payroll partners.” On its employer page, ZayZoon says it “integrates with 130+ payroll providers” and can have you running “in less than 30 minutes.” ZayZoon’s ADP Marketplace listing covers ADP Workforce Now Next Gen. In an October 8, 2026, release, ZayZoon said UKG picked ZayZoon as the exclusive earned wage access provider for UKG Wallet in UKG Ready. The rollout starts in early 2027.
Payactiv says it “connects to 150+ payroll and workforce systems” and names ADP, Paychex, UKG, Paycor, Oracle, and Workday as active partnerships. Payactiv powers UKG Wallet today, plus Pay on Demand in Paychex Flex and OnDemand Pay in the Paycor app. If your company runs UKG Ready, expect your UKG Wallet provider to change from Payactiv to ZayZoon in 2027. Expect a new fee table.
Licenses
ZayZoon lists NMLS ID 2635812 in its terms, along with California DFPI registration 04-CCFPL-2635812-3480665 and licenses in Kansas, Maryland, and Nevada. ZayZoon says its Indiana application is in process. It names regulators in Connecticut, South Carolina, Utah, and Wisconsin without license numbers. Payactiv lists NMLS ID 2591928 and Wisconsin license 2591928EWA. The CFPB issued Payactiv an approval order in December 2020 and ended it in June 2022 at Payactiv’s request. We found no regulator action against ZayZoon on official sources.
Our earned wage access laws tracker lists the states with their own rules. Our best earned wage access providers roundup compares the full employer field.
The catch with each
ZayZoon’s catch is the route to your bank, which always costs up to $5, plus its $200 payout cap. Payactiv’s catch is the condition on its free card path.
ZayZoon’s catches
- You can’t move money to your own bank for free.
- ZayZoon allows one payout a day, up to $200, so a big bill takes several days and several fees.
- The ZayZoon card charges $2.50 per ATM withdrawal, according to its FAQ.
- Gift card bonuses beat cash only if you’d shop at that brand anyway.
Payactiv’s catches
- The free instant path requires a $200 direct deposit to the Payactiv Card every pay period.
- Payactiv’s pricing page says only “a portion” of earned wages. Its get-started FAQ gives 50% and $500 “in most cases.”
- Payactiv charges $2.95 to move card money out through wallets, linked cards, or banking apps.
- Payactiv doesn’t publish a rule for a paycheck that comes up short.
Payactiv vs ZayZoon: which should you use?
Your employer picks the provider, so use the one you have and take its free path. When you compare job offers or suggest a provider to HR, weigh the free bank transfer against the written protections.
Pick ZayZoon if
- Your employer’s payroll company partners with ZayZoon, or your company runs UKG Ready after the 2027 rollout.
- You’ll spend from the ZayZoon card or use gift cards, so payouts cost $0.
- You need $200 or less at a time.
- You want the nonrecourse and no-bank-debit promises in writing.
Our guide to apps like ZayZoon covers other employer programs with a free bank transfer.
Pick Payactiv if
- Your employer, Paychex, Paycor, or UKG Wallet offers Payactiv.
- Your bills auto-pay from your current bank, and you can wait one to three business days for $0 ACH.
- You need up to $500 at once.
- You’ll route $200 of each paycheck to the Payactiv Card for free instant transfers and free MoneyPass ATM cash.
Our Payactiv review has the full verdict. With either app, a transfer every pay period points to a budget gap. A starter emergency fund costs $0 to use and beats both.
Payactiv vs ZayZoon FAQ
Payactiv vs ZayZoon: the bottom line
Payactiv wins on cost and size. You get a $0 bank transfer, a $3.49 ceiling on its main instant fees, and up to $500 at once. ZayZoon wins on written protection, with no bank debits, no recourse, no tips, and no credit checks. If your employer offers ZayZoon, keep payouts on its card and plan around the $200 daily cap. If your employer offers Payactiv, take the ACH transfer when the bill can wait two days.
For more matchups, read Payactiv vs Tapcheck, Payactiv vs DailyPay, Payactiv vs EarnIn, Payactiv vs Wisely, and Payactiv vs Paychex. Our earned wage access fees table puts every provider side by side.
Free guide
Spend less, earn more, and grow your wealth
Get my free 2026 Playbook with a checklist for your budget, credit, investing, and side income, plus the free 7-day Bootcamp.
- Track your money with the tools that still work in 2026.
- The order to invest in, with the 2026 401(k) and IRA limits.
- Three ways to earn your first $100 on the side this month.
Bonus: The 7-day Personal Profitability Bootcamp, one short lesson in your inbox each day