
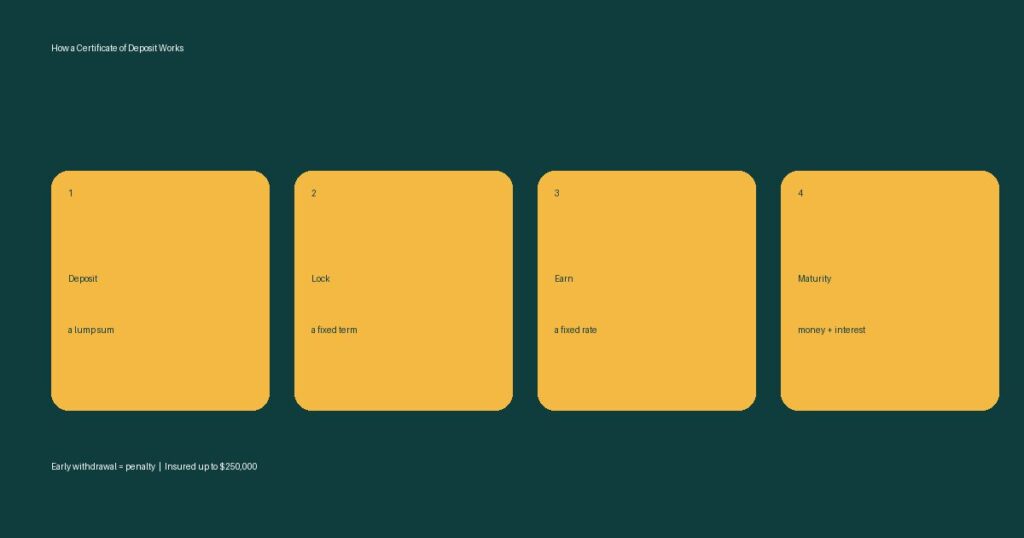
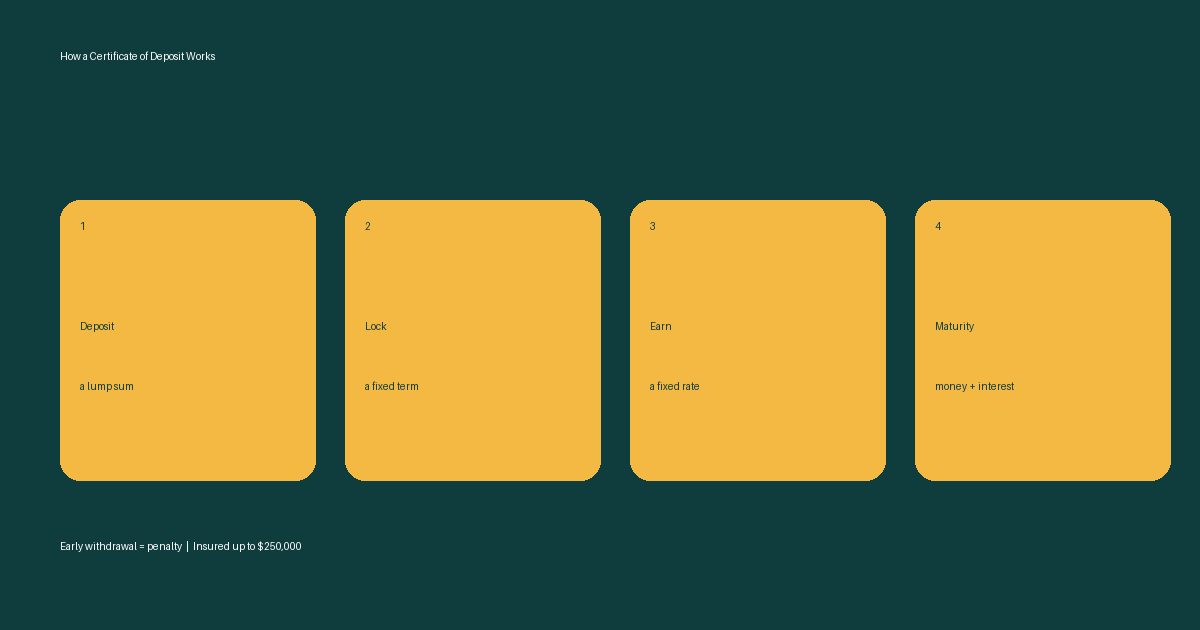
How does a certificate of deposit work? You lend a bank or credit union a lump sum for a set time, and it pays you a fixed interest rate in return. Leave the money alone until the term ends and you get your original deposit plus the interest. Pull it out early and you pay a penalty. A CD is a savings account with a lock on it, and the lock is what buys you the guaranteed rate. If you want flexibility instead, a high-yield savings account is the other option to weigh.
How Does a Certificate of Deposit Work? The Basics
A certificate of deposit, or CD, is a deposit account with a fixed term and a fixed rate. You pick the term, which can run from a few months to several years. You deposit a lump sum. The bank agrees to pay a set rate for that whole stretch, no matter what rates do in the meantime.
That’s the trade. You give up easy access to the money. The bank gets a predictable pool of cash it can lend out. In return, it usually pays a higher rate than a regular savings account, though that gap changes with the market and with each bank. Check the current rate on the bank’s own page before you commit.
You can open a CD at a bank or at a credit union. At a credit union, it’s often called a share certificate. They work the same way for you.
Build an excellent credit score without paying interest
Get my free 2026 guide to how credit scores work, what moves them and how to fix mistakes on your credit report.
The Parts of a CD: Term, Rate, and Maturity
Every CD comes down to four pieces. Know them and you can read any offer in a minute.
| Part | What it means | What to check |
|---|---|---|
| Term | How long your money stays locked up | Longer terms often pay more, but not always |
| Rate (APY) | The yearly return, including compounding | Compare APY to APY, not APY to a plain rate |
| Minimum deposit | The least you can open the CD with | Varies by bank, and some have none |
| Maturity date | The day the term ends and your money is free | Mark it on your calendar |
The APY, or annual percentage yield, is the number to compare. It folds in how often the interest compounds, so two CDs with the same stated rate can have slightly different APYs. Banks have to show you the APY and the penalty terms before you open the account, so ask for the fee schedule if you can’t find it.
Once you have the APY, the math takes one line. Take a hypothetical $10,000 in a one-year CD at a 4.00% APY. At maturity you’d have about $10,400, because the APY already counts the compounding. Real rates move with the market. CD rates tend to rise and fall with the Federal Reserve’s rate decisions, so the rate you see today may not be there next month.
Maturity is the part people forget. When the term ends, most banks give you a short grace period to withdraw, move, or change the money. If you do nothing, many banks roll the CD into a new one at whatever rate is current. That rate may be worse than the one you started with. Read your account terms so you know what your bank does by default.
Is Your Money Safe in a CD?
Yes, up to the insurance limit. The FDIC’s standard coverage is $250,000 per depositor, per insured bank, for each account ownership category, and CDs are on its list of covered deposits. You can read the details on the FDIC deposit insurance page.
Credit unions have the same standard. The NCUA insures share certificates up to $250,000 per member, per credit union, per ownership type. See the NCUA share insurance page for the rules.
Confirm the institution is FDIC or NCUA insured before you send money. With more than $250,000 to park, spread it across banks or ownership categories so every dollar is covered. A CD from an insured bank is one of the lowest-risk places to keep cash, and the main risk left is the lock itself.
What Happens If You Cash Out a CD Early?
You pay an early withdrawal penalty. Banks set their own penalty and it usually scales with the term, so a longer CD costs more to break. It’s most often charged as a set number of days or months of interest. Federal rules set a floor. The OCC’s consumer help site notes that if you withdraw within the first six days after deposit, the penalty is at least seven days of simple interest. There is no federal cap, so the bank decides the rest. See the OCC page on CD penalties.
On a short CD held for a short time, the penalty can eat most or all of the interest you earned. On a longer CD, you can lose part of your principal if you haven’t earned enough interest yet. That’s why you read the penalty before you open the account, not after you need the cash.
So don’t put your emergency money in a CD. Keep that in a liquid account first. If you haven’t built one yet, start with our guide to emergency funds. Use CDs for money you already know you won’t touch, like a down payment you’ll need in two years.
How CD Interest Is Taxed
CD interest is taxable income. IRS rules say you generally count it in the year you receive it or can withdraw it without a substantial penalty, even if you leave it sitting in the CD. On a CD that defers interest for more than a year, the original issue discount rules usually make you report some interest each year before you see it. Your bank sends a Form 1099-INT, and you owe the tax whether or not a form shows up. IRS Publication 550 covers interest income in detail.
If you pay an early withdrawal penalty, you can usually deduct it. Publication 550 says you report the full interest from Box 1 of your 1099-INT, then deduct the penalty shown in Box 2 on Schedule 1 of Form 1040. That means a broken CD still hands you a partial tax break. Any tax program or preparer can walk you through it.
Types of CDs: Which One Fits?
The standard CD is the simplest, but banks sell a few variations. Each one changes the trade between rate and flexibility.
| CD type | How it works | Best for |
|---|---|---|
| Traditional | Fixed term, fixed rate, penalty for early exit | Money you can leave alone |
| No-penalty | Lets you withdraw early without a fee, often after a short waiting period | People who want a fixed rate and an exit |
| Bump-up | Lets you request a rate increase if the bank’s rate rises | Rising-rate markets |
| Jumbo | Large minimum deposit, sometimes a higher rate | Big lump sums |
| Brokered | Sold through a brokerage and can be sold on a secondary market | Experienced savers comfortable with the extra steps |
| Callable | The bank can end the CD early and return your money, usually when rates fall | Savers who read the call terms first |
Sell a brokered CD before maturity and you get the market price, which can be less than you paid if rates have gone up. No-penalty CDs often pay a little less than traditional ones, so the flexibility has a price. Terms differ by bank, so read the specific product before you decide.
How to Open a CD, Step by Step
Opening one takes about as long as opening any savings account. Six steps cover it.
- Decide the job for the money. A CD works for cash you won’t need before the term ends. Set that date first.
- Pick a term that matches the date. If you need the money in 18 months, don’t buy a five-year CD because the rate looks better.
- Compare APYs from several places. Check online banks, local banks, and credit unions. Use each institution’s own rate page for the current number.
- Confirm the insurance. Make sure the bank is FDIC insured or the credit union is NCUA insured.
- Read the penalty and the maturity rules. Find the early withdrawal penalty and what happens when the term ends.
- Fund it and set a reminder. Put the maturity date on your calendar a couple of weeks early so you can decide what comes next.
CD Ladders: A Simple Way to Stay Flexible
A CD ladder splits your money across CDs with different terms. Say you have $5,000. You could put $1,000 each into a one-year, two-year, three-year, four-year, and five-year CD. As each one matures, you either use the cash or reinvest it into a new five-year CD. After a few years, you have a CD maturing every year and you’re earning longer-term rates.
A ladder smooths out two risks. You aren’t betting everything on today’s rate, and you always have some money coming free. It takes a little more tracking, but it fixes the biggest complaint about CDs, which is being locked in.
CD vs. High-Yield Savings: Which Is Better?
Neither wins every time. A high-yield savings account has a variable rate. It can drop whenever the bank decides, but you can withdraw anytime. A CD locks the rate and the money. When rates are falling, a CD protects your return. When rates are rising, a savings account lets you catch the increase.
Two more options sit nearby. A money market account is a bank deposit with a variable rate and often check-writing, and it’s insured like savings. Treasury bills are short-term loans to the federal government, sold through TreasuryDirect or a brokerage, and their interest is exempt from state and local income tax. Either can beat a CD in some markets, so compare all three before you lock in.
My default is simple. Emergency fund goes in the savings account. Money with a known date goes in a CD. That way you never pay a penalty to cover a surprise, and you earn a guaranteed rate on cash you were never going to spend anyway. If you’re still deciding where your savings should live, our high-yield savings guide covers the other side of this choice.
Conclusion
A CD is a simple deal. You give up access, and the bank gives you a guaranteed rate and federal insurance up to the limit. It’s a good tool for money with a known date and a bad one for emergency cash. Match the term to your timeline, read the penalty, and check the maturity rules.
Want more on where to keep your savings? Start with how a high-yield savings account works, then build a safety net with our emergency funds guide. If you’re trying to reach a bigger goal, see how to find the cash with zero-based budgeting. You can also browse the rest of our personal finance guides.
Free guide
Build an excellent credit score without paying interest
Get my free 2026 guide to how credit scores work, what moves them and how to fix mistakes on your credit report.
- The five factors FICO uses and how much each one counts
- How long late payments, collections and medical bills can stay
- A step-by-step plan to raise your score and dispute errors
Bonus: The Debt Payoff Plan, a worksheet to list your balances and pick a payoff order