Here’s how a traditional IRA works: you put in pre-tax or tax-deductible money up to a yearly limit, your gains stay tax-deferred, and you pay ordinary income tax when you take it out in retirement. It’s one of the simplest ways to save for retirement on your own, whether or not you have an employer-sponsored plan like a 401(k). If you’re building your income as a freelancer or side hustler, you also get a place to save that doesn’t depend on a boss.
How does a traditional IRA work in plain terms?
A traditional IRA is an individual retirement account you open yourself at a financial institution, such as a bank, brokerage, or robo-advisor. You fund the account with money you earned, pick its investments, and leave the balance alone until retirement. The account is the container. What you buy inside it (index funds, mutual funds, target-date funds, or a CD) is a separate decision.
The tax break comes in two parts. First, your contribution may be deductible, which lowers your taxable income this year. Second, the IRS says it generally doesn’t tax the amounts in your traditional IRA, including earnings and gains, until you take a distribution. You pay the bill later, at whatever ordinary income rate you’re in then.
That trade is the whole point. You skip tax now and pay it in retirement, which makes sense if you expect to be in a lower bracket later. If you expect a higher bracket, you may come out ahead with a Roth. Read our guide to Roth IRAs for beginners for that side of the choice.
Learn how the stock market works, then start
Get my free 2026 guide to stocks, trades, account types, and index funds, plus a step-by-step plan for your first investment.
How much can you contribute to a traditional IRA in 2026?
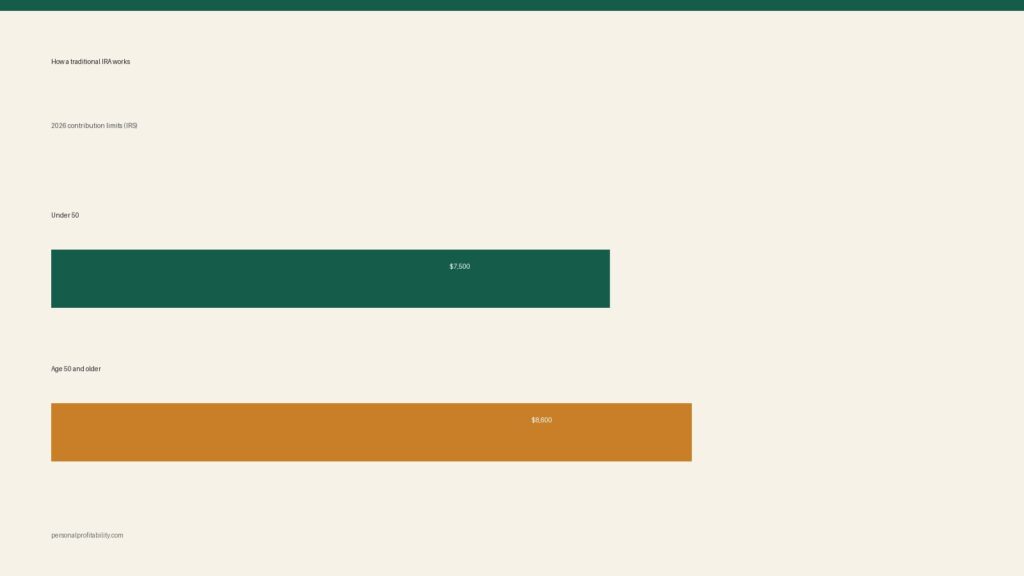
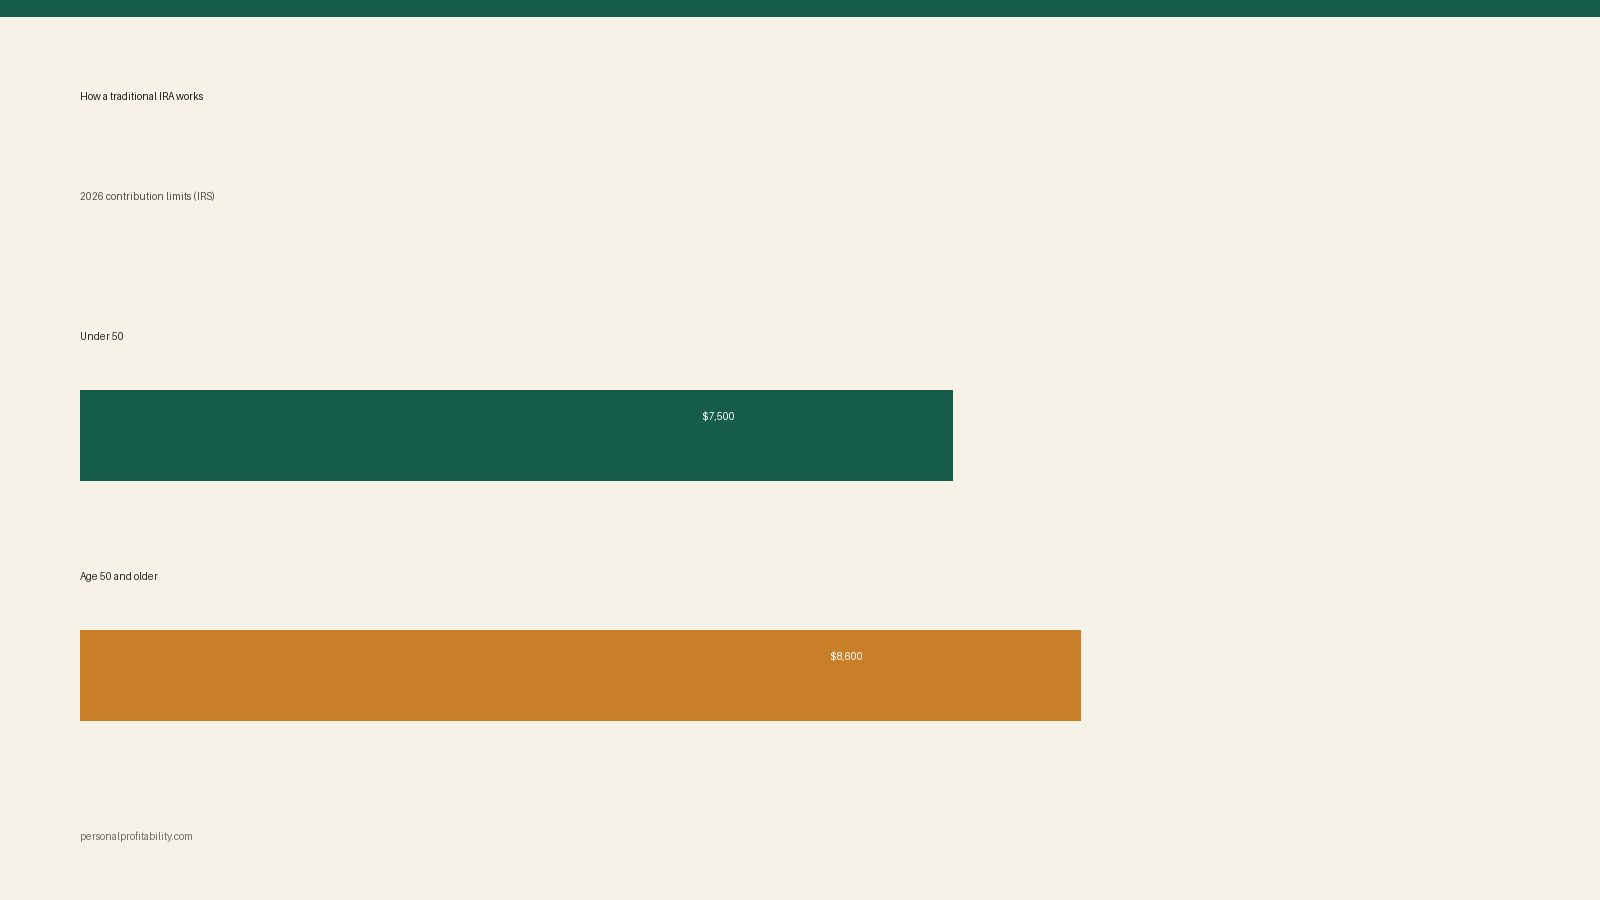
The traditional IRA contribution limit is $7,500 for 2026, or $8,600 if you’re 50 or older, according to the IRS IRA contribution limits page. The IRS applies that limit to all your traditional and Roth IRAs combined, so $7,500 split across two accounts is still $7,500.
| Tax year | Under 50 | Age 50 and older |
|---|---|---|
| 2025 | $7,000 | $8,000 |
| 2026 | $7,500 | $8,600 |
Your contribution also can’t exceed your taxable compensation for the year. If you earned $4,000 from a part-time gig, $4,000 is your ceiling. Wages, self-employment income, and similar earnings count. Investment income and rental income generally don’t.
A spouse with no income of their own can still contribute. On a joint return, the IRS lets a spouse without compensation contribute based on the other spouse’s pay, as long as the combined contributions stay within the compensation on the return.
You can make a contribution for a tax year during that year or up to the filing deadline, without extensions. For most people, that means you can still fund a 2025 IRA until April 15, 2026, according to IRS Publication 590-A.
Is a traditional IRA contribution tax deductible?
If neither you nor your spouse has a workplace retirement plan, you can deduct the full amount. If you have a plan at work and a high income, you may get a smaller deduction or none at all. The IRS publishes new phase-out ranges each year. Here are the 2026 figures from the IRS announcement of 2026 limits.
| Your situation | 2026 deduction phase-out (modified AGI) |
|---|---|
| Single, covered by a workplace plan | $81,000 to $91,000 |
| Married filing jointly, you have a workplace plan | $129,000 to $149,000 |
| Married filing jointly, only your spouse has a workplace plan | $242,000 to $252,000 |
| Married filing separately, covered by a workplace plan | $0 to $10,000 |
Below the range, you deduct the full contribution. Inside it, you deduct a partial amount. Above it, you get no deduction, but you can still contribute. If neither spouse has a workplace plan, the phase-out doesn’t apply at all.
Say you’re single, you have a 401(k) at work, and your modified AGI is $70,000. You’d deduct the full $7,500 contribution. At $86,000, you’re in the phase-out range and you’d deduct only a portion. At $95,000, the deduction is gone.
You can still make a nondeductible contribution, but you’ll need to do some paperwork. The IRS says you must file Form 8606 when you make nondeductible contributions to a traditional IRA, and you use it to track your basis (the money you already paid tax on) so you don’t pay tax twice on the same dollars.
What happens when you take money out of a traditional IRA?
The IRS generally taxes withdrawals as ordinary income, and if you take money out before age 59½ you usually owe an extra 10% tax on the taxable part. The IRS says the 10% additional tax applies to the part of the distribution you have to include in gross income, and you report it on Form 5329 or Schedule 2 of your Form 1040.
The IRS lists exceptions to that 10% tax. A few of the common ones:
- Total and permanent disability
- Up to $10,000 for a qualified first-time home purchase
- Qualified higher education expenses
- Up to $5,000 for a qualified birth or adoption
- Substantially equal periodic payments over your life expectancy
- Unreimbursed medical expenses above a set share of your adjusted gross income
An exception only gets you out of the 10% tax. You still owe regular income tax on a withdrawal. The full list lives in IRS Tax Topic 557 and Publication 590-B.
When you pull money out early, you also give up the growth. Take $10,000 out at 35 and you usually pay income tax plus the 10% additional tax, and you give up 30 years of compound growth before age 65. Treat an IRA as retirement money and keep a separate cash cushion for emergencies. You can build one with a sinking fund, and you’ll find the steps in our post on how to start a sinking fund.
When do you have to start taking money out?
The IRS says you generally have to start required minimum distributions (RMDs) when you reach age 73, and your first one is due by April 1 of the year after you reach that age. After that, you take one every year by December 31. Congress has changed this age before, so check the IRS RMD page before you plan your withdrawals.
Missing an RMD is expensive. The IRS says it may charge a 25% excise tax on the amount you didn’t withdraw, and the rate drops to 10% if you correct the mistake within two years. You can file Form 5329 and ask the IRS to waive the penalty for a reasonable error.
There’s no age cap on contributing anymore. Since 2020, you can keep adding to a traditional IRA at any age as long as you have taxable compensation.
Traditional IRA vs Roth IRA, 401(k), and SEP IRA
Your pick depends on how you earn and how much you want to save. The traditional IRA is the simplest option, and many people pair it with a workplace plan instead of choosing one over the other.
| Account | Tax break | 2026 limit | Who it fits |
|---|---|---|---|
| Traditional IRA | Possible deduction now, taxed on withdrawal | $7,500 ($8,600 at 50+) | Anyone with earned income |
| Roth IRA | No deduction, tax-free qualified withdrawals | Same combined IRA limit, with income limits | Younger earners, or anyone expecting a higher future bracket |
| 401(k) | Pre-tax contributions through payroll | $24,500 in employee deferrals | Employees with a plan, especially with a match |
| SEP IRA | Deductible business contributions | Much higher, based on net self-employment earnings | Freelancers and small business owners |
Start with the match. If your employer offers a match, take the full match first because it’s free money. Then fund an IRA, and consider a Roth when you’re young and in a low bracket. For more on the order, read our breakdown of maxing a 401(k) or a Roth first. Freelancers who want to save more can read how a SEP IRA works or compare a SEP IRA vs a Solo 401(k).
How to open a traditional IRA, step by step
- Confirm you have earned income. Your contribution can’t exceed your taxable compensation for the year.
- Choose a provider. Banks, brokerages, and robo-advisors all offer IRAs. Compare fees, because small costs compound too. Read our guide to IRA fees for the costs to watch.
- Open the account online. You’ll give your Social Security number, a bank account for funding, and a beneficiary.
- Fund it. Transfer money from your bank, ideally on a schedule so you save automatically.
- Pick investments. An S&P 500 index fund or a target-date fund is a sensible default for most people. The money sits in cash until you choose.
- Label the tax year. When you contribute near the tax deadline, label the deposit for the correct tax year.
- Keep the paperwork. Save the Form 5498 your provider sends, and file Form 8606 if any contribution was nondeductible.
You can also move an old workplace plan into a traditional IRA with a rollover. If you’re doing that, read about rolling over an old 401(k) first so you move the money directly and avoid a tax bill.
Mistakes that cost people money
- Over-contributing. The IRS taxes excess contributions at 6% per year while they stay in the IRA. You can fix the error by withdrawing the excess and its earnings by your return’s due date, including extensions.
- Assuming the deduction is automatic. Workplace coverage and income can reduce the deduction, so check the ranges above before you plan your tax bill.
- Leaving the money in cash. Contributing isn’t investing. Many people fund an IRA and never pick a fund.
- Skipping the beneficiary. Your IRA provider generally pays the account to the person named on your beneficiary form, even if your will says something else.
- Raiding it early. Between income tax and the 10% additional tax, you usually lose far more to an early withdrawal than you’d expect.
Traditional IRA FAQ
Your next step with a traditional IRA
You’ll get the most from a traditional IRA when you treat it as a long-term account: contribute what you can, claim the deduction if you qualify, invest the money, and leave it alone until retirement. For 2026 the limit is $7,500, or $8,600 at 50 and older, so even a monthly automatic transfer adds up.
If you want more retirement ideas, browse the retirement archive or start from the Personal Profitability homepage. Confirm your own deduction and tax situation with a fee-only fiduciary or a tax professional before you file.
Free guide
Learn how the stock market works, then start
Get my free 2026 guide to stocks, trades, account types, and index funds, plus a step-by-step plan for your first investment.
- How a trade works, from order types to T+1 settlement.
- Why I start with low-cost index funds instead of stock picks.
- The margin rules and my own trading mistakes, so you can avoid the same errors.
Bonus: The First-Investment Checklist, the order to handle your match, debt, and savings